

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Insect Growth Regulators Market to Climb from USD 1,105.04 Million in 2025 to USD 1,607.48 Million by 2032 at a 5.5% CAGR

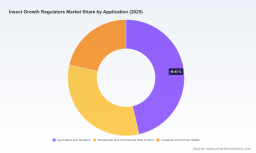
Worldwide Insect Growth Regulators Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Insect Growth Regulators (IGR) market provides an executive-grade roadmap designed to inform capital allocation, product strategy, and regulatory positioning for 2026. Anchored on a 2025 base year and a forward-looking 2026–2032 forecast window, the analysis quantifies the market’s trajectory — a mid-single-digit compound annual growth rate (CAGR) and a clear expansion of the total addressable market over the forecast period — while delivering practical, decision-ready insight without exposing the proprietary line-item breakdowns that underlie our models.
Worldwide Paid Email Service Market
Why this report matters in 2026
-
Market momentum: After robust recovery and reinvestment across agriculture, urban pest management and animal health channels in the early 2020s, the IGR market is growing steadily. Our base-year assessment for 2025 and modeled trajectories through 2032 reflect an expansion consistent with sustained demand for selective, resistance-managing chemistries and an increase in professional pest-control spending globally.
Fixed Medical Pendant Market -
Consolidation and concentration: Competitive dynamics are neither fragmented nor monopolistic — market concentration is meaningful and favors incumbent global crop protection and specialty chemical players. This concentration creates both barriers to entry and strategic corridors for targeted M&A and portfolio carve-outs. Our concentration metrics show that the top-tier players account for a substantial share of the market, providing scale advantages in R&D, registrations and channel access.
Coagulation Test Kit Market -
Regulatory and stewardship pressure: Regulatory scrutiny continues to shape product design and go-to-market choices. Labeling requirements that reflect slower developmental activity, product group classifications tied to insect life-cycle stages, and use restrictions on certain granular formulations are forcing manufacturers to reengineer registrational strategies and stewardship programs.
-
Innovation vectors: Product innovation is moving on at least three axes — new modes of action and chemistries (including next‑generation ketoenols), formulations engineered for systemic activity and minimal residues, and application innovations supporting integrated pest management (IPM) in greenhouses, livestock systems and urban environments.
What the PW Consulting report delivers — practical assets for 2026 execution
-
Demand model with scenario capability: A flexible, auditable forecast model that converts macro drivers (crop prices, urbanization, livestock intensification, regulatory timelines) into demand volumes and revenue ranges under three planning scenarios.
-
Regulatory heat map and tracker: A rolling assessment of registration risks and label constraints across major jurisdictions, with distilled guidance on likely approval timelines and label language that materially affects adoption and use patterns.
-
Commercial playbooks: Channel-specific GTM modules for agriculture, professional pest management and animal health that prescribe packaging, pricing and distribution approaches tailored to each channel’s procurement dynamics and stewardship requirements.
-
Product portfolio optimization toolkit: A profitability and risk matrix that flags candidates for lifecycle extension, reformulation, or divestiture — designed to support 2026 budget allocation and R&D prioritization.
-
Competitive scorecards and M&A screening: Qualitative and quantitative assessment of the major market participants, plus acquisition target archetypes and a tactical M&A playbook for rapidly capturing niche growth pockets.
Competitive landscape — strategic implications for leading players
-
BASF SE — With a broad crop protection portfolio that includes chitin synthesis inhibitors and juvenile hormone analogs, BASF’s scale and channel reach enable it to defend premium agricultural segments. Strategic focus for 2026: leverage formulation know‑how to extend patent cliffs and bundle IGRs into integrated solutions that emphasize resistance management.
-
Bayer AG — The introduction of next-generation ketoenol products with systemic movement marks Bayer’s intent to own sap-feeder control and seed/foliar systemic plays. Strategic focus: accelerate seed-to-harvest stewardship pilots and explore subscription or service models that pair systemic IGRs with monitoring technology.
-
Syngenta AG — Syngenta’s expansion of urban-control formulations underscores a dual play across agriculture and professional pest control. Strategic focus: capitalize on urban pest resistance cycles by broadening monitoring partnerships with facilities management firms.
-
Sumitomo Chemical — Specialization in low‑residue chitin synthesis inhibitors for rice and horticulture offers a defensive moat in sensitive cropping systems. Strategic focus: protect regulatory advantages and explore label expansions into adjacent high-value vegetable and fruit markets.
-
Corteva Agriscience — As an integrated crop protection player, Corteva is positioned to embed IGRs into broader IPM portfolios. Strategic focus: orchestrate bundled offers that combine cultural, biological and chemical controls to preserve efficacy and rationalize application windows.
-
FMC Corporation — FMC’s portfolio emphasis on agricultural and speciality pest control enables nimble responses to niche opportunities. Strategic focus: cultivate specialty distribution partners and accelerate registration in underserved regulatory corridors.
-
ADAMA Ltd. — Recent launches for greenhouse thrips and whiteflies demonstrate ADAMA’s capability to win in regulated, high-margin horticultural niches. Strategic focus: double down on formulatory agility and local regulatory compliance to defend greenhouse channels.
-
Nufarm Limited — As a global supplier, Nufarm can flex across regions but must prioritize capital allocation. Strategic focus: prioritize scale plays in high-growth value chains while outsourcing complex registrations.
-
Valent U.S.A. LLC — U.S.-focused offerings position Valent to exploit domestic urban and agricultural demand. Strategic focus: align stewardship programs with state-level regulatory trends and professional applicator training.
-
Central Life Sciences — Specialization in feed-through products for livestock illustrates the value of targeted, channel-specific chemistries. Strategic focus: extend partnerships with animal health integrators and demonstrate ROI through field efficacy studies.
-
MGK — Focus on poultry and professional fly control gives MGK a durable niche. Strategic focus: convert technical leadership into bundled service contracts with major integrators.
-
Russell IPM — Niche developer and supplier to integrated pest management programs, with strength in horticulture and on‑farm solutions. Strategic focus: build licensing and white‑label partnerships with larger distributors.
Regulatory and supply‑chain dynamics to watch in 2026
-
Label-driven differentiation: Several IGR products carry regulatory labeling that reflects delayed developmental activity, group‑specific classifications and use restrictions in sensitive ecosystems. These constraints can materially affect application frequency and perceived value — and should be embedded into pricing and stewardship strategies.
-
Formulation constraints: Certain granular formulations have explicit use restrictions in particular crop types (e.g., rice paddies). Manufacturers must coordinate formulation R&D with regulatory teams to preserve addressable use cases.
-
Intermediates and raw materials: Synthesis of many IGR active ingredients depends on specialized intermediates (for example, phenoxyphenyl derivatives and juvenile hormone analog precursors). Securing upstream supply, qualifying secondary suppliers, and building inventory buffers are prudent actions to mitigate input volatility.
-
Resistance management and stewardship: EPA and other regulators increasingly expect active stewardship programs that limit resistance risk. This creates differentiation opportunities for firms that pair chemistry with monitoring, application guidance and education services.
Scenarios and recommended strategic moves for 2026
-
Baseline acceleration (most likely): Moderate demand growth persists as agronomic and urban spending trends continue. Recommendation: Invest selectively in reformulations that extend label life, scale targeted field trials to support premium pricing, and lock key intermediates with multi-year supply agreements.
-
Innovator upgrade (high-opportunity): Rapid adoption of next-gen systemic and low-residue IGRs in high-value crops and greenhouse systems. Recommendation: Fast-track commercial pilots with premium growers, pursue co-marketing with precision application vendors, and ready regulatory dossiers for adjacent geographies.
-
Regulatory tightening (risk scenario): Accelerated restriction of certain formulations compresses addressable markets in specific use-cases. Recommendation: Rebalance portfolios toward products with favorable residue and toxicity profiles, accelerate IP-protected formulation patents, and evaluate divestiture of at‑risk SKUs.
How PW Consulting partners with executive teams in 2026
-
Rapid-read briefings: Condensed C-suite briefings that translate our full market model into three immediate decisions — where to invest, what to shelve, and whom to partner with this financial year.
-
Regulatory playbook execution: End-to-end support from label language optimization to dossier readiness and regulatory engagement strategy.
-
M&A and carve‑out advisory: Target screening, valuation models that reflect product lifecycle and regulatory tail risk, and diligence playbooks focused on integration value capture for specialty IGR assets.
-
Commercial pilots and channel design: Field-proven go-to-market pilots with KPIs tied to adoption, repeat purchase and stewardship compliance — to de‑risk scale-up decisions.
PW Consulting’s Worldwide Insect Growth Regulators Market study is designed to be both a strategic compass and an operational manual for 2026 — showing where value pools will grow, where regulatory and supply risks concentrate, and the precise tactical moves that unlock ROI. The full report includes our detailed demand model, jurisdictional regulatory trackers, company scorecards and proprietary segmentation analyses. To access the complete intelligence package and the underlying data that informs our recommendations, please visit PW Consulting’s report page and request the full briefing.
For leaders evaluating portfolio shifts, M&A options, or aggressive commercial plays in 2026, this study provides the confidence and practical prescription to act. PW Consulting stands ready to translate these insights into executable plans that preserve efficacy, navigate regulation, and accelerate profitable growth in the evolving IGR landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Insect Growth Regulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com