

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: LPG Market Hits $162M in 2025, Poised for 5.5% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Liquefied Petroleum Gas Market Navigating Growth and Volatility Through 2032
The global Liquefied Petroleum Gas (LPG) market stands at a critical inflection point, shaped by shifting geopolitical dynamics, evolving energy security priorities, and accelerating adoption of cleaner cooking and transportation fuels. As enterprises navigate an increasingly complex macroeconomic environment, access to granular, forward-looking intelligence is no longer optionalit is a strategic imperative. Our latest market research on the LPG sector delivers precisely that: a comprehensive, data-rich blueprint designed to inform investment allocation, supply chain optimization, competitive positioning, and regulatory risk mitigation through 2032.
LPG Cylinder Market
Market Trajectory and Structural Growth Drivers
Between 2020 and 2025, the LPG market demonstrated consistent expansion, with revenue climbing from approximately 136.55 million in 2020 to 162.0 million by 2025. The momentum carries firmly into the forecast horizon, projecting sustained growth that peaks at 235.43 million by 2032. This trajectory reflects a compound annual growth rate of 5.5 percent over the 2026-2032 window, underscoring the commodity's resilience and its expanding role in the global energy mix.
Several structural forces are propelling this expansion. First, LPG continues to serve as a vital bridge fuel in regions undergoing rapid energy transition, particularly where grid reliability remains inconsistent or where governments are phasing out traditional biomass for household cooking. Second, industrial demand is being reinforced by petrochemical feedstocks and manufacturing processes that require stable, high-energy-density inputs. Third, regulatory frameworks in multiple jurisdictions are increasingly favoring lower-emission alternatives to diesel and coal, indirectly accelerating LPG adoption in both stationary and mobile applications. Finally, supply chain adaptations, including strategic inventory positioning and route optimization, are helping market participants navigate freight volatility and tariff adjustments that emerged in recent years.
It is important to recognize that this growth is neither uniform nor automatic. Regional policy shifts, fluctuating crude and natural gas pricing, infrastructure investment cycles, and evolving trade tariffs all introduce variability that can compress margins or alter demand timelines. Understanding where these variables intersect with your specific operational footprint requires more than high-level market sizing. It demands a disciplined, scenario-aware analytical framework, which our research is built to provide.
Comprehensive Analytical Coverage: What the Research Delivers
Our LPG market study is structured to translate macroeconomic trends into actionable strategic guidance. Rather than offering static snapshots, the report integrates historical performance tracking with forward-looking modeling, allowing decision-makers to stress-test assumptions across multiple time horizons. The methodology combines top-down market sizing with bottom-up segment validation, ensuring that aggregate figures are consistently anchored to real-world operational dynamics.
The research delves deeply into the market's compositional architecture, breaking down the universe into type, application, and geographic dimensions. On the product side, the analysis distinguishes between propane-dominant flows and butane-heavy segments, highlighting how their respective utilization patterns differ across heating, industrial processing, and blending applications. In terms of end-use, the report examines residential consumption patterns, commercial deployment trends, industrial feedstock requirements, and autogas integration in transportation fleets. Each of these segments carries distinct demand elasticities, pricing sensitivities, and substitution risks, and our analysis maps those differences explicitly rather than treating the market as a monolith.
Geographic coverage extends across major production and consumption corridors, capturing how regional supply-demand balances interact with trade flows, port infrastructure status, and localized regulatory environments. The research also addresses the competitive architecture of the market, evaluating concentration metrics, market share distribution among leading operators, and the strategic maneuvers that are reshaping value capture along the supply chain.
Beyond structural analysis, the report integrates operational intelligence that matters directly to corporate planning. This includes an assessment of raw material dependencies, particularly the role of steel in traditional tank and cylinder manufacturing, alongside emerging shifts toward composite vessel technologies. It also examines labor market constraints, as ongoing skilled workforce shortages in the broader oil and gas sector continue to influence project timelines and operational productivity. Regulatory developments are tracked with precision, including tariff carve-outs for specific LPG carriers under long-term charter arrangements, which can materially affect shipping economics and route planning.
The research further captures recent strategic moves and industry events that signal changing competitive dynamics. Divestiture activity in European distribution networks, quarterly financial disclosures from major shipping operators, and active participation in key regional trade exhibitions collectively reveal how incumbents are adjusting asset portfolios, focusing on core competencies, and exploring new geographic or product adjacencies. These developments serve as leading indicators of where capital is flowing and which capabilities are increasingly valued.
Competitive Landscape and Strategic Positioning
The LPG value chain is characterized by a concentrated yet highly differentiated competitive environment. Market structure reflects a mix of integrated energy majors, specialized shipping operators, state-backed producers, and regional distribution leaders, each pursuing distinct strategic logic. At the top of the competitive hierarchy, market concentration remains significant, with the three largest players collectively commanding a substantial share of industry revenue and the top five extending that influence further. This concentration has implications for pricing power, contract negotiation leverage, and the pace at which new entrants can achieve scale.
Leading international energy companies continue to anchor production, trading, and downstream distribution activities, leveraging diversified portfolios that span upstream extraction, midstream logistics, and retail or commercial supply networks. Their scale allows them to absorb short-term volatility, hedge across multiple commodities, and invest in infrastructure that secures supply continuity for key markets. At the same time, these integrated players are increasingly scrutinized on operational efficiency, emissions-related commitments, and capital discipline, which shapes how they prioritize LPG within broader energy portfolios.
Complementing the integrated majors is a cohort of specialized operators whose competitive advantage lies in logistical excellence and asset specialization. Global shipping companies operating modern very large gas carriers play an essential role in connecting production hubs with consumption centers, and their fleet deployment strategies, charter economics, and waiting-time management directly influence regional supply reliability. In parallel, engineering and manufacturing specialists are advancing storage and containment solutions, from conventional steel-based vessels to composite cylinder innovations that emphasize safety, weight reduction, and production scalability. These technology and logistics players may not command headline market share, but they exert outsized influence on total cost structures and service quality across the value chain.
Regional dynamics further complicate the competitive picture. In markets where state-owned enterprises or national conglomerates dominate refining, production, and retail distribution, commercial strategy often intertwines with broader industrial policy objectives, such as energy access, employment, or import substitution. Meanwhile, private distributors and marketers operating across multiple countries must continuously balance regulatory compliance, cross-border logistics, and localized customer relationships. Understanding which competitors hold structural advantages in which contexts, and how those advantages may erode or strengthen over the forecast period, is central to any credible market entry, partnership, or expansion plan.
Time-sensitive developments reinforce the need for continuous competitive monitoring. Recent divestiture activity in parts of Europe highlights how some operators are streamlining portfolios and reallocating capital toward higher-return or more strategically aligned territories. Separately, major shipping and infrastructure players are actively showcasing products and services at prominent industry gatherings, signaling product roadmap directions and partnership ambitions. Financial disclosures from key shipping operators and ongoing trade event participation collectively illustrate a market where asset optimization, regional presence, and technology differentiation are increasingly interlocking strategic priorities.
Macroeconomic and Regulatory Dynamics Shaping the Horizon
LPG market performance does not occur in isolation. Trade policy adjustments have introduced new considerations for long-term charter economics, particularly where tariff modifications have created carve-outs for specific carrier configurations. These changes can alter the cost base for certain shipping routes and influence how traders structure contract portfolios to preserve margin stability. At the same time, feedstock and production patterns in major exporting regions continue to shape global supply availability. Gulf producers have maintained substantial LPG export volumes, reinforcing the region's position as a critical supply node and reinforcing the importance of freight logistics in determining final landed economics.
Labor and skills availability remain a persistent operational variable. Industry-wide constraints on specialized talent can affect everything from vessel maintenance to terminal operations and cylinder manufacturing throughput. Companies that proactively address workforce planning, automation adoption, and process modernization are better positioned to sustain productivity even as broader sector labor conditions remain tight. On the materials side, the industry continues to navigate the balance between conventional steel-based containment infrastructure and newer composite technologies that offer production scale and design flexibility. Advances in automated manufacturing lines are expanding output capacity for certain vessel types, potentially reshaping cost curves and product availability over time.
These dynamics do not simply influence operating costs; they interact with strategic planning assumptions about capacity expansion, supplier selection, geographic prioritization, and risk hedging. A market study that treats these variables as peripheral noise misses the point. Our research embeds them directly into the analytical narrative so that strategic decisions are grounded in how the market actually behaves, not how it appears in simplified models.
Why This Research Matters for 2026 Decision-Making
As organizations finalize capital plans, evaluate partnership opportunities, and recalibrate supply chain strategies for the 2026-2032 period, the LPG market presents both meaningful opportunity and material complexity. Sustained top-line growth is supported by structural demand drivers, yet realized performance will vary sharply across segments, geographies, and operator profiles. Companies that rely on generic market narratives risk misallocating resources, underestimating regional nuances, or overlooking competitive threats that are already reshaping the landscape.
Our research is designed to close that gap. It provides the analytical depth needed to distinguish between headline growth and actionable opportunity, between apparent market strength and strategically relevant advantage. Decision-makers can use the report to refine investment theses, benchmark competitive exposure, identify segments where differentiation is achievable, and anticipate regulatory or logistics developments that may alter operational economics. By integrating historical performance, forward-looking projections, segment-level structural analysis, and current industry movements into a single cohesive framework, the study supports more confident and evidence-based strategy formulation.
Liquefied Petroleum Gas (LPG) Market
The LPG market is evolving at the intersection of energy transition, trade policy adaptation, logistics optimization, and technology modernization. Navigating that environment successfully requires more than awareness of aggregate growth figures. It requires clarity on where value is being created, which capabilities are becoming more or less valuable, and how external shocks and policy shifts will propagate through specific parts of the value chain. Our report delivers that clarity, giving enterprises the strategic intelligence they need to act decisively in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Liquefied Petroleum Gas (LPG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AES Resin Market to Hit $289M by 2032, Driven by 6% CAGR
By pmarketresearch, 2026-09-15
Navigating the AES Resin Market: Strategic Imperatives for 2026 and Beyond
The global landscape for Acrylonitrile Ethylene Styrene (AES) resin is undergoing a period of meaningful evolution. As manufacturers grapple with shifting feedstock costs, evolving end-use requirements, and intensifying regional demand patterns, the ability to make informed, forward-looking decisions has never been more critical. Our latest AES Resin Market research offers a comprehensive, data-driven examination of the industry, providing executives, procurement leaders, and strategic planners with the clarity needed to navigate both near-term volatility and long-term growth trajectories.
This report is not merely a retrospective compilation of figures. It is a strategic instrument designed to surface the underlying mechanics of market behavior, dissect competitive positioning, and illuminate the drivers that will shape industry outcomes from 2026 through 2032. By combining rigorous quantitative modeling with qualitative assessment of supply chain dynamics, technological developments, and application-specific demand shifts, the analysis equips decision-makers with actionable intelligence that can be immediately integrated into corporate planning cycles.
Market Trajectory and Structural Growth Dynamics
Over the past half-decade, the AES resin industry has demonstrated consistent expansion, reflecting steady adoption across multiple industrial and consumer sectors. Historical data indicates that the global market has grown from approximately 125 million USD in 2020 to an estimated 185 million USD by 2025, underscoring a resilient upward trend despite periodic supply chain disruptions and macroeconomic uncertainty. This growth has been supported by expanding production capacities, rising consumption in key application verticals, and sustained demand for weather-resistant and high-impact material grades.
Looking ahead, the forecast horizon extending to 2032 suggests continued momentum. The market is projected to reach 195.68 million USD in 2026, with steady year-over-year progression that culminates in an estimated 289 million USD by the end of the forecast window. This trajectory reflects a compound annual growth rate of 6.0 percent, a figure that signals sustained, albeit measured, expansion rather than speculative hype. For corporate planners, this level of predictability is invaluable: it enables more accurate capacity forecasting, informs investment timing, and provides a reliable baseline for scenario modeling.
The consistency of this growth path also highlights the structural attractiveness of AES resin as a material class. Its balance of impact resistance, weather durability, and processability makes it a preferred choice across diverse manufacturing contexts. As downstream industries continue to prioritize material performance and longevity, demand is expected to remain anchored by both replacement cycles and new product introductions, ensuring that the market retains a stable growth foundation.
Segmentation Intelligence: Type, Application, and Regional Architecture
Understanding where growth concentrates—and where it lags—is essential for allocating resources efficiently. The analysis segments the market across multiple dimensions, revealing how product types, end-use applications, and geographic regions interact to shape overall market behavior. While specific percentage splits and exact revenue allocations are detailed within the full report, the broader structural patterns are already evident and carry direct strategic implications.
MABS Resin Market
From a product-type perspective, the market encompasses general purpose, high impact, and weather-resistant AES resin grades. Each variant serves distinct performance requirements, and their relative demand profiles are influenced by downstream application needs, regional climate conditions, and manufacturing specifications. The balance between these categories affects pricing dynamics, production scheduling, and inventory strategies, making it critical for suppliers and buyers alike to understand how shifts in one segment ripple across the broader value chain.
Application-level demand further illustrates the material's versatility. Automotive, electronics, construction, and consumer goods sectors each contribute meaningfully to overall consumption, but their growth rates, formulation requirements, and procurement cycles differ substantially. For example, automotive-grade resins must meet stringent durability and regulatory standards, while construction applications prioritize weather resistance and long-term outdoor performance. Electronics and consumer goods, meanwhile, often emphasize process efficiency and aesthetic consistency. Recognizing these application-specific nuances allows manufacturers to tailor production portfolios and enables buyers to align specification decisions with total cost of ownership rather than unit price alone.
Geographically, the market exhibits pronounced regional variation. Asia Pacific represents a substantial share of global consumption, driven by robust industrial activity, expanding manufacturing bases, and growing infrastructure investment. Europe and North America also maintain significant demand, though their growth trajectories are shaped by distinct regulatory environments, raw material availability, and end-market maturity. Latin America and the Middle East and Africa regions present emerging opportunities, where evolving industrial capacity and shifting procurement patterns are gradually reshaping regional demand profiles. The full report provides detailed regional breakdowns, but even at this level, it is clear that geographic strategy must be tailored rather than standardized.
Competitive Landscape: Differentiated Capabilities and Market Concentration
The AES resin sector is characterized by a moderately concentrated competitive environment, with a small group of established manufacturers holding a meaningful share of total market revenue. The analysis indicates that the top three players account for approximately 55 percent of market value, while the top five collectively represent around 65 percent. This concentration level suggests that incumbents possess substantial production scale, technical expertise, and customer relationships, but it also leaves room for specialized players to compete on grade differentiation, regional service, and application-specific solutions.
Several key companies define the current competitive architecture. Techno-UMG Co., Ltd., based in Tokyo, specializes in AES resin of the ethylene propylene rubber type, with particular emphasis on weather-resistant grades designed for automotive and outdoor applications. Nagase America LLC, operating from New York, offers multiple AES terpolymer grades that deliver strong weather resistance for industrial and automotive use, positioning itself as a reliable supplier for performance-critical specifications. INEOS Styrolution Group GmbH, headquartered in Frankfurt, produces weather-resistant and high-performance AES resins under recognized brand portfolios, serving construction, automotive, and electronics markets with a focus on consistency and material reliability.
Nippon A&L Inc., also based in Tokyo, manufactures weather-resistant AES resin grades tailored for outdoor and construction applications, addressing the need for long-term durability in exposed environments. Kumho Petrochemical Co., Ltd., a large-scale producer in Seoul, maintains integrated capacity spanning general purpose and high-impact grades, enabling it to serve broad demand profiles with operational flexibility. JSR Corporation, another Tokyo-based supplier, provides AES resin for styrenic polymer alloys and specialty applications, supporting customers who require customized material behavior. Chi Mei Corporation, located in Tainan, Taiwan, stands as a leading producer with a focus on high-impact and general-purpose variants for automotive and consumer goods, reinforcing the region's importance as both a production hub and a demand center.
These companies illustrate the diverse strategic pathways within the market. Some compete on scale and integrated production, others on grade specialization and regional service, and still others on brand reputation and application-specific technical support. For buyers, this diversity creates options but also requires careful evaluation of supplier capabilities, quality consistency, and long-term reliability. For competitors, it underscores the importance of clear positioning, whether through cost leadership, product differentiation, or customer intimacy.
Raw Material Dynamics and Supply Chain Volatility
No analysis of the AES resin market would be complete without addressing the raw material environment that underpins production economics. Feedstock pricing, supply availability, and regional cost structures directly influence manufacturing margins, pricing strategies, and ultimately, market competitiveness. Recent industry observations highlight the dynamic nature of this environment and the need for proactive supply chain management.
Global acrylonitrile prices have shown notable movement, with increases of 3 to 5 percent across most regions during the first quarter of 2026, driven primarily by rising propylene feedstock costs. In the United States, the situation intensified further, with acrylonitrile prices surging by over 21 percent in late March 2026 as global inventories declined sharply and upstream feedstock availability tightened. These movements illustrate how quickly cost pressures can materialize and how regional factors can amplify or moderate price trends. In contrast, acrylonitrile pricing in India reached approximately 1038 USD per metric ton in September 2025, reflecting moderate growth supported by relatively steady supply chain conditions. This divergence across regions emphasizes that procurement strategies must be geographically informed rather than uniformly applied.
AES Resin Market
On the ethylene propylene rubber side, price trends have followed a different pattern. In Northeast Asia, EPDM rubber prices declined by 6.5 percent to around 2.88 USD per kilogram by May 2026, reflecting stable supply and moderate downstream demand. Meanwhile, in South America, EPDM rubber prices fell even more sharply, dropping 15.8 percent to approximately 2.93 USD per kilogram during the same period, as reduced industrial demand exerted downward pressure. These contrasting movements highlight the importance of monitoring regional feedstock markets in parallel, as cost advantages in one area can be offset by disadvantages in another, and as production location decisions increasingly depend on total input cost profiles rather than isolated commodity prices.
For manufacturers, these dynamics create both risk and opportunity. Effective hedging strategies, flexible sourcing arrangements, and proactive inventory management can mitigate exposure to sudden price swings. At the same time, companies that anticipate feedstock trends and align production planning accordingly can protect margins and maintain competitive pricing even in volatile periods. The report's detailed analysis of raw material dynamics provides the context needed to develop such strategies with confidence.
Report Architecture: How the Analysis Supports Execution
The AES Resin Market research is structured to translate complex industry data into practical decision support. It begins with a comprehensive market overview that establishes historical context, defines the scope of analysis, and outlines the methodological framework used to generate forecasts. From there, the report progresses into detailed segmentation analysis, examining type, application, and regional dimensions with sufficient granularity to support targeted strategic planning.
Competitive profiling forms another central pillar of the study. Each key company is evaluated not only on scale and product portfolio, but also on strategic positioning, regional presence, and likely response patterns to market shifts. This approach helps readers understand not just who the players are, but how they compete and where vulnerabilities or opportunities may emerge. The report also incorporates supply chain and raw material analysis, linking feedstock trends to production economics and pricing behavior, so that procurement and operations teams can align their strategies with realistic cost expectations.
Beyond descriptive analysis, the study includes forward-looking scenario considerations that account for potential variations in demand growth, raw material availability, regulatory developments, and technological adoption. These scenarios are designed to help organizations stress-test their assumptions and prepare for multiple plausible futures rather than betting on a single trajectory. The full report also provides structured data tables, trend visualizations, and interpretive commentary that together enable both high-level strategic discussion and detailed operational planning.
Strategic Takeaways for 2026 Decision-Making
As organizations finalize their 2026 plans, several strategic priorities emerge from the current market landscape. First, capacity and production planning should be aligned with the steady growth trajectory observed in the forecast period, while remaining flexible enough to accommodate regional demand fluctuations and application-specific shifts. Second, procurement strategies must account for the volatility inherent in raw material markets, particularly for acrylonitrile and related feedstocks, and should incorporate diversified sourcing where feasible. Third, competitive positioning should be sharpened through clear differentiation, whether by grade specialization, regional service capability, or application-focused technical support, since price competition alone is unlikely to sustain advantage in a moderately concentrated market.
Finally, cross-functional coordination between procurement, production, sales, and strategy teams will be essential. The interplay between feedstock costs, regional demand patterns, and product specification requirements means that siloed decision-making can easily lead to suboptimal outcomes. An integrated view, supported by the kind of comprehensive analysis provided in this report, enables organizations to anticipate changes, respond faster, and capture value that less prepared competitors may miss.
The AES resin market is not defined by sudden disruption, but by steady evolution, regional complexity, and the continuous refinement of material performance expectations. Organizations that invest in understanding these dynamics today will be better positioned to make confident decisions tomorrow. The complete market research report offers the depth, structure, and actionable detail needed to turn that understanding into strategy. We invite you to explore the full analysis and access the complete dataset, segmentation breakdowns, competitive profiles, and forward-looking scenarios that can inform your next strategic move.
For detailed analysis of this topic, please visit the official page: AES Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Box Server Market Hits $185M in 2025, Projected 7.25% CAGR to $301.6M by 2032
By pmarketresearch, 2026-09-15
Navigating the White Box Servers Market: Strategic Imperatives for 2026 and Beyond
The infrastructure landscape is undergoing a decisive shift. As enterprises grapple with escalating compute demands, energy constraints, and the imperative for hardware sovereignty, the white box server segment has transitioned from a niche alternative to a strategic cornerstone of modern data center architecture. At PW Consulting, our latest White Box Servers Market research study is engineered not merely to document this evolution, but to equip executives, procurement leaders, and technology strategists with the analytical rigor required to navigate a rapidly fragmenting competitive terrain. This overview outlines the scope, methodological depth, and actionable intelligence embedded within the full report, while positioning it as an indispensable decision-support instrument for the 2026 planning cycle.
Macro Trajectory and the Architecture of Growth
The historical record establishes a clear inflection point. From a baseline of 130.0 million USD in 2020, the market has compounded through a series of structural expansions, reaching 185.0 million USD in 2025. This trajectory is not coincidental; it reflects the systematic unbundling of proprietary hardware lock-ins, the maturation of open-compute specifications, and the financial calculus that increasingly favors modular, specification-driven procurement. Our forecast horizon extends through 2032, and the projected 2026 valuation anchors at 201.35 million USD, with compound annual growth sustaining at 7.25 percent across the entire forecast window. By the close of 2032, the market is positioned to approach 301.6 million USD.
These figures are not isolated snapshots. They are contextualized through a multi-year historical reconstruction spanning 2020 through 2025, followed by a disciplined forecast architecture that isolates demand drivers, pricing elasticity, and supply-chain velocity. Throughout the study, we intentionally refrain from fragmenting aggregate valuations into granular regional or application-level percentages within this narrative, preserving the analytical granularity for the dedicated matrices where cross-referenced variables can be properly contextualized. What executives should internalize is the velocity itself: a mid-single-digit CAGR amid a macroeconomic environment characterized by capital allocation caution signals that white box adoption is being driven by endogenous operational economics rather than speculative hype.
Report Architecture: From Specification to Strategy
The study is structured to serve multiple functional constituencies within the enterprise. Rather than presenting a monolithic narrative, the report is engineered as a modular intelligence system. Core sections include:
- Demand Decomposition and Use-Case Mapping : A systematic breakdown of workload characteristics that drive form-factor selection, power-consumption preferences, and deployment topology. The analysis correlates technical specifications with procurement behavior across enterprise, hyperscale, and telecom environments.
- Supply-Side Valorization : An examination of how original design manufacturers, component suppliers, and standards bodies interact to shape pricing architecture, lead times, and customization ceilings. The report maps the value chain from silicon reference designs through chassis integration and rack-level deployment.
- Competitive Positioning Framework : A multi-dimensional benchmarking methodology that evaluates incumbent and emerging players across customization capability, energy-efficiency engineering, compliance readiness, and geographic delivery maturity. Profiles are constructed to expose strategic adjacencies rather than superficial product listings.
- Regulatory and Infrastructure Overlay : A contextual layer that integrates energy-consumption realities, data-sovereignty mandates, and cooling-density constraints into deployment feasibility assessments. This section is particularly critical for organizations evaluating cross-border roll-outs or constrained facility footprints.
- Scenario Modeling and Sensitivity Analysis : Forward-looking constructs that test market responses to variable input conditions, including component cost volatility, energy-price fluctuations, and shifts in open-standard adoption velocity. Decision-makers can stress-test procurement timelines and capex phasing against plausible futures.
Each module is cross-linked to underlying datasets, allowing technical teams to trace an executive-level conclusion back to the specification sheet or procurement signal that generated it. This traceability is deliberate: it transforms the report from a passive reference document into an auditable strategic instrument.
Competitive Dynamics and the New Hardware Coalition
The white box server ecosystem is defined by a heterogeneous coalition of participants, each occupying distinct nodes within the value chain. The study profiles a carefully selected cohort of organizations whose strategic posture shapes procurement outcomes and architectural standards.
American-based integrators and silicon architects continue to anchor the customization frontier. Leading providers emphasize configurable architectures assembled from commercial off-the-shelf components, energy-conscious thermal design, and active participation in open-compute specification development. Their positioning reflects a dual mandate: deliver enterprise-grade reliability while preserving the agility that distinguishes white box procurement from proprietary alternatives. Concurrently, processor and reference-design architects supply the foundational instruction sets and validation blueprints that enable third-party integration at scale, often through structured partnerships that extend custom open-standard server programs into deployed environments.
Data Center White Box Servers Market
Across the Pacific, the dynamics shift toward scale, modularity, and regional deployment orchestration. Active manufacturers in East Asia have engineered modular chassis architectures optimized for cloud computing workloads and large-scale data center rollouts. Their operational footprint emphasizes repeatable integration pipelines and volume-responsive customization. Within this cohort, specialized subsidiaries have directed production expansion toward Southeast Asian data center markets, aligning hardware availability with regional demand clusters and localized service expectations. Taiwan-based entities further reinforce the supply architecture, with key ODM providers concentrating on high-performance, customizable hardware tailored to hyperscale and enterprise deployment profiles, while parallel manufacturing groups maintain active production and integration pipelines for global data center and telecommunications customers.
The ecosystem is not purely commercial. Open-compute foundations and standards consortia play a coordinating role, standardizing design parameters and specification frameworks through community-driven initiatives. Their influence extends beyond documentation; by establishing interoperable baselines, they reduce integration friction and expand the addressable surface for competitive procurement.
Recent collaboration signals reinforce this multi-actor architecture. In March 2025, a notable partnership announcement illustrated the convergence of silicon capability and open-architecture ambition, as major technology entities moved to develop custom white-box platforms leveraging advanced processor families for flexible, cost-effective open-standard deployments. Such developments are not isolated product launches; they signal a structural reorientation in which silicon vendors, integrators, and end-users co-design the specification boundary rather than accept it as a fixed constraint.
White Box Servers Market
Infrastructure Realities and Regulatory Pressure as Strategic Variables
Market growth cannot be decoupled from the physical and regulatory environment in which hardware operates. Energy economics now function as a first-order procurement variable. In 2023, U.S. data center annual energy consumption reached approximately 176 terawatt-hours, with servers alone accounting for roughly 40 percent of electricity consumption. Projections tied to AI-related model expansion anticipate energy demand doubling or tripling by 2028. This trajectory forces a recalibration of total cost of ownership models: efficiency is no longer a secondary specification, it is a financial necessity.
Enterprise adoption of white box servers is consequently reinforced by their energy-efficiency profile and the associated reduction in power bills through lower cooling requirements and decreased rack-level power density. Procurement decisions that once prioritized upfront unit cost are increasingly evaluated against operational expenditure over a five-to-seven-year lifecycle, with thermal design, power-supply architecture, and component selection serving as direct levers on long-term profitability.
Regulatory architecture adds a second pressure axis. Stringent data sovereignty requirements are accelerating localized deployment strategies, particularly in regions such as the Nordic countries where green data center mandates intersect with jurisdictional data-handling expectations. In these contexts, white box configurations offer a pragmatic pathway: organizations can tailor hardware sourcing, service delivery, and rack-level placement to satisfy both environmental targets and compliance mandates without surrendering architectural flexibility. The study maps these dynamics not as abstract policy commentary, but as deployment constraints that influence site selection, vendor qualification, and rollout sequencing.
Strategic Application for 2026 Decision-Making
The 2026 planning cycle demands more than directional market awareness. It requires procurement architectures that can absorb component volatility, deployment models that can satisfy both efficiency mandates and sovereignty constraints, and competitive intelligence that can distinguish between transient product positioning and durable strategic capability. The full report is designed to support these decisions across several operational domains:
- Capital Allocation and Phasing : Executives can align capex deployment with forecast windows, identifying where demand acceleration is most probable and where specification standardization is likely to compress procurement cycles.
- Vendor Qualification and Sourcing Strategy : Procurement teams can evaluate integrators, ODMs, and silicon partners against customization depth, energy-performance trade-offs, and regional delivery maturity, rather than relying on vendor-provided narrative alone.
- Infrastructure Road-Mapping : Facilities and operations leaders can incorporate power-consumption segmentation and thermal-density considerations into rack design, refresh timing, and cooling investment decisions.
- Competitive Positioning and Market Entry : Strategic teams evaluating adjacent expansions or new deployment geographies can use the concentration metrics and competitive profiling to identify where incumbency advantages are structural and where they are contingent on localized execution.
Market concentration remains moderately distributed, with the top three participants accounting for approximately 27.5 percent of aggregate positioning and the top five extending to roughly 34.2 percent. This dispersion signals that influence is not monopolized; it is contested through capability differentiation, integration velocity, and regional execution. For decision-makers, that dispersion is opportunity: it means that strategic partnerships, specification alignment, and procurement leverage can be engineered rather than passively inherited.
Accessing the Complete Intelligence Architecture
This overview is intentionally constructed as a strategic précis rather than a comprehensive disclosure. The aggregate trajectory, the competitive cohort, and the infrastructure and regulatory overlays presented here establish the analytical frame; the full report delivers the depth required to act on it. Within the complete study, decision-makers will find the detailed segmentation matrices, form-factor and power-consumption cross-references, application-driven demand breakdowns, and company-level capability assessments that translate macro trends into procurement-ready insight.
The white box server segment is no longer an experimental alternative. It is a structurally embedded component of how enterprises, cloud operators, and telecommunications providers will build, scale, and govern compute infrastructure through the remainder of the decade. The organizations that define their positioning earliest, against the most rigorous intelligence available, will capture the compounding advantages of specification agility, energy-efficient deployment, and regulatory readiness. PW Consulting's White Box Servers Market research is built to provide that intelligence with the precision, traceability, and strategic framing that 2026 decision-making demands.
For detailed analysis of this topic, please visit the official page: White Box Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cycle Computer Market Hits $215M in 2025, Projected 6.98% CAGR Through 2032
By pmarketresearch, 2026-09-15
Unlocking Growth in the Cycle Computer Market: A 2026 Strategic Roadmap
The global cycling industry is undergoing a profound technological transformation, driven by the convergence of wearable technology, advanced GPS navigation, and data analytics. For industry stakeholders, investors, and product strategists, understanding the trajectory of the Cycle Computer Market is no longer optional—it is a critical component of strategic planning. As we move through 2026, the landscape is defined by shifting consumer demands for real-time performance tracking, seamless ecosystem integration, and rugged durability. This article serves as a strategic overview of the current market environment, leveraging our latest comprehensive research to highlight the opportunities and challenges that define this sector.
Our recent market study provides a granular look at the forces shaping the industry between 2026 and 2032. By synthesizing historical performance with forward-looking projections, we offer a clear view of where capital and innovation are flowing. The following analysis outlines the macro-economic trends, competitive dynamics, and operational insights contained within the full report, designed to equip leadership teams with the intelligence needed to navigate the next seven years.
Cycle Computer Market
Market Trajectory and Economic Outlook
The financial architecture of the Cycle Computer Market demonstrates resilience and steady expansion, reflecting the broader adoption of connected fitness devices. Our analysis tracks revenue streams from 2020 through the forecast horizon ending in 2032, revealing a consistent upward trend that underscores the product category's maturity. In the base year of 2025, the market reached a valuation of 215.0 Million USD. This figure represents a significant culmination of growth from 163.15 Million USD recorded in 2020, highlighting a compound annual growth rate that signals healthy demand elasticity.
Looking ahead, the forecast period from 2026 to 2032 projects sustained momentum. We anticipate the market size to escalate from 231.5 Million USD in 2026 to approximately 344.8 Million USD by 2032. This trajectory suggests a CAGR of 6.98 percent, indicating that the sector is outperforming many traditional consumer electronics segments. This growth is not merely linear; it is fueled by incremental innovations in sensor technology, battery life, and connectivity protocols that enhance the user value proposition. For businesses operating in this space, these figures suggest that while the market is established, there remains substantial headroom for capture, particularly for players who can differentiate through software integration and niche performance features.
The transition from 2025 to 2026 marks a pivotal inflection point. As supply chains stabilize and consumer spending on high-quality sports equipment remains robust, the market is positioned to absorb new entrants and expanded product lines from incumbents. However, realizing this projected growth requires more than just manufacturing hardware; it demands a strategic understanding of how different product types and usage scenarios contribute to the overall revenue pool.
Product Segmentation and Application Nuances
Understanding the composition of the market is essential for targeted product development and marketing allocation. The Cycle Computer Market is not a monolith; it is divided into distinct categories based on material composition and end-use applications, each carrying different margin profiles and adoption rates.
Typology and Material Considerations
The market is primarily segmented by the type of technology and form factor employed. Our research indicates that certain segments dominate the revenue share due to their widespread compatibility with standard cycling setups, while others cater to specialized high-performance needs. The differentiation here is critical for supply chain management and R&D focus. Companies must decide whether to compete in high-volume segments or carve out niches in specialized categories where differentiation is higher. The balance between established film types and emerging variations defines the competitive ceiling for hardware manufacturers.
Application Diversity
On the application side, the usage scenarios for cycle computers extend beyond simple speed tracking. The primary demand driver is rooted in professional-grade manufacturing and rigorous testing environments, alongside consumer-facing recreational and competitive use. Our data highlights that specific application verticals command a larger share of the wallet, reflecting the intensity of usage in those sectors. For instance, segments related to high-precision manufacturing and specialized cycling applications show robust consumption patterns. Understanding which application drives the most volume allows vendors to tailor their feature sets, such as emphasizing power meter integration for competitive riders or mapping features for touring enthusiasts.
Bicycle Market
Strategically, the interplay between type and application suggests that bundling hardware with specific software capabilities could unlock higher value. The report details how these segments interact, providing a map for where product portfolios should be weighted to maximize return on investment.
Competitive Landscape and Strategic Positioning
The competitive environment in the Cycle Computer Market is characterized by a mix of specialized wearable technology firms, legacy cycling component manufacturers, and broad ecosystem players. Our analysis identifies key companies that are setting the pace for innovation and market share acquisition. The landscape is moderately fragmented, with a combined concentration ratio indicating that no single entity dominates completely, leaving room for agile competitors to gain ground through superior technology or strategic partnerships.
Key Market Players
Several firms stand out for their strategic focus on the Cycle Computer Market offering:
- Garmin Ltd. Based in Kansas City, USA, Garmin remains a dominant force with its Flagship Edge series GPS bike computers. Their strategy leverages a highly integrated sports ecosystem, ensuring user lock-in through data continuity across devices.
- Wahoo Fitness Operating out of Atlanta, USA, Wahoo focuses on high-performance units like the Element Bolt and Roam. Their value proposition centers on advanced mapping and navigation capabilities that appeal to cyclists seeking detailed route data.
- Polar Electro Oy From Oulu, Finland, Polar integrates GPS-enabled cycling computers with heart rate monitors and training tools. Their approach emphasizes the physiological aspect of cycling, targeting users focused on health metrics and training load.
- Lezyne Inc. Located in California, USA, Lezyne provides reliable GPS and cycling computer accessories specifically designed for road and mountain bikes, catering to durability and utility.
- COROS Wearables Based in Boulder, USA, COROS targets endurance athletes with their Dura and Explorer GPS bike computers, optimizing hardware for long-duration reliability and battery efficiency.
- Bryton Inc. Headquartered in Taiwan, Bryton offers GPS bike computers with mapping and navigation features suitable for road, gravel, and mountain use, positioning itself as a versatile global option.
- CatEye Co., Ltd. A Japanese manufacturer known for the AirGPS II and other GPS cyclocomputers, focusing on wireless compatibility and reliability in urban and recreational settings.
- Sigma-ELEKTRO GmbH Based in Germany, this company manages the VDO Cyclecomputing brand, offering bike computers and lighting systems that integrate safety with performance data.
- iGPSPORT A China-based contender providing BiNavi and BSC300T touchscreen GPS bike computers, increasingly aggressive in high-visibility racing partnerships.
- Magene Also based in China, Magene offers the C606 Pro GPS bike computers and power meter integrations, focusing on cost-performance value and ecosystem breadth.
- Stages Cycling, LLC A USA-based firm specializing in power-integrated cycle computers designed for top-level competitive cycling, leveraging direct power measurement technology.
- Trek Bicycle Corporation Based in Wisconsin, USA, Trek integrates GPS bike computers within their full bicycle and e-bike ecosystem, offering a seamless hardware-software bundle for OEM customers.
These companies are not merely selling hardware; they are competing for data ecosystems. The winner in this space will likely be the entity that best integrates hardware reliability with actionable data insights.
Recent Developments and Partnership Dynamics
The competitive field is dynamic, with recent moves signaling shifts in credibility and market access. Strategic partnerships, particularly within professional cycling, serve as powerful validation tools that influence consumer perception and brand equity.
In January 2026, Magene announced a significant partnership with the XDS Astana Team for the 2026 season. This deal involves the use of the C606 Pro cycle computer and the full Magene ecosystem. This move by a China-based manufacturer to secure a WorldTour partnership demonstrates the increasing competitiveness of emerging brands against established Western incumbents. It signals a shift in the perception of value and technology quality from Asian manufacturers, potentially disrupting premium pricing strategies held by legacy players.
Similarly, in November 2025, iGPSPORT signed with the Groupama-FDJ team for the 2026 season, supplying BiNavi, BSC300T, and accessories. Such endorsements are critical in the Cycle Computer Market because they provide real-world stress testing data and marketing visibility at the highest level of the sport. These developments indicate that the race for brand prestige is intensifying, and companies are willing to invest heavily in sponsorship to differentiate their hardware in a crowded market.
Strategic Implications for 2026 Decision Makers
The data and trends outlined in our full market research carry specific implications for strategic planning in 2026. First, the projected CAGR of 6.98 percent suggests that organic growth is available, but capturing it requires precision. Investors and executives should avoid broad-brush strategies and instead focus on the specific segments where margins are expanding. The divergence between product types and applications means that a generic strategy will likely yield suboptimal results.
Second, the competitive landscape suggests that ecosystem integration is becoming a moat. Companies like Garmin and Trek leverage broader ecosystems to retain users. New entrants or those looking to expand must consider how their hardware fits into a larger digital workflow. Partnerships, as seen with Magene and iGPSPORT, are not just marketing exercises; they are validations of technical reliability that can accelerate adoption in competitive segments.
Third, the regional dynamics hiding within the aggregate data suggest varying rates of adoption and preference. A one-size-fits-all distribution strategy is inefficient. Understanding where the volume is concentrated allows for optimized logistics and marketing spend.
Conclusion: The Value of Deep Intelligence
Navigating the Cycle Computer Market in 2026 requires more than surface-level observation. The difference between capturing the projected growth to 344.8 Million USD by 2032 and losing share lies in the details of segmentation, competitive moves, and application-specific demand. While this article provides a strategic overview, the full depth of our research offers the actionable intelligence required to make high-stakes decisions.
Our comprehensive report delves deeper into the specific revenue contributions of each segment, detailed regional analysis, and granular competitor profiling that are unavailable in this summary. For stakeholders ready to move from strategy to execution, accessing the complete dataset is the next logical step. We invite you to explore the full Cycle Computer Market research on our website to secure the detailed intelligence needed to lead in this evolving industry.
For detailed analysis of this topic, please visit the official page: Cycle Computer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Loading Dock Equipment Market Hits $215M in 2025, Forecasts 5.73% CAGR Through 2032
By pmarketresearch, 2026-09-15
The Strategic Imperative of Loading Dock Infrastructure: Navigating the 2026 Market Landscape
In the complex ecosystem of global supply chains, few components are as critical yet as frequently underestimated as the loading dock. These transitional zones serve as the primary interface between transportation networks and storage or production facilities. As we move through 2026, the loading dock equipment market stands at a pivotal juncture, influenced by evolving regulatory standards, technological integration, and shifting logistical demands. PW Consulting has released a comprehensive market study designed to equip industry leaders with the granular intelligence needed to navigate this changing environment. This article serves as an executive overview of that research, highlighting the strategic value embedded within the data without disclosing the full extent of the proprietary analysis available to subscribers.
Understanding the trajectory of this sector is not merely an academic exercise; it is a fundamental requirement for capital allocation, capacity planning, and competitive positioning. The following insights draw from our latest forecast models, offering a glimpse into the market forces that will define operational efficiency over the next half-decade and beyond.
Market Trajectory and Economic Scope
The loading dock equipment market has demonstrated consistent resilience and growth over the past half-decade. According to our analysis, the market revenue in the base year of 2025 reached 215.0 million USD. This figure represents a steady accumulation of value from a 2020 baseline of 163.15 million USD. The historical compound annual growth rate reflects a maturing industry that is expanding in lockstep with broader logistics and warehousing sectors.
Looking forward, the forecast period spanning 2026 to 2032 projects a continued upward trend. We anticipate the market valuation to reach 223.71 million USD in 2026, eventually scaling to 344.8 million USD by 2032. This projection corresponds to a forecast CAGR of 5.73 percent. Such growth is not accidental; it is driven by the replacement cycle of aging infrastructure, the expansion of e-commerce fulfillment centers, and stricter safety compliance requirements that mandate upgraded equipment.
For strategic planners, these numbers provide a macro-level validation of investment in dock infrastructure. However, top-line figures only tell a portion of the story. The real value lies in understanding the velocity of capital expenditure across different facility types and the specific drivers that will accelerate adoption in certain regions versus others. Our detailed report deconstructs these trends to help stakeholders identify where growth is most sustainable.
Segmentation Dynamics and Operational Focus
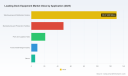
A critical component of our study involves breaking down the market by equipment type and application. The data suggests a diverse landscape where hydraulic solutions continue to hold significant weight due to their reliability and load-bearing capabilities. Mechanical and air-powered options cater to specific niche requirements where power availability or maintenance constraints differ. The breadth of product offerings available in the market indicates that there is no one-size-fits-all solution for loading dock management.
Similarly, the application spectrum is varied. Warehousing and distribution centers represent a substantial portion of demand, reflecting the surge in last-mile delivery requirements. Manufacturing and production facilities also contribute significantly, as integrated logistics become part of the production line efficiency. Ports and logistics hubs, along with the food and beverage industry, present specialized use cases that require equipment capable of withstanding harsher environmental conditions or maintaining strict hygiene standards.
While specific percentage splits are detailed in the full report, it is important for decision-makers to recognize that reliance on a single equipment type or application focus can introduce vulnerability. Diversification in dock infrastructure portfolios allows companies to adapt to fluctuating throughput volumes. The research highlights how different segments correlate with industry-specific risk factors, enabling procurement teams to align their specifications with long-term operational goals.
Geographic Distribution and Regional Opportunities
Geography plays a decisive role in market utilization and growth potential. North America remains a mature market with high adoption rates of advanced dock equipment, driven by stringent safety norms and a dense network of distribution centers. Europe follows as a significant contributor, with growth influenced by cross-border logistics integration and regulatory harmonization.
Asia Pacific presents a dynamic opportunity space, characterized by rapid infrastructure development and the expansion of manufacturing bases. Latin America and the Mideast and Africa regions, while currently smaller in terms of revenue share, offer emerging potential as trade corridors develop and modernization initiatives take hold. Our analysis provides a nuanced view of these regions, accounting for local economic conditions and logistical maturity.
Dock Levelers Market
Strategists must avoid the temptation to apply a uniform strategy across all geographies. The rate of infrastructure investment, labor costs, and regulatory timelines vary significantly. The full market study includes a deeper dive into regional absorption rates and the competitive intensity within each geographic zone, allowing companies to prioritize market entry or expansion efforts where the return on investment is most favorable.
Competitive Landscape and Key Players
The loading dock equipment sector is populated by a mix of established manufacturers and specialized providers. Prominent companies such as Systems, LLC, McGuire, Poweramp, DLM, Kelley, Rite-Hite, and Serco form a core group of industry participants based primarily in the United States. These firms compete on various fronts including product durability, innovation in safety features, and service network reach.
International presence is also notable, with companies like Pentalift Equipment Corporation and Blue Giant Equipment Corporation from Canada, alongside major players like Overhead Door and Wayne Dalton, who bring broader door and dock solutions to the table. Other significant contributors include Rotary Products Inc., Advance Lifts, Copperloy, Alapont Logistics USA, and DH Pace. Together, these entities create a competitive environment that drives innovation while maintaining supply reliability.
Market concentration data indicates a moderately fragmented landscape, with a CR3 of approximately 32.5 percent and a CR5 of roughly 44.2 percent. This suggests that while there are dominant players, there is still substantial room for mid-sized companies to capture niche markets or regional dominance through specialized service offerings or technological differentiation. Understanding the specific offerings and capacity of these competitors is essential for positioning new products or negotiating supply contracts.
Regulatory Pressures and Safety Compliance
One of the most potent drivers of market growth is the regulatory environment. Safety standards are becoming increasingly rigorous, compelling facility managers to upgrade equipment that may have previously been considered compliant but is now outdated relative to new interpretations of safety codes. A key example is the requirement under OSHA 29 CFR 1910.23, which mandates guarding for open-sided dock areas 4 feet or more above adjacent floor or ground level where there is a danger of employee falling.
Compliance with such regulations is not optional. It necessitates investment in dock levelers, guardrails, and vehicle restraints that meet specific safety thresholds. Failure to comply can result in significant fines and operational shutdowns, making regulatory adherence a primary budget justification for equipment upgrades. Our report analyzes how these regulatory shifts impact capital expenditure cycles and which equipment categories see the highest demand spikes following regulatory updates.
Furthermore, beyond OSHA, local building codes and insurance requirements often impose additional layers of compliance. Companies operating multi-site facilities must ensure consistency across their portfolio to manage risk effectively. The intersection of regulation and equipment specifications is a complex area that our study examines in detail, providing checklists and compliance roadmaps for safety officers and operations managers.
Report Methodology and Practical Utility
PW Consulting's Loading Dock Equipment Market report is constructed using a multi-source methodology that combines primary interviews with industry experts and secondary data analysis. The aim is to provide actionable intelligence rather than abstract projections. The document is structured to support various internal functions, from procurement and engineering to strategic planning and investor relations.
Readers of the full report will find detailed profiles of the key companies mentioned earlier, including their specific offerings within the loading dock equipment space. This competitive profiling helps in benchmarking internal capabilities against market leaders. Additionally, the report covers recent developments and technological shifts that are reshaping the product landscape, such as automation integration and IoT-enabled safety systems.
The segmentation analysis provided in the document allows users to isolate the specific application or product type most relevant to their business case. Whether a company is focused on expanding a warehousing network or upgrading manufacturing dock entries, the data enables scenario planning. By removing the noise of aggregate market data, the report zeroes in on the specific growth vectors that align with particular business models.
Strategic Recommendations for 2026 Decision Makers
Based on the preliminary findings of our study, several strategic priorities emerge for stakeholders operating in 2026. First, investment in safety-compliant equipment should be viewed through the lens of risk mitigation rather than just operational cost. Upgrading to meet current standards protects against liability and enhances workforce safety, which in turn improves productivity.
Second, supply chain resilience requires flexibility in dock operations. Companies should consider equipment options that allow for rapid adjustment to varying trailer sizes or throughput volumes. The data suggests that facilities with versatile docking solutions recover faster from logistical disruptions than those with rigid infrastructure.
Third, geographic strategy should be informed by local regulatory timelines and infrastructure maturity. Businesses with global footprints can leverage insights on regional growth rates to align their expansion plans with markets where dock infrastructure investment is peaking. This avoids overinvestment in saturated areas while capturing early-mover advantages in developing regions.
Finally, competitive intelligence should be continuous. The landscape involving players like Rite-Hite, Kelley, and Blue Giant is dynamic. Understanding their product roadmaps and capacity expansions can inform partnership opportunities or help identify gaps in the market that a company can fill. Our report provides the foundational data to build this ongoing intelligence capability.
Accessing Comprehensive Intelligence
The insights presented here represent a high-level summary of the strategic themes identified in our latest research. While the market trajectory, key players, and regulatory drivers provide a useful context, the full depth of the analysis is contained within the complete report. Specific segmentation values, detailed regional forecasts, and granular competitor assessments are essential for building precise business cases and investment models.
We invite industry leaders, procurement directors, and strategic planners to access the full Loading Dock Equipment Market study on the PW Consulting web platform. The complete document offers the proprietary data and nuanced analysis required to make informed decisions that will sustain operational excellence through 2032 and beyond. In a market driven by both growth and compliance, having the right data is the most valuable asset a company can possess.
Loading Dock Equipment Market
For detailed analysis of this topic, please visit the official page: Loading Dock Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rotary Kiln Market at USD 718.57M in 2025, Projected 3.1% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Rotary Kiln Market: Strategic Intelligence for the 2026–2032 Horizon
The global rotary kiln industry stands at a critical inflection point. As we move through 2026, capital allocation decisions, capacity expansions, and technology roadmaps must be anchored in rigorous, forward-looking intelligence rather than historical extrapolation. PW Consulting’s latest Rotary Kiln Market research delivers precisely that strategic compass, synthesizing a decade of historical performance with a carefully modeled forecast window to equip executives, investors, and engineering leaders with actionable market clarity.
This report is not a static snapshot. It is a decision-support instrument engineered for the realities of mid-decade capital cycles, supply chain reconfiguration, and the accelerating push toward decarbonized thermal processing. Below, we outline the analytical architecture, the structural forces shaping the market trajectory, and the competitive dynamics that will separate resilient operators from marginal participants over the remainder of the decade.
Market Trajectory and the Strategic Imperative for 2026 Decision-Makers
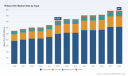
The rotary kiln market has demonstrated consistent expansion through the 2020–2025 historical window, recovering from early-pandemic disruptions and capitalizing on sustained demand across core industrial processing sectors. By the close of 2025, the market crossed a significant threshold, with evaluated revenue reaching $718.57 million. That momentum carries into the forecast period, positioning 2026 as a foundational year where early-cycle investments in automation readiness, emission compliance tooling, and next-generation kiln configurations will compound into measurable competitive advantages.
Our modeling points to a five-year compound annual growth rate of approximately 3.1 percent across the forecast horizon. While that headline figure suggests measured, steady progression, the underlying trajectory is anything but uniform. Growth will be spatially uneven, technologically selective, and heavily influenced by raw material cost volatility, energy transition pacing, and the pace at which heavy industrial operators integrate digital process optimization into existing assets.
Strategic decision-makers must recognize that the mid-period forecast years contain meaningful inflection moments. Operators who understand where capacity additions will concentrate, which kiln configurations will command premium pricing, and how regional demand cycles align with local regulatory timelines will be positioned to capture disproportionate value. Those who rely on legacy procurement assumptions or unvalidated regional intuition will face margin compression, compliance friction, and stranded asset risk.
This is where comprehensive intelligence becomes indispensable. Understanding the interplay between shipment volumes, equipment lifecycle timing, and the pace of retrofit activity across installed base fleets requires structured, granular data that unpicks headline growth into operational signals. The differences between a kiln procurement decision delayed by six months versus one synchronized with regional regulatory deadlines or raw material pricing troughs can meaningfully alter project economics and return timelines.
Structural Fault Lines: Type, Application, and Regional Divergence
The rotary kiln ecosystem is inherently segmented by function, end-use processing requirements, and regional industrial maturity. At the equipment level, distinct kiln types serve fundamentally different thermal processing objectives, each with its own demand elasticity, capital intensity profile, and aftermarket service requirements. The dominance of established processing lines ensures that a substantial share of market value continues to flow through capital and maintenance cycles tied to large-scale cement and lime operations. Meanwhile, specialized configurations for metallurgy and other niche applications present differentiated entry barriers, customization demands, and service economics.
Worldwide Rotary Separator Market
By application, thermal processing demand is anchored by core industrial use cases that dictate throughput requirements, heat transfer design tolerances, and refractory lifecycle expectations. Cement production remains the gravitational center of the market, supported by ongoing upgrades to improve thermal efficiency and reduce specific fuel consumption. Metallurgical processing and chemical manufacturing applications contribute meaningful demand with distinct operating specifications, often requiring tighter control over residence time, atmosphere, and material throughput consistency. Emerging and auxiliary applications round out the demand profile, frequently serving specialized engineering, agricultural amendment, or waste processing needs where kiln performance intersects with material science requirements.
Geographically, the market reflects pronounced divergence. Asia Pacific continues to represent the largest demand footprint, driven by sustained industrial construction activity, grinding and pyro-processing capacity investments, and expanding mineral processing infrastructure. North America maintains a substantial position supported by mature cement, chemical, and waste-processing value chains alongside a strong aftermarket and retrofit services segment. Europe’s market profile is shaped less by volume expansion and more by compliance-driven upgrades, fuel-switching initiatives, and advanced filtration integration aimed at meeting increasingly stringent emissions thresholds. Latin America and the Middle East & Africa contribute more modest demand volumes but are characterized by project-stage volatility, selective large-scale capital deployments, and regional policy shifts that can accelerate or delay procurement cycles.
Rotary Kiln Market
Understanding these structural fault lines is essential because regional and application-level patterns do not move in lockstep. Procurement timing, specification requirements, local content expectations, and service ecosystem maturity vary considerably. A product strategy that works in one geography or application vertical often underperforms when exported without recalibration to local operating conditions, regulatory frameworks, and labor cost structures.
Technology Integration and Operational Dynamics Reshaping the Value Chain
The operational narrative of the rotary kiln market is being rewritten by three converging forces: raw material supply dynamics, digital process optimization, and regulatory tightening. Each force alters the economics of kiln ownership, the structure of service contracts, and the competitive positioning of equipment manufacturers and operating fleets.
Steel remains the essential raw material for rotary kiln construction shells, and its price instability creates direct sensitivity across total production costs. For equipment suppliers, this means that quoting frameworks, lead-time estimation, and contract structuring must account for material cost volatility rather than assuming stable bill-of-materials pricing. For operators, it reinforces the value of lifecycle service agreements, refractory management programs, and predictive maintenance capabilities that reduce unplanned downtime when procurement conditions tighten.
Digitalization is equally transformative. The integration of AI-based process optimization and IoT-enabled monitoring in cement and minerals plants has demonstrated measurable operational impact, reducing labor requirements for kiln operations while improving fuel efficiency by an estimated 10 to 15 percent. This is not merely a cost-reduction story. It reshapes asset utilization models, enables remote diagnostics, and shifts the competitive frontier from mechanical reliability alone to integrated operational intelligence. Operators that decouple throughput improvement from linear labor expansion gain a structural margin advantage, while manufacturers that embed monitoring, control logic, and performance analytics into their equipment offerings increasingly win on lifecycle value rather than installed cost alone.
Regulatory pressure adds another layer of strategic complexity. Stringent emission regulations in Europe require advanced filtration, optimized combustion, and fuel switching in rotary kilns to meet CO2, NOx, and particulate controls. Compliance is no longer an optional engineering add-on; it is increasingly a precondition for continued operation in high-scrutiny jurisdictions. At the same time, standardization efforts are expanding the material applications of rotary kiln-produced outputs. The ASTM D5883 standard provides guidance for using rotary kiln-produced expanded shale, clay, or slate as a mineral amendment in topsoil, while ASTM D8249 specifies material characteristics, physical requirements, and sampling for rotary kiln-produced porous aggregates. These standards validate new market applications, creating incremental demand pathways that intersect directly with kiln design choices and operational flexibility.
Together, these dynamics create a market environment where procurement, operations, and compliance cannot be managed in isolation. Engineering teams must plan for multi-variable operating envelopes. Procurement leaders must negotiate around material volatility and lead-time risk. Plant managers must assess retrofit versus replacement paths with regard to both emissions compliance and digital readiness. Strategic intelligence that integrates these dimensions gives executives the ability to prioritize investments where they yield compounding operational and regulatory returns.
Competitive Architecture: Scale, Specialization, and Strategic Posture
The competitive landscape of the rotary kiln market is defined by a blend of global equipment majors, engineering specialists, regional manufacturing leaders, and application-focused technology firms. Market concentration metrics underscore a moderately consolidated environment, with CR3 and CR5 levels reflecting the influence of a handful of large, internationally active players alongside a broad base of regional and custom-solution providers.
FLSmidth stands out as a global leader in cement and minerals equipment, with more than 500 installed or upgraded kiln lines worldwide. Its profile reflects a scale-driven, project-integrated approach that spans engineering, delivery, and long-cycle service support. Recent activity illustrates how the company is expanding the technical frontier of its offerings: in May 2025, FLSmidth delivered a cutting-edge 115-meter rotary kiln to Sibanye-Stillwater’s Keliber lithium refinery, signaling the market’s growing relevance beyond traditional cement and minerals applications and the increasing demand for large-format, process-specific kiln systems.
KHD Humboldt Wedag brings deep German engineering specialization in cement industry rotary kiln systems, positioning itself around process reliability, design heritage, and integration expertise for core pyro-processing applications. thyssenkrupp Polysius operates in a similar strategic lane with integrated pyro-processing rotary kiln systems, emphasizing tightly coupled equipment architectures that align thermal processing, preheater logic, and downstream material handling. Both firms compete on engineering depth, system-level optimization, and the ability to deliver kiln solutions that reduce downstream inefficiencies rather than just hardware specifications.
On the North American side, FEECO International operates as a custom rotary kiln manufacturer with strong capabilities in pilot-scale testing and batch or pilot facilities. This positions the company to serve clients that require flexible development pathways, material-specific process validation, and customized thermal processing solutions before full-scale deployment. HiTemp Tech Corporation complements the landscape with factory-built rotary kiln incineration systems for solid waste at throughput ranges from 12 to 100 tons per day, representing a distinctly application-oriented segment where regulatory compliance, emissions control, and compact thermal processing design are central competitive factors.
Chinese manufacturers represent a substantial and rapidly evolving competitive presence. CITIC Heavy Industries has manufactured more than 1,000 rotary kilns, including cement, lime, and pellet types for global markets, reflecting large-scale production capacity and broad application coverage. AGICO Cement Machinery is a leading supplier of cement rotary kilns, lime kilns, and shaft kilns with factory-direct solutions, and its recent project activity underscores the pace of operating-asset modernization in the sector. In September 2025, AGICO completed a rotary kiln revamp project for a 5,000 t/d cement production line with a double five-stage preheater and TTF decomposition furnace, a clear example of how retrofit and upgrade activity is becoming a strategic battleground for both OEMs and aftermarket service providers.
Jiangsu Pengfei Group rounds out the competitive field as a custom rotary kiln supplier for cement plants and wet-pulp caustic processes. Its recent engagement highlights cross-application demand linkages: in March 2025, Jiangsu Pengfei secured an order for two wet-pulp caustic rotary kilns with Valmet Europe, demonstrating how kiln technology is embedded into broader process chains and how international partnerships shape deployment pathways.
Taken together, the competitive architecture reveals three strategic archetypes. First, global integrators that compete on scale, installed base, and system-level engineering. Second, specialists and application-focused manufacturers that compete on customization, pilot validation, and niche compliance demands. Third, large-volume producers that compete on manufacturing capacity, broad product scope, and aggressive project execution. The strategic takeaway is that positioning in this market does not map cleanly to a single competitive axis. Pricing, service, customization, compliance capability, and delivery reliability each carry weight depending on geography, application, and project stage.
What This Market Study Delivers for Executive Decision-Making
This study is structured to convert market complexity into decision readiness. It combines historical reconstruction with forward modeling, competitive profiling with application-specific demand analysis, and regulatory and operational context with practical strategic framing. The analysis is designed for multiple audiences within an enterprise: strategy and corporate development teams assessing portfolio and geographic direction, engineering leaders evaluating equipment and retrofit pathways, procurement leaders aligning sourcing with material cost and lead-time risk, and investors or lenders requiring structured visibility into demand durability and competitive positioning.
Report content is built around operational utility. It maps the demand architecture across kiln type and application so that teams can identify where volume concentration and specification complexity create different procurement, service, and pricing dynamics. It evaluates regional market profiles in a way that respects local regulatory timelines, industrial maturity, and project-stage volatility rather than treating geography as a simple share table. It embeds competitive intelligence around the companies shaping the market today, including their technological focus, delivery posture, and recent developments that signal where capability and demand are converging.
Equally important, the study integrates the external forces that alter the battlefield. Raw material cost exposure, digital process optimization, emissions compliance requirements, and standards-driven material applications are not treated as background noise. They are analyzed as demand modifiers and operational constraints that affect payback calculations, service contract design, retrofit prioritization, and competitive differentiation. Recent 2025 developments are incorporated to illustrate how large-format equipment, cross-border partnerships, and retrofit modernization are actively reshaping the market rhythm.
The output is intended to support concrete decisions: which segments warrant focused commercial attention, where retrofit opportunity intersects with compliance deadlines, how regional demand cycles should inform capacity and partnership strategy, and which competitive differentiators are likely to matter most as digitalization and emissions requirements become normalized operating expectations.
The Strategic Case for Deeper Intelligence in 2026
The rotary kiln market of 2026 is not a single trajectory. It is a set of overlapping demand cycles, compliance-driven upgrade paths, digital readiness imperatives, and regionally distinct procurement rhythms. Executives who attempt to navigate these layers with high-level summaries or purely historical assumptions will miss where value is actually created and where exposure accumulates.
PW Consulting’s Rotary Kiln Market research is designed to close that gap. By combining modeled market progression with structural segment analysis, competitive profiling, and operational context, it provides a foundation for capital planning, product and service strategy, and operational investment prioritization. The full report goes further, offering the detailed segmentation intelligence, regional demand narratives, competitive benchmarking granularity, and application-specific dynamics that executives need to translate market direction into committed action.
For organizations preparing to allocate capital, renew equipment lifecycles, expand processing capacity, or reposition service offerings through 2026 and beyond, the difference between assumption and evidence is material. Deeper market intelligence enables sharper segmentation choices, better-timed procurement decisions, and more resilient competitive positioning as the market moves through the forecast period.
For detailed analysis of this topic, please visit the official page: Rotary Kiln Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cotton Yarn Market to Hit $117.79 Billion by 2032, Growing at 3.97% CAGR
By pmarketresearch, 2026-09-15
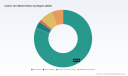
Navigating the Cotton Yarn Market: Strategic Intelligence for 2026 Decision-Making
The global cotton yarn industry stands at a critical inflection point as we move through the mid-2020s. Shifting trade architectures, volatile raw material pricing, and aggressive capacity adjustments by key producers are redefining competitive dynamics across apparel, home textiles, and technical fabric supply chains. For executives responsible for sourcing strategy, margin optimization, and geographic expansion, relying on fragmented market signals is no longer sufficient. The Cotton Yarn Market Research report from PW Consulting delivers a rigorous, data-grounded lens into the forces shaping the sector, with a forecast horizon that extends through 2032.
This article provides a strategic preview of the study's core findings and analytical framework. It is designed to demonstrate why this intelligence matters for enterprise planning in 2026, while preserving the detailed breakdowns that justify a full review of the complete document.
A Trajectory of Measured Expansion
Over the past five years, the cotton yarn market has demonstrated resilient growth against a backdrop of supply chain disruptions and evolving consumer demand. Historical valuations show the market expanding from approximately $62.01 billion in 2020 to $89.54 billion by 2025, reflecting a compound trajectory fueled by sustained textile consumption and industrial spin capacity additions. Looking ahead, the forecast period through 2032 projects the market reaching $117.79 billion, underpinned by a steady CAGR of 3.97 percent.
These figures tell a story of incremental but consistent growth rather than hyper-expansion. For strategic planners, this trajectory signals a market where share capture, operational efficiency, and vertical integration matter more than chasing volume for its own sake. The mid-single-digit growth rate suggests that value will increasingly accrue to participants who can navigate input cost volatility, optimize blend formulations, and align production with demand pockets in high-growth geographies.
Where Value Concentrates: Yarn Types and End-Use Applications
The market's internal architecture reveals clear patterns in how revenue is distributed across product categories and final applications. Carded yarn commands the largest share of the type segmentation, followed by combed yarn, with a smaller remainder allocated to specialty and other variants. This distribution reflects the enduring demand for cost-effective, versatile yarns in mass-market garment manufacturing, while combed variants retain premium positioning for higher-count and finer textile applications.
On the application side, apparel remains the dominant end-use driver, absorbing more than half of total market value. Broader textile applications, including home textiles and industrial fabrics, represent the next significant demand pool. These structural allocations matter for procurement and product development teams because they illuminate where pricing pressure is most intense, where custom specifications command premiums, and where forward purchasing contracts can lock in favorable input costs. The full report unpacks these splits with granular segmentation that connects each category to regional production footprints and demand cycles, but the headline takeaway is clear: apparel-led consumption continues to anchor the market, while textile diversification offers incremental growth opportunities.
Geographic Concentration and the Asia-Pacific Anchor
Regional dynamics in the cotton yarn market are heavily shaped by production clustering and trade flow patterns. Asia Pacific dominates the regional revenue landscape, reflecting the concentration of spinning infrastructure, deep-integrated textile ecosystems, and proximity to major apparel manufacturing hubs. Other regions, including North America, Europe, Latin America, and the Middle East and Africa, collectively account for a smaller but strategically significant portion of market value, each influenced by distinct regulatory frameworks, import dependencies, and local manufacturing competitiveness.
For sourcing managers and market entry strategists, the geographic breakdown is not merely a revenue map. It is a lens into trade policy exposure, logistics cost structures, and the relative bargaining power of regional suppliers. The complete analysis maps these dynamics against tariff regimes, local incentive programs, and shifting buyer preferences, providing the kind of regional intelligence that supports scenario planning rather than static sourcing assumptions.
Competitive Intensity and the CR5 Reality
Market concentration data underscores a landscape that is fragmented at the base but meaningfully consolidated among top-tier players. The top three competitors hold approximately 32.5 percent of total market revenue, while the top five expand that share to 42.0 percent. This structure indicates that a handful of large, integrated producers exert disproportionate influence over pricing benchmarks, capacity cycles, and export flow patterns, even as a broad base of regional manufacturers competes on cost, specialization, and localized service.
The competitive set spans well-established names across India, China, Vietnam, and Pakistan, each pursuing distinct strategic postures. In India, major players such as Vardhman Textiles Ltd., Nahar Spinning Mills Limited, Ambika Cotton Mills Limited, Sutlej Textiles and Industries Limited, KPR Mill Limited, Arvind Limited, and Grasim Industries Ltd. continue to anchor domestic spinning capacity and export supply. Fiotex Cotspin Pvt. Ltd. has drawn particular attention in 2026 for ramping production and achieving full capacity utilization while booking export orders up 40 percent through June, largely driven by demand from China. Across the broader competitive field, manufacturers are balancing volume growth with product differentiation, particularly in compact, Siro-spun, core-spun, and blended yarns that appeal to value-added textile programs.
In Vietnam, producers such as HengBang Textile Vietnam Co., Ltd. and BLUETEX VIETNAM are active in 100 percent cotton and polyester-cotton blends, supporting the country's export-oriented textile expansion. In China, large-scale operators including Weiqiao Textile Company Limited and several Shandong-based manufacturers like Weifang Jinyi Yarn Co., Ltd., Shandong Henghua Textile Co., Ltd., and Shandong Hongyan Textile Co., Ltd. maintain significant pure cotton yarn output, often leveraging automated lines to improve consistency and throughput. Nishat Mills Limited in Pakistan rounds out the competitive picture as an active regional producer navigating its own input and trade dynamics.
The strategic implication is that competitive benchmarking cannot be reduced to a single market share number. Instead, it requires understanding how each major player positions itself across count ranges, blend types, quality tiers, and destination markets. The report's competitive analysis goes beyond company snapshots to examine capacity trajectories, product Launches, and the ways in which recent operational milestones may shift regional bargaining power.
Regulation, Tariffs, and the New Cost Calculus
One of the most consequential layers of 2026 planning is the evolving regulatory and cost environment. Trade policy and input pricing are no longer peripheral concerns; they are central variables in supply chain modeling. Recent developments illustrate how quickly the operating context can change. In Vietnam, cotton yarn classified under HS codes 5204, 5205, and 5207 faces a 5 percent tariff alongside an 8 percent value-added tax, shaping the cost competitiveness of Vietnamese exports in certain destination markets.
In the United States, the Buying American Act of 2025 introduces a $0.85 per pound tariff on U.S. cotton fiber exported to non-FTA countries, while U.S.-manufactured cotton yarn is subject to a $0.15 per pound tariff. These asymmetric levies influence where sourcing teams prioritize domestic versus imported inputs and how yarn exporters evaluate destination-country incentives. Meanwhile, India's RoDTEP scheme for cotton yarn exports was reduced from 3.4 percent FOB to 1.7 percent effective February 2026, compressing a previously meaningful export incentive and prompting producers to reassess price positioning in competitive overseas markets.
Raw material pricing adds another layer of volatility. In April 2026, the Producer Price Index for raw cotton rose to 118.299 from 101.319 in December 2025, while the spun cotton yarn PPI stood at 149.159, down from 153.620 in January 2026. This divergence between upstream cotton costs and downstream yarn pricing highlights the margin sensitivity of spinners and the importance of forward hedging, blend optimization, and contract structuring. In India, cotton prices climbed to a four-year high of ₹300 per kg in May 2026, driven by strong demand from China and Bangladesh, which in turn pushed yarn prices toward the same ₹300 per kg threshold. These movements reinforce the need for market intelligence that connects commodity indices to commercial decision points rather than treating them as abstract economic indicators.
What the Full Report Delivers
The Cotton Yarn Market Research study is built to support practical, forward-looking decisions rather than simply summarizing market size. It integrates historical performance analysis, forecast modeling through 2032, segmentation-by-type and application, regional evaluation, competitive benchmarking, and regulatory context into a cohesive intelligence framework. For executives, this means the report can be used to:
- Evaluate long-term demand trajectories for different yarn categories and end-use segments
- Assess where production capacity additions are likely to alter supply balances and pricing leverage
- Understand the impact of tariff structures, export incentive changes, and value-added tax regimes on sourcing cost models
- Compare major competitors' strategic moves, including capacity expansion, product launches, and export order momentum
- Align procurement and inventory planning with commodity price signals and PPI trends
- Identify regional market opportunities and risks through a structured lens rather than anecdotal market chatter
Each section is designed to feed directly into commercial planning, whether that involves renegotiating supplier contracts, prioritizing investment in certain yarn grades, evaluating entry into new export corridors, or stress-testing margin assumptions under different input-cost scenarios.
Why 2026 Decision-Makers Need This Intelligence Now
The mid-2020s are defining a more complex operating environment for cotton yarn stakeholders. Growth is steady but not explosive, competition is intensifying among both integrated giants and specialized regional producers, and policy-driven cost shifts can quickly reorder sourcing economics. In this setting, the difference between reactive and proactive strategy often comes down to the quality of market intelligence available at the point of decision-making.
Cotton Yarn Market
A market expanding toward $117.79 billion by 2032 at a 3.97 percent CAGR may appear straightforward at the aggregate level. Yet the real strategic question is not whether the market is growing, but who will capture value within that growth and under what cost, regulatory, and competitive conditions. The answers depend on segmentation detail, regional nuance, and a clear-eyed view of how leading producers are repositioning themselves.
The complete Cotton Yarn Market Research report from PW Consulting is structured to provide that level of clarity. It offers the analytical depth required to move beyond high-level trends and into the operational and commercial specifics that guide investment, sourcing, and competitive positioning decisions. For teams preparing for the remainder of 2026 and beyond, this is the kind of intelligence that converts uncertainty into a structured basis for action.
To access the full segmentation analysis, regional breakouts, competitive profiles, and forecast detail, download the complete report from the PW Consulting site. This preview has been designed to show the strategic relevance of the study while preserving the granular data and scenario-ready analysis that buyers rely on for critical planning decisions.
Worldwide Cotton Bedsheets Market
For detailed analysis of this topic, please visit the official page: Cotton Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: VNA Market Projected to Reach $0.56 Billion by 2032; CAGR 3.38%
By pmarketresearch, 2026-09-15
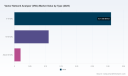
Navigating the Vector Network Analyzer Landscape: Strategic Intelligence for 2026 Decision-Makers
Executive Perspective
In the rapidly evolving ecosystem of radio frequency testing and measurement, the Vector Network Analyzer (VNA) Market stands as a critical barometer for technological advancement and industrial capability. As organizations prepare their capital allocation strategies for the forecast period extending to 2032, understanding the nuances of this market is not merely an technical necessity but a strategic imperative. This comprehensive market research report serves as a foundational tool for executives, procurement leaders, and R&D directors who must navigate a landscape defined by consolidation, technological specificity, and shifting regional demand patterns.
The current valuation of the sector reflects a mature yet steadily growing environment. With a historical trajectory from 2020 through 2025 showing resilience despite global supply chain fluctuations, the market has established a solid baseline. Looking forward, the projected compound annual growth rate indicates a moderate but consistent expansion path. This growth is not uniform across all segments; rather, it is driven by specific high-value applications and regional hubs of innovation. For enterprise decision-makers, the value of this research lies in its ability to translate raw numerical data into actionable intelligence regarding where capital should be deployed and which technologies warrant investment.
Market Trajectory and Scale
The financial architecture of the Vector Network Analyzer Market reveals a steady climb in revenue over the past half-decade. Historical data from 2020 to 2025 demonstrates a market that has maintained stability while incrementally increasing in value. Starting from a baseline in the early 2020s, the sector has progressed to a significant valuation by 2025. This stability suggests a robust underlying demand that is less susceptible to short-term economic volatility, likely anchored by long-term infrastructure projects and defense procurement cycles.
Vector Network Analyzer (VNA) Market
Forecasting into the future, the revenue projections indicate a continued upward trend. The market is expected to surpass previous ceilings as the forecast period progresses toward 2032. This growth trajectory is underpinned by a compound annual growth rate that suggests steady accumulation of value rather than explosive, unsustainable spikes. For stakeholders, this implies a market environment where long-term planning yields better returns than speculative short-term positioning. The consistency in revenue units, measured in billions of USD, underscores the significance of this sector within the broader electronic test and measurement industry.
It is crucial for leaders to recognize that these aggregate figures mask underlying complexities. The reported total market size is the sum of diverse segments, each with its own cost structures, adoption rates, and competitive pressures. Understanding the macro numbers is the first step, but the strategic advantage comes from dissecting how these figures are composed without necessarily exposing every granular detail publicly. This report provides the framework to understand that composition.
Worldwide Vector Network Test Instrument Market
Segmentation Dynamics and Demand Drivers
The demand for vector network analyzers is not monolithic. It is distributed across various frequency ranges and application verticals, each presenting unique opportunities and challenges. The market is segmented by type, reflecting the specific frequency capabilities required by different end-users. Lower frequency ranges continue to hold a substantial share, catering to general communication and manufacturing needs, while higher frequency segments command premium positioning due to their specialized use in advanced research and defense applications. The distribution across these frequency types indicates where the technical focus of the industry currently lies and where it is heading.
Similarly, the application landscape is diverse. Communications remain a dominant driver, fueled by the ongoing deployment of next-generation networks and the proliferation of connected devices. However, other sectors contribute significantly to the demand profile. Automotive applications are gaining traction as vehicle electronics become more complex, requiring rigorous testing protocols. Electronic manufacturing and aerospace and defense sectors also represent substantial pillars of demand, each necessitating specific instrument capabilities and compliance standards. The balance between these applications dictates the product roadmap for suppliers and the procurement strategy for buyers.
Regionally, the market exhibits a concentrated distribution of value. North America maintains a leading position, reflecting its strong presence in technology development and defense spending. Europe follows as a significant contributor, driven by its robust industrial base and regulatory standards. Asia Pacific represents a growing zone of interest, though its current share indicates room for expansion relative to the established hubs. Latin America and the Middle East and Africa constitute smaller portions of the global revenue mix, suggesting niche opportunities or emerging markets that may evolve over the forecast period. Understanding these regional weights helps organizations prioritize geographic expansion or supply chain localization efforts.
Competitive Landscape and Strategic Positioning
The competitive environment within the Vector Network Analyzer Market is characterized by high concentration and established player dominance. The industry structure suggests a barrier to entry that favors large, well-capitalized firms with extensive R&D capabilities. The concentration ratios indicate that a small number of key companies control a significant majority of the market revenue. This oligopolistic structure implies that pricing power, technological standardization, and customer loyalty are heavily influenced by the strategic moves of these top-tier entities.
Keysight Technologies, headquartered in Santa Rosa, California, remains a pivotal force in this arena. Their product portfolio, including the NA520xA PNA-X and VectorStar/Streamline families, exemplifies the high-end capabilities required to serve top-tier research and defense clients. Recent developments, such as the introduction of the NA520xA PNA-X Vector Network Analyzer with four RF sources and advanced receiver configurations, highlight their focus on enhancing measurement capability and complexity. Such product launches signal a market trend toward multifunctional instruments that can reduce overall system footprint while increasing testing throughput.
Rohde & Schwarz, based in Munich, Germany, competes with a strong emphasis on high-frequency performance. Their offerings, such as the ZNBT and ZVA series including multiport VNAs capable of operating up to 1.1 THz, target applications requiring extreme precision and frequency range. This focus aligns with the growing demand for millimeter-wave testing and advanced communication research. Their presence reinforces the necessity for buyers to evaluate frequency requirements carefully when selecting vendors, as the upper limits of operation often dictate the choice of equipment.
On the other end of the spectrum, Copper Mountain Technologies, located in Indianapolis, offers a different value proposition focused on accessibility and portability. Their 1-port and 2-port USB-powered VNAs with calibration modules cater to field applications and smaller scale operations where full-sized benchtop instruments may be impractical. This segmentation shows that the market supports both high-performance laboratory solutions and compact, cost-effective field solutions, allowing different tiers of users to access necessary testing capabilities.
Anritsu, headquartered in Morgan Hill, California, continues to expand its footprint through versatility. Their VNA Master series and VectorStar/ShockLine families provide a range of options for various testing scenarios. Recent developments, such as adding Vector Network Analyzer and Vector Voltmeter measurements to Site Master field portable instruments, demonstrate a strategy of integrating VNA capabilities into existing field tools. This convergence reduces the need for multiple devices in the field, enhancing efficiency for service providers and maintenance teams.
Industry Dynamics and Operational Realities
Navigating this market requires an understanding of the underlying dynamics that influence cost, compliance, and capability. One significant factor is the regulatory and accreditation environment. For instance, certain calibration laboratories associated with major players are accredited in accordance with the ISO/IEC 17025 international standard. This accreditation is critical for ensuring measurement traceability and compliance, particularly for industries like aerospace and defense where certification is mandatory. Buyers must consider the certification status of their suppliers and calibration services as part of their vendor qualification process.
Cost structures within the industry are influenced by technical complexity. High development and calibration costs associated with vector network analyzers require substantial investment in research and development, especially for high-frequency operation above 15 GHz. This technical barrier contributes to the market concentration observed among top players. Additionally, premium components and high-speed data acquisition systems further increase production expenses. These cost drivers affect pricing strategies and may influence the total cost of ownership for end-users, making lease-versus-buy decisions and service contract negotiations important strategic considerations.
Macro trends are also reshaping demand. Vector network analyzers are essential for precise RF testing compliance in 5G, IoT, and Industry 4.0 applications driving demand. As these technologies mature, the requirement for accurate impedance matching, signal integrity testing, and component characterization becomes more stringent. This technological dependency ensures that the VNA market remains tied to the broader growth of digital infrastructure and smart manufacturing initiatives. Organizations involved in these sectors must anticipate their testing equipment needs in alignment with their technology roadmaps.
Strategic Value of the Research Report
This market research report is designed to go beyond surface-level statistics. It provides a detailed examination of the factors that will define market success over the next several years. For executives, the report offers a structured analysis of market size, growth rates, and segmentation that supports financial modeling and budget forecasting. For technical leaders, it contextualizes product capabilities within the broader competitive landscape, helping to identify gaps in current tooling or opportunities for technology upgrades.
The report includes in-depth profiles of key companies, analyzing their recent developments and strategic focus areas. By understanding the product launches and capability additions of competitors, organizations can benchmark their own requirements and anticipate shifts in market availability. The inclusion of regulatory and cost dynamics provides a realistic view of the operational environment, helping to mitigate risks associated with compliance and procurement costs.
Furthermore, the segmentation analysis allows for targeted strategy development. Whether an organization is looking to enter a new geographic region or expand into a specific application vertical, the detailed breakdown of market splits provides the necessary context to evaluate potential returns. The report avoids generic assertions, instead offering specific insights derived from comprehensive data collection and analysis.
Ultimately, the goal of this research is to empower decision-makers with the confidence to act. In a market where concentration is high and technical barriers are significant, information asymmetry can lead to suboptimal choices. By consolidating data on market size, competitive moves, and industry dynamics into a single coherent narrative, this report reduces that asymmetry. It enables stakeholders to align their procurement strategies with market realities, ensuring that investments in vector network analysis capabilities support broader organizational goals.
Conclusion
The Vector Network Analyzer Market is poised for steady evolution through the forecast period ending in 2032. While the aggregate growth rates suggest a stable environment, the underlying segmentation and competitive dynamics offer rich opportunities for those who look deeper. The dominance of key players, the specific needs of high-frequency applications, and the regional distribution of demand all contribute to a complex landscape that requires careful navigation.
For organizations aiming to optimize their testing infrastructure or expand their market presence, access to granular data and expert analysis is indispensable. This report serves as a comprehensive guide to that intelligence. To fully unlock the strategic potential of these findings and access the detailed segmentation data, regional breakdowns, and company-specific revenue estimates, stakeholders are encouraged to consult the full report. The complete intelligence contained within provides the precision required for high-stakes decision-making in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Strainer Filter Market to Hit $5.73B by 2032, Growing at 5.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Decade Ahead: Navigating the 2026 Strainer Filter Market
In the complex ecosystem of industrial fluid management, the strainer filter serves as the quiet sentinel. Often overlooked until failure occurs, this component is critical for protecting pumps, valves, and sensitive process equipment from particulate contamination. As we move through 2026, the strainer filter market is not merely growing; it is evolving under the pressure of regulatory tightening, material cost fluctuations, and shifting industrial priorities. For executives and strategy leaders, understanding the trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and procurement optimization.
PW Consulting has released a comprehensive market research study covering the forecast period from 2026 to 2032. This article serves as a strategic preview of the findings, highlighting the macroeconomic currents shaping the industry while preserving the granular intelligence required for immediate executive decision-making. The full report offers the precise segmentation data necessary to calibrate your supply chain and investment strategies.
Market Trajectory and Growth Dynamics
The historical context provides a foundation for confidence. Between 2020 and 2025, the global strainer filter market demonstrated resilient expansion, overcoming supply chain disruptions that plagued broader manufacturing sectors. According to our analysis, the market valuation reached approximately 4,050.0 Million USD by the base year of 2025. This figure represents more than just revenue; it indicates a sustained industrial demand for flow control solutions across diverse sectors.
Looking forward, the projection indicates a steady compound annual growth rate (CAGR) of 5.2 percent throughout the forecast period ending in 2032. This growth rate suggests a market that is maturing but still retains significant expansion potential, driven by infrastructure renewals and stricter environmental compliance. The trajectory from 2026 through 2032 implies a cumulative increase that will reshape the competitive hierarchy. Stakeholders who rely on outdated volume assumptions risk either overstocking inventory or facing critical supply shortages during peak maintenance cycles.
It is important to note that this growth is not uniform. The velocity of expansion varies significantly based on material specifications, type configurations, and regional regulatory environments. Our full market study dissects these variances to reveal where the highest value opportunities reside. Accessing the complete dataset allows procurement leaders to align their purchasing forecasts with the specific growth pockets identified in the analysis.
Transportation and Logistics Considerations
Logistics play a pivotal role in the strainer filter market, particularly for large-diameter industrial units. The shipping dimensions and weight of duplex and basket strainers often require specialized freight handling. In 2026, fuel surcharges and freight capacity constraints continue to influence the landed cost of these components.
Worldwide Wire Mesh Filter Screen Market
- Freight optimization strategies are now integrated into lead time calculations.
- Regional warehousing is becoming more critical to mitigate supply chain latency.
- Import/export dynamics are shifting due to changes in trade policy compliance.
The research report details the logistical cost structures associated with different product types. For example, shipping requirements for large-scale temporary strainers used in pipeline commissioning differ vastly from those for compact inline strainers used in HVAC systems. Understanding these logistical nuances is essential for accurate total cost of ownership (TCO) modeling. The full report provides the breakdown needed to refine your logistics budget and vendor selection criteria.
Competitive Landscape and Key Players
The market structure is moderately consolidated, with the top three players holding a combined market share of 35.5 percent, while the top five entities command 42.8 percent. This concentration indicates a healthy balance between established incumbents and room for specialized competitors to gain traction. The presence of multiple key companies across different geographies suggests that no single entity dominates every segment, allowing for strategic sourcing flexibility.
Several prominent firms define the current competitive arena. Hayward Flow Control, based in Clemmons, NC, maintains a strong focus on plastic strainers for water and wastewater applications, utilizing materials like PVC and PVDF. Meanwhile, Alfa Laval, headquartered in Lund, Sweden, distinguishes itself in the hygienic sector with inline strainers tailored for dairy and beverage processing. Their recent expansion of a service center on the Gulf Coast in January 2026 underscores the strategic importance of regional maintenance support in retaining industrial clients.
Strainer Filter Market
In the fabricated metal sector, Weamco, Inc. and Gerard Daniel supply critical basket strainer elements and pipeline equipment. American Wheatley and NIBCO serve the plumbing and HVAC verticals with standardized Y-strainers and filtration systems. On the global manufacturing front, STV Valves and Brother Filtration provide competitive alternatives for process and chemical applications, often influencing pricing dynamics in the Asia Pacific region. Eaton Filtration remains a key reference for automatic self-cleaning strainers and hydraulic applications.
The interplay between these companies involves more than just product competition. Recent developments highlight the strategic moves shaping the landscape. In March 2026, the US Army Corps of Engineers updated maintenance standards requiring visual inspection and cleaning of strainers on project plans. This regulatory shift directly benefits manufacturers who can demonstrate compliance and durability. Furthermore, trade policy updates in February 2026, including Executive Order 14389, have altered the tariff landscape for stainless steel imports, impacting cost structures for companies relying on specific material origins.
The full market research report analyzes the strategic positioning of each key company, including their recent product launches, M&A activity, and regional sales footprints. This competitive intelligence is vital for benchmarking your own vendor relationships and identifying potential partners or acquisition targets.
Industry Drivers and Regulatory Headwinds
Market growth is being propelled by a combination of environmental mandates and operational efficiency goals. The EPA's enforcement of the Clean Water Act has tightened particulate discharge limits for industrial facilities. This regulatory pressure is increasing demand for high-efficiency mesh and basket strainers that can ensure compliance without frequent manual intervention. Similarly, NSF/ANSI listings for PVC and CPVC strainers have been updated for lead-free compliance under the Safe Drinking Water Act, opening new avenues for potable water applications while excluding non-compliant materials.
However, these opportunities come with constraints. Raw material costs remain a volatile factor. Tariff modifications on stainless steel mesh under Section 301 exclusions reduced costs for US importers in early 2026, providing a temporary relief window. Conversely, USITC HTS updates list stainless steel wire mesh under specific classifications with tariffs on EU-origin goods effective post-February 2026. These conflicting signals require close monitoring. A procurement strategy based on static material cost assumptions could lead to significant margin erosion.
In the chemical sector, EU REACH 2.0 compliance training is becoming mandatory for filtration professionals by September 2026. This regulatory requirement increases the barrier to entry for suppliers who cannot provide detailed material safety documentation. Our report evaluates how these regulatory shifts are reshaping the competitive field and influencing customer preference toward suppliers with robust compliance infrastructures.
Segmentation Insights: Product and Material Shifts
The market is diversified across several product types, each serving distinct operational needs. Y-strainers continue to hold a significant portion of the market due to their simplicity and widespread use in piping systems. T-strainers and duplex strainers cater to applications requiring higher flow rates or redundancy. Temporary strainers are essential for construction and commissioning phases, while automatic strainers are gaining ground in facilities aiming to reduce labor costs associated with manual cleaning.
Material selection is equally critical. Stainless steel remains the dominant material choice for corrosion resistance and hygiene, particularly in food and pharmaceutical applications. Cast iron and carbon steel serve heavy-duty industrial environments where cost is a primary driver. Plastic strainers are seeing increased adoption in chemical processing where corrosion resistance outweighs structural strength requirements. The specific revenue distribution among these types and materials reveals where investment is flowing. For instance, the shift toward automatic self-cleaning systems is altering the maintenance service revenue model for many integrators.
Applications span a wide range, from water and wastewater treatment, which represents a substantial volume of demand, to oil and gas, chemical processing, and power generation. Food and beverage, pharmaceutical, and pulp and paper industries also contribute significant segments, each with unique material and certification requirements. The growth rates within these application sectors are not identical. Some sectors are driven by new infrastructure builds, while others are driven by replacement cycles and retrofitting. Identifying which application segment offers the highest margin potential in 2026 requires a detailed view of the segmentation splits provided in the complete study.
Regional Market Variations
Geography plays a decisive role in market dynamics. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present unique opportunities and challenges. Asia Pacific continues to be a hub for manufacturing capacity and growing industrial demand. North America and Europe are characterized by stricter regulatory environments and a focus on high-efficiency, compliant solutions. Latin America and the Middle East and Africa offer growth potential tied to infrastructure development and energy sector investments.
Trade policies and logistics costs create regional price disparities. A strainer filter sourced in one region may face different tariff structures when exported to another. The recent adjustments in US trade policy regarding stainless steel imports illustrate how quickly regional cost advantages can shift. Companies operating globally must navigate these complexities to maintain competitive pricing. The full report provides a regional breakdown that helps strategists prioritize market entry or expansion efforts based on actual revenue potential rather than estimated demand.
Why Access the Full Research Report
This article provides a high-level strategic overview, but the complexity of the strainer filter market demands precision. The 5.2 percent CAGR and the 4,050.0 Million USD base year valuation are just the starting points. To make informed decisions regarding procurement contracts, capacity planning, or market entry, you need the underlying data.
PW Consulting's comprehensive Strainer Filter Market report delivers the depth required for action. Inside, you will find:
- Detailed revenue forecasts segmented by product type, material, application, and region through 2032.
- A complete profile of key competitors including their strategic focus and recent developments.
- Analysis of regulatory impacts on material costs and compliance requirements.
- Insights into market concentration and pricing trends.
- Scenario planning data to help navigate tariff changes and supply chain disruptions.
Do not rely on generalized trends when your capital allocation depends on specific market realities. The full report bridges the gap between macro observation and micro execution. Access the complete intelligence today to secure your strategic advantage in the 2026 strainer filter market and beyond.
For detailed analysis of this topic, please visit the official page: Strainer Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Brakes Market to Reach $1,961.21 Million by 2032, Growing at 4.4% CAGR: PW Consulting
By pmarketresearch, 2026-09-15
Strategic Imperative: Unlocking the Industrial Brakes Market Outlook for 2026 and Beyond
The global industrial landscape is entering a phase of precise mechanical evolution, where the means of production are increasingly demanding exacting standards for kinetic energy dissipation. At PW Consulting, we recognize that understanding the industrial brakes market is no longer just a matter of maintenance planning; it is a critical component of capital allocation, operational efficiency, and competitive positioning. This article serves as a strategic preview of our latest comprehensive market research, designed to equip enterprise decision-makers with the contextual intelligence required for the 2026 planning cycle. While this overview captures the macro trends and critical market dynamics, the full report provides the granular data necessary for precise forecasting and targeted investment.
Industrial Brakes Market
The sector exhibits resilience and steady expansion, underpinned by the foundational requirement that machinery, regardless of industry, must operate safely and efficiently. As we transition from the historical data of 2020 through 2025 into the forecast period of 2026 to 2032, the market trajectory suggests a continuation of measured growth. Enterprise leaders must look beyond the headline figures to understand the structural shifts driving this momentum, particularly regarding regional distribution, technological segmentation, and application-specific demands that define market segmentation.
Macro Trajectory and Market Scale
According to our latest analysis, the overall market size in 2025 is valued at approximately 1,454.4 million USD, having grown steadily from 1,200.0 million USD in 2020. This indicates a compound annual growth rate of 4.4% over the forecast period extending to 2032. While the top-line figures demonstrate consistent expansion, the strategic insight lies in understanding the distribution of this value across different geographies and sectors. The growth is not uniform; it is distributed across a complex web of regions, with Asia Pacific, North America, and Europe representing the bulk of revenue generation, while emerging markets in Latin America and the Mideast and Africa present distinct, albeit smaller, opportunities.
It is crucial for stakeholders to recognize that the 2026 outlook begins at an estimated 1,493.79 million USD and projects a continuous upward curve, reaching 1,961.21 million USD by 2032. This trajectory implies that the window for capturing market share in high-growth regions or high-value application segments is open, but competitive intensity is rising. The data reveals that while the market expands, the concentration of power among top players remains significant, with the top three companies holding a CR3 of 55.0% and the top five commanding a CR5 of 62.0%. This concentration suggests that while the pie is growing, the dominant players have entrenched positions, making strategic differentiation essential for mid-tier entrants and new investment opportunities.
Operational Intelligence: Deep Dive into Market Segmentation
The true value of this research lies in its dissection of the market into actionable segments. Decision-makers need to know not just that a market is growing, but which technologies and applications are driving that growth. Our report provides a granular breakdown that reveals the relative weight of disc brakes, drum brakes, caliper brakes, and other variants. Disc brakes, for instance, hold a commanding share of the type segmentation, reflecting a global shift in preference for braking technologies that offer superior heat dissipation and maintenance characteristics in specific industrial contexts. However, drum brakes remain relevant due to their simplicity and cost-effectiveness in rugged environments. Caliper brakes and other emerging types carve out specialized niches, particularly in applications requiring precise control and modular integration.
Application-Specific Dynamics
Application segmentation further clarifies where the demand is concentrated. Manufacturing is the primary driver, encompassing 505.88 million USD of the market, highlighting the reliance of continuous production lines on reliable braking systems for conveyors, packaging machinery, and material handling equipment. Metal and mining follows, representing a substantial 293.73 million USD, where heavy-duty braking solutions are critical for safety and load management in harsh environments. Construction, marine and shipping, and power generation each contribute meaningful segments, ranging from 146 to 147 million USD, indicating diverse use cases spanning mobile machinery, vessel operations, and energy infrastructure. The "others" category captures a broad array of specialized uses, reminding stakeholders that innovation is happening across the periphery as well.
Regional analysis in the full report maps these applications to specific geographic hotspots. While Asia Pacific leads in total volume, reflecting its massive manufacturing base, North America and Europe maintain significant shares due to mature industrial bases and high regulatory standards. Latin America and the Mideast and Africa represent smaller but strategically important markets where industrialization is accelerating. However, specific regional percentages and values are detailed exclusively in the downloadable dataset to empower analysts to build their own localized models without the constraints of pre-formatted summaries.
Competitive Landscape: The Major Players
The industrial brakes market is characterized by a competitive structure where key players have established strong footholds through specialized product portfolios and strategic focus. Our analysis profiles the core enterprises that define the competitive boundaries, offering insights into their headquarters, strategic positioning, and specific market offerings.
Regal Rexnord, headquartered in Bloomfield, Wisconsin, USA, stands as a prominent force in the sector. The company's profile emphasizes its specific offering for the industrial brakes market through the Warner Electric™ and Stearns™ brands, which provide industrial brakes and clutches tailored for packaging machinery. Their focus on high-performance solutions for the packaging sector aligns with the broader market trend of automation and efficiency in manufacturing. On June 16, 2026, Regal Rexnord demonstrated this commitment by exhibiting Warner Electric™ and Stearns™ brakes for packaging machinery at PACK EXPO International 2026, showcasing their direct engagement with trade events to capture opportunities in this application segment.
Niche Specialists and Modular Solutions
Coremo Ocmea, based in Milan, Italy, adds a distinct European dimension to the competitive landscape. The company focuses its offering on pneumatic caliper brakes and modular solutions, specifically targeting the converting and packaging industries. This specialization highlights the demand for flexible, pneumatically actuated braking systems that can integrate seamlessly into modern, modular production lines. The "modular solutions" aspect is particularly noteworthy, as it reflects a broader industry shift toward customizable machinery components that can adapt to varying production speeds and material handling requirements.
Stearns, also headquartered in Brookfield, Wisconsin, USA, reinforces the significance of the American market presence. Stearns offers spring-set power-off electric motor brakes and clutches designed for industrial packaging equipment. The spring-set mechanism is a key technology feature, providing a fail-safe design that ensures brakes engage automatically in the event of power loss, a critical safety requirement in industrial packaging environments. This company's focus mirrors the broader theme of safety and reliability driving product differentiation in the market.
These companies, along with others captured in the full report, compete not just on price but on technical capability, reliability, and the ability to integrate braking solutions into the broader ecosystem of industrial machinery. The high market concentration ratio indicates that these players have significant influence on pricing and technology standards, making competitive intelligence regarding their strategies essential for procurement and partnership decisions.
Dynamic Forces Shaping the 2026-2032 Horizon
Market growth does not occur in a vacuum. The period from 2026 to 2032 is influenced by a confluence of regulatory, economic, and raw material factors that can reshape demand patterns and cost structures. Our report integrates these external dynamics to provide a holistic view of the market environment.
Regulatory Pressures and Compliance Costs
Regulatory developments are exerting a profound influence on the industrial packaging and manufacturing sectors, which are key drivers of brake demand. The Packaging and Packaging Waste Regulation 2025/40 (PPWR), which entered into force on February 11, 2025, and will generally apply from August 12, 2026, represents a major shift in European policy. This regulation mandates national registers of producers to monitor compliance with Extended Producer Responsibility (EPR) requirements. For brake manufacturers and end-users, this implies that the machinery used in packaging production will be subject to stricter scrutiny regarding energy efficiency, waste generation, and operational lifespan. The compliance timeline aligns directly with the start of our forecast period, suggesting that the initial years of 2026-2028 may see increased investment in braking systems that support higher throughput and reduced downtime to meet regulatory standards for packaging production efficiency.
Simultaneously, EPR laws in the United States are moving toward compliance with key state deadlines in spring 2026, shifting packaging waste management costs to producers. This development may drive a consolidation of packaging production capabilities or a push for more durable, longer-lasting equipment, including industrial brakes, to mitigate total cost of ownership. Companies that can demonstrate the longevity and reliability of their braking systems may find a competitive advantage as producers seek to reduce the frequency of equipment replacement and maintenance.
Raw Material Volatility and Cost Implications
On the cost side, raw material fluctuations remain a persistent concern. Data indicates that the Producer Price Index for plastic materials and resin reached 285.0 in 2026, reflecting a 9.5% decrease from the previous year. While this decline in plastic costs might seem beneficial for the packaging industry, the broader implications for industrial brakes are nuanced. Plastic materials are often used in brake components such as friction pads, seals, and housing elements. A decrease in resin prices could lower the input costs for brake manufacturers, potentially improving margins or allowing for price stability in a competitive market. However, the market dynamics are complex, and cost savings in raw materials may be offset by increases in metal components or energy costs. The full report provides a deeper analysis of how these material cost trends intersect with supply chain logistics and regional pricing variations, enabling companies to model their procurement strategies more accurately.
Strategic Application of the Research
For enterprise leaders, the utility of this market research extends beyond passive observation. The data and insights contained in the full report are designed to support active strategic decision-making across several key functions.
In capital expenditure planning, the forecast data allows for precise timing of investments. Knowing that the market is projected to grow from 1,493.79 million USD in 2026 to 1,961.21 million USD in 2032 helps organizations validate the long-term viability of investments in braking technologies. Whether a company is expanding its manufacturing footprint, upgrading existing machinery, or entering new geographic markets, the market trajectory provides a quantitative basis for ROI projections.
Procurement and supply chain teams can leverage the segmentation data to negotiate more effectively. Understanding the relative dominance of disc brakes versus drum brakes, and the specific demands of the manufacturing and metal and mining applications, enables procurement professionals to align their purchasing strategies with current market supply and demand balances. The identification of key competitors like Regal Rexnord, Coremo Ocmea, and Stearns provides reference points for benchmarking product offerings and pricing structures.
Furthermore, the integration of regulatory and raw material insights allows for risk assessment and mitigation. Companies can anticipate how the PPWR and US EPR deadlines might alter demand patterns for packaging machinery brakes, or how fluctuations in plastic resin prices could affect component costs. This foresight enables proactive adjustments to inventory, supplier contracts, and product design roadmaps.
The market research also serves as a tool for competitive positioning. By analyzing the market concentration and the specific strengths of leading players, mid-sized manufacturers or new entrants can identify gaps in the market. For example, the high CR3 and CR5 figures suggest that the market is consolidated, but the growth to nearly 1,961 million USD by 2032 indicates room for expansion. Specialized players may find opportunities in underserved applications or regions, or by innovating in braking technologies that address specific pain points highlighted in the industry context, such as energy efficiency or modular integration.
Conclusion: The Value of Comprehensive Intelligence
The industrial brakes market is poised for steady growth over the 2026-2032 period, driven by the enduring needs of manufacturing, mining, construction, and energy sectors. However, the opportunities within this growth are nuanced, shaped by regional variations, technological preferences, application-specific demands, and a dynamic regulatory environment. The macro data tells a story of expansion, but the strategic decisions made by 2026 require a detailed map of the terrain.
Electric Parking Brake Market
This article has provided a high-level overview of the market size, CAGR, key segments, competitors, and industry dynamics. Yet, the depth of analysis required for precise strategic execution lies in the full dataset and proprietary analysis available in the complete PW Consulting report. The segment-specific revenue splits, exact regional allocations, and detailed competitor benchmarking are essential tools that transform general awareness into actionable intelligence. By accessing the full research, stakeholders can download the data, model their scenarios, and gain the confidence to navigate the complexities of the industrial brakes market with precision.
In a market where concentration is high and growth is steady, the advantage goes to those who understand the underlying structures. The forecast of a 4.4% CAGR and the trajectory toward nearly 2 billion USD by 2032 are compelling, but the path to capturing value depends on how well decision-makers can interpret the segmentation, dynamics, and competitive landscape. PW Consulting's comprehensive research is the instrument designed to provide that clarity, ensuring that your organization is not just reacting to the market, but strategically shaping its position within it.
For detailed analysis of this topic, please visit the official page: Industrial Brakes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com