

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rotary Kiln Market at USD 718.57M in 2025, Projected 3.1% CAGR to 2032

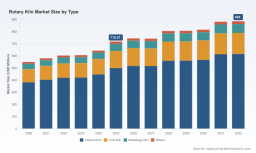
Navigating the Rotary Kiln Market: Strategic Intelligence for the 2026–2032 Horizon
The global rotary kiln industry stands at a critical inflection point. As we move through 2026, capital allocation decisions, capacity expansions, and technology roadmaps must be anchored in rigorous, forward-looking intelligence rather than historical extrapolation. PW Consulting’s latest Rotary Kiln Market research delivers precisely that strategic compass, synthesizing a decade of historical performance with a carefully modeled forecast window to equip executives, investors, and engineering leaders with actionable market clarity.
This report is not a static snapshot. It is a decision-support instrument engineered for the realities of mid-decade capital cycles, supply chain reconfiguration, and the accelerating push toward decarbonized thermal processing. Below, we outline the analytical architecture, the structural forces shaping the market trajectory, and the competitive dynamics that will separate resilient operators from marginal participants over the remainder of the decade.
Market Trajectory and the Strategic Imperative for 2026 Decision-Makers
The rotary kiln market has demonstrated consistent expansion through the 2020–2025 historical window, recovering from early-pandemic disruptions and capitalizing on sustained demand across core industrial processing sectors. By the close of 2025, the market crossed a significant threshold, with evaluated revenue reaching $718.57 million. That momentum carries into the forecast period, positioning 2026 as a foundational year where early-cycle investments in automation readiness, emission compliance tooling, and next-generation kiln configurations will compound into measurable competitive advantages.
Our modeling points to a five-year compound annual growth rate of approximately 3.1 percent across the forecast horizon. While that headline figure suggests measured, steady progression, the underlying trajectory is anything but uniform. Growth will be spatially uneven, technologically selective, and heavily influenced by raw material cost volatility, energy transition pacing, and the pace at which heavy industrial operators integrate digital process optimization into existing assets.
Strategic decision-makers must recognize that the mid-period forecast years contain meaningful inflection moments. Operators who understand where capacity additions will concentrate, which kiln configurations will command premium pricing, and how regional demand cycles align with local regulatory timelines will be positioned to capture disproportionate value. Those who rely on legacy procurement assumptions or unvalidated regional intuition will face margin compression, compliance friction, and stranded asset risk.
This is where comprehensive intelligence becomes indispensable. Understanding the interplay between shipment volumes, equipment lifecycle timing, and the pace of retrofit activity across installed base fleets requires structured, granular data that unpicks headline growth into operational signals. The differences between a kiln procurement decision delayed by six months versus one synchronized with regional regulatory deadlines or raw material pricing troughs can meaningfully alter project economics and return timelines.
Structural Fault Lines: Type, Application, and Regional Divergence
The rotary kiln ecosystem is inherently segmented by function, end-use processing requirements, and regional industrial maturity. At the equipment level, distinct kiln types serve fundamentally different thermal processing objectives, each with its own demand elasticity, capital intensity profile, and aftermarket service requirements. The dominance of established processing lines ensures that a substantial share of market value continues to flow through capital and maintenance cycles tied to large-scale cement and lime operations. Meanwhile, specialized configurations for metallurgy and other niche applications present differentiated entry barriers, customization demands, and service economics.
Worldwide Rotary Separator Market
By application, thermal processing demand is anchored by core industrial use cases that dictate throughput requirements, heat transfer design tolerances, and refractory lifecycle expectations. Cement production remains the gravitational center of the market, supported by ongoing upgrades to improve thermal efficiency and reduce specific fuel consumption. Metallurgical processing and chemical manufacturing applications contribute meaningful demand with distinct operating specifications, often requiring tighter control over residence time, atmosphere, and material throughput consistency. Emerging and auxiliary applications round out the demand profile, frequently serving specialized engineering, agricultural amendment, or waste processing needs where kiln performance intersects with material science requirements.
Geographically, the market reflects pronounced divergence. Asia Pacific continues to represent the largest demand footprint, driven by sustained industrial construction activity, grinding and pyro-processing capacity investments, and expanding mineral processing infrastructure. North America maintains a substantial position supported by mature cement, chemical, and waste-processing value chains alongside a strong aftermarket and retrofit services segment. Europe’s market profile is shaped less by volume expansion and more by compliance-driven upgrades, fuel-switching initiatives, and advanced filtration integration aimed at meeting increasingly stringent emissions thresholds. Latin America and the Middle East & Africa contribute more modest demand volumes but are characterized by project-stage volatility, selective large-scale capital deployments, and regional policy shifts that can accelerate or delay procurement cycles.
Rotary Kiln Market
Understanding these structural fault lines is essential because regional and application-level patterns do not move in lockstep. Procurement timing, specification requirements, local content expectations, and service ecosystem maturity vary considerably. A product strategy that works in one geography or application vertical often underperforms when exported without recalibration to local operating conditions, regulatory frameworks, and labor cost structures.
Technology Integration and Operational Dynamics Reshaping the Value Chain
The operational narrative of the rotary kiln market is being rewritten by three converging forces: raw material supply dynamics, digital process optimization, and regulatory tightening. Each force alters the economics of kiln ownership, the structure of service contracts, and the competitive positioning of equipment manufacturers and operating fleets.
Steel remains the essential raw material for rotary kiln construction shells, and its price instability creates direct sensitivity across total production costs. For equipment suppliers, this means that quoting frameworks, lead-time estimation, and contract structuring must account for material cost volatility rather than assuming stable bill-of-materials pricing. For operators, it reinforces the value of lifecycle service agreements, refractory management programs, and predictive maintenance capabilities that reduce unplanned downtime when procurement conditions tighten.
Digitalization is equally transformative. The integration of AI-based process optimization and IoT-enabled monitoring in cement and minerals plants has demonstrated measurable operational impact, reducing labor requirements for kiln operations while improving fuel efficiency by an estimated 10 to 15 percent. This is not merely a cost-reduction story. It reshapes asset utilization models, enables remote diagnostics, and shifts the competitive frontier from mechanical reliability alone to integrated operational intelligence. Operators that decouple throughput improvement from linear labor expansion gain a structural margin advantage, while manufacturers that embed monitoring, control logic, and performance analytics into their equipment offerings increasingly win on lifecycle value rather than installed cost alone.
Regulatory pressure adds another layer of strategic complexity. Stringent emission regulations in Europe require advanced filtration, optimized combustion, and fuel switching in rotary kilns to meet CO2, NOx, and particulate controls. Compliance is no longer an optional engineering add-on; it is increasingly a precondition for continued operation in high-scrutiny jurisdictions. At the same time, standardization efforts are expanding the material applications of rotary kiln-produced outputs. The ASTM D5883 standard provides guidance for using rotary kiln-produced expanded shale, clay, or slate as a mineral amendment in topsoil, while ASTM D8249 specifies material characteristics, physical requirements, and sampling for rotary kiln-produced porous aggregates. These standards validate new market applications, creating incremental demand pathways that intersect directly with kiln design choices and operational flexibility.
Together, these dynamics create a market environment where procurement, operations, and compliance cannot be managed in isolation. Engineering teams must plan for multi-variable operating envelopes. Procurement leaders must negotiate around material volatility and lead-time risk. Plant managers must assess retrofit versus replacement paths with regard to both emissions compliance and digital readiness. Strategic intelligence that integrates these dimensions gives executives the ability to prioritize investments where they yield compounding operational and regulatory returns.
Competitive Architecture: Scale, Specialization, and Strategic Posture
The competitive landscape of the rotary kiln market is defined by a blend of global equipment majors, engineering specialists, regional manufacturing leaders, and application-focused technology firms. Market concentration metrics underscore a moderately consolidated environment, with CR3 and CR5 levels reflecting the influence of a handful of large, internationally active players alongside a broad base of regional and custom-solution providers.
FLSmidth stands out as a global leader in cement and minerals equipment, with more than 500 installed or upgraded kiln lines worldwide. Its profile reflects a scale-driven, project-integrated approach that spans engineering, delivery, and long-cycle service support. Recent activity illustrates how the company is expanding the technical frontier of its offerings: in May 2025, FLSmidth delivered a cutting-edge 115-meter rotary kiln to Sibanye-Stillwater’s Keliber lithium refinery, signaling the market’s growing relevance beyond traditional cement and minerals applications and the increasing demand for large-format, process-specific kiln systems.
KHD Humboldt Wedag brings deep German engineering specialization in cement industry rotary kiln systems, positioning itself around process reliability, design heritage, and integration expertise for core pyro-processing applications. thyssenkrupp Polysius operates in a similar strategic lane with integrated pyro-processing rotary kiln systems, emphasizing tightly coupled equipment architectures that align thermal processing, preheater logic, and downstream material handling. Both firms compete on engineering depth, system-level optimization, and the ability to deliver kiln solutions that reduce downstream inefficiencies rather than just hardware specifications.
On the North American side, FEECO International operates as a custom rotary kiln manufacturer with strong capabilities in pilot-scale testing and batch or pilot facilities. This positions the company to serve clients that require flexible development pathways, material-specific process validation, and customized thermal processing solutions before full-scale deployment. HiTemp Tech Corporation complements the landscape with factory-built rotary kiln incineration systems for solid waste at throughput ranges from 12 to 100 tons per day, representing a distinctly application-oriented segment where regulatory compliance, emissions control, and compact thermal processing design are central competitive factors.
Chinese manufacturers represent a substantial and rapidly evolving competitive presence. CITIC Heavy Industries has manufactured more than 1,000 rotary kilns, including cement, lime, and pellet types for global markets, reflecting large-scale production capacity and broad application coverage. AGICO Cement Machinery is a leading supplier of cement rotary kilns, lime kilns, and shaft kilns with factory-direct solutions, and its recent project activity underscores the pace of operating-asset modernization in the sector. In September 2025, AGICO completed a rotary kiln revamp project for a 5,000 t/d cement production line with a double five-stage preheater and TTF decomposition furnace, a clear example of how retrofit and upgrade activity is becoming a strategic battleground for both OEMs and aftermarket service providers.
Jiangsu Pengfei Group rounds out the competitive field as a custom rotary kiln supplier for cement plants and wet-pulp caustic processes. Its recent engagement highlights cross-application demand linkages: in March 2025, Jiangsu Pengfei secured an order for two wet-pulp caustic rotary kilns with Valmet Europe, demonstrating how kiln technology is embedded into broader process chains and how international partnerships shape deployment pathways.
Taken together, the competitive architecture reveals three strategic archetypes. First, global integrators that compete on scale, installed base, and system-level engineering. Second, specialists and application-focused manufacturers that compete on customization, pilot validation, and niche compliance demands. Third, large-volume producers that compete on manufacturing capacity, broad product scope, and aggressive project execution. The strategic takeaway is that positioning in this market does not map cleanly to a single competitive axis. Pricing, service, customization, compliance capability, and delivery reliability each carry weight depending on geography, application, and project stage.
What This Market Study Delivers for Executive Decision-Making
This study is structured to convert market complexity into decision readiness. It combines historical reconstruction with forward modeling, competitive profiling with application-specific demand analysis, and regulatory and operational context with practical strategic framing. The analysis is designed for multiple audiences within an enterprise: strategy and corporate development teams assessing portfolio and geographic direction, engineering leaders evaluating equipment and retrofit pathways, procurement leaders aligning sourcing with material cost and lead-time risk, and investors or lenders requiring structured visibility into demand durability and competitive positioning.
Report content is built around operational utility. It maps the demand architecture across kiln type and application so that teams can identify where volume concentration and specification complexity create different procurement, service, and pricing dynamics. It evaluates regional market profiles in a way that respects local regulatory timelines, industrial maturity, and project-stage volatility rather than treating geography as a simple share table. It embeds competitive intelligence around the companies shaping the market today, including their technological focus, delivery posture, and recent developments that signal where capability and demand are converging.
Equally important, the study integrates the external forces that alter the battlefield. Raw material cost exposure, digital process optimization, emissions compliance requirements, and standards-driven material applications are not treated as background noise. They are analyzed as demand modifiers and operational constraints that affect payback calculations, service contract design, retrofit prioritization, and competitive differentiation. Recent 2025 developments are incorporated to illustrate how large-format equipment, cross-border partnerships, and retrofit modernization are actively reshaping the market rhythm.
The output is intended to support concrete decisions: which segments warrant focused commercial attention, where retrofit opportunity intersects with compliance deadlines, how regional demand cycles should inform capacity and partnership strategy, and which competitive differentiators are likely to matter most as digitalization and emissions requirements become normalized operating expectations.
The Strategic Case for Deeper Intelligence in 2026
The rotary kiln market of 2026 is not a single trajectory. It is a set of overlapping demand cycles, compliance-driven upgrade paths, digital readiness imperatives, and regionally distinct procurement rhythms. Executives who attempt to navigate these layers with high-level summaries or purely historical assumptions will miss where value is actually created and where exposure accumulates.
PW Consulting’s Rotary Kiln Market research is designed to close that gap. By combining modeled market progression with structural segment analysis, competitive profiling, and operational context, it provides a foundation for capital planning, product and service strategy, and operational investment prioritization. The full report goes further, offering the detailed segmentation intelligence, regional demand narratives, competitive benchmarking granularity, and application-specific dynamics that executives need to translate market direction into committed action.
For organizations preparing to allocate capital, renew equipment lifecycles, expand processing capacity, or reposition service offerings through 2026 and beyond, the difference between assumption and evidence is material. Deeper market intelligence enables sharper segmentation choices, better-timed procurement decisions, and more resilient competitive positioning as the market moves through the forecast period.
For detailed analysis of this topic, please visit the official page: Rotary Kiln Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com