

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Strainer Filter Market to Hit $5.73B by 2032, Growing at 5.2% CAGR

Strategic Intelligence for the Decade Ahead: Navigating the 2026 Strainer Filter Market
In the complex ecosystem of industrial fluid management, the strainer filter serves as the quiet sentinel. Often overlooked until failure occurs, this component is critical for protecting pumps, valves, and sensitive process equipment from particulate contamination. As we move through 2026, the strainer filter market is not merely growing; it is evolving under the pressure of regulatory tightening, material cost fluctuations, and shifting industrial priorities. For executives and strategy leaders, understanding the trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and procurement optimization.
PW Consulting has released a comprehensive market research study covering the forecast period from 2026 to 2032. This article serves as a strategic preview of the findings, highlighting the macroeconomic currents shaping the industry while preserving the granular intelligence required for immediate executive decision-making. The full report offers the precise segmentation data necessary to calibrate your supply chain and investment strategies.
Market Trajectory and Growth Dynamics
The historical context provides a foundation for confidence. Between 2020 and 2025, the global strainer filter market demonstrated resilient expansion, overcoming supply chain disruptions that plagued broader manufacturing sectors. According to our analysis, the market valuation reached approximately 4,050.0 Million USD by the base year of 2025. This figure represents more than just revenue; it indicates a sustained industrial demand for flow control solutions across diverse sectors.
Looking forward, the projection indicates a steady compound annual growth rate (CAGR) of 5.2 percent throughout the forecast period ending in 2032. This growth rate suggests a market that is maturing but still retains significant expansion potential, driven by infrastructure renewals and stricter environmental compliance. The trajectory from 2026 through 2032 implies a cumulative increase that will reshape the competitive hierarchy. Stakeholders who rely on outdated volume assumptions risk either overstocking inventory or facing critical supply shortages during peak maintenance cycles.
It is important to note that this growth is not uniform. The velocity of expansion varies significantly based on material specifications, type configurations, and regional regulatory environments. Our full market study dissects these variances to reveal where the highest value opportunities reside. Accessing the complete dataset allows procurement leaders to align their purchasing forecasts with the specific growth pockets identified in the analysis.
Transportation and Logistics Considerations
Logistics play a pivotal role in the strainer filter market, particularly for large-diameter industrial units. The shipping dimensions and weight of duplex and basket strainers often require specialized freight handling. In 2026, fuel surcharges and freight capacity constraints continue to influence the landed cost of these components.
Worldwide Wire Mesh Filter Screen Market
- Freight optimization strategies are now integrated into lead time calculations.
- Regional warehousing is becoming more critical to mitigate supply chain latency.
- Import/export dynamics are shifting due to changes in trade policy compliance.
The research report details the logistical cost structures associated with different product types. For example, shipping requirements for large-scale temporary strainers used in pipeline commissioning differ vastly from those for compact inline strainers used in HVAC systems. Understanding these logistical nuances is essential for accurate total cost of ownership (TCO) modeling. The full report provides the breakdown needed to refine your logistics budget and vendor selection criteria.
Competitive Landscape and Key Players
The market structure is moderately consolidated, with the top three players holding a combined market share of 35.5 percent, while the top five entities command 42.8 percent. This concentration indicates a healthy balance between established incumbents and room for specialized competitors to gain traction. The presence of multiple key companies across different geographies suggests that no single entity dominates every segment, allowing for strategic sourcing flexibility.
Several prominent firms define the current competitive arena. Hayward Flow Control, based in Clemmons, NC, maintains a strong focus on plastic strainers for water and wastewater applications, utilizing materials like PVC and PVDF. Meanwhile, Alfa Laval, headquartered in Lund, Sweden, distinguishes itself in the hygienic sector with inline strainers tailored for dairy and beverage processing. Their recent expansion of a service center on the Gulf Coast in January 2026 underscores the strategic importance of regional maintenance support in retaining industrial clients.
Strainer Filter Market
In the fabricated metal sector, Weamco, Inc. and Gerard Daniel supply critical basket strainer elements and pipeline equipment. American Wheatley and NIBCO serve the plumbing and HVAC verticals with standardized Y-strainers and filtration systems. On the global manufacturing front, STV Valves and Brother Filtration provide competitive alternatives for process and chemical applications, often influencing pricing dynamics in the Asia Pacific region. Eaton Filtration remains a key reference for automatic self-cleaning strainers and hydraulic applications.
The interplay between these companies involves more than just product competition. Recent developments highlight the strategic moves shaping the landscape. In March 2026, the US Army Corps of Engineers updated maintenance standards requiring visual inspection and cleaning of strainers on project plans. This regulatory shift directly benefits manufacturers who can demonstrate compliance and durability. Furthermore, trade policy updates in February 2026, including Executive Order 14389, have altered the tariff landscape for stainless steel imports, impacting cost structures for companies relying on specific material origins.
The full market research report analyzes the strategic positioning of each key company, including their recent product launches, M&A activity, and regional sales footprints. This competitive intelligence is vital for benchmarking your own vendor relationships and identifying potential partners or acquisition targets.
Industry Drivers and Regulatory Headwinds
Market growth is being propelled by a combination of environmental mandates and operational efficiency goals. The EPA's enforcement of the Clean Water Act has tightened particulate discharge limits for industrial facilities. This regulatory pressure is increasing demand for high-efficiency mesh and basket strainers that can ensure compliance without frequent manual intervention. Similarly, NSF/ANSI listings for PVC and CPVC strainers have been updated for lead-free compliance under the Safe Drinking Water Act, opening new avenues for potable water applications while excluding non-compliant materials.
However, these opportunities come with constraints. Raw material costs remain a volatile factor. Tariff modifications on stainless steel mesh under Section 301 exclusions reduced costs for US importers in early 2026, providing a temporary relief window. Conversely, USITC HTS updates list stainless steel wire mesh under specific classifications with tariffs on EU-origin goods effective post-February 2026. These conflicting signals require close monitoring. A procurement strategy based on static material cost assumptions could lead to significant margin erosion.
In the chemical sector, EU REACH 2.0 compliance training is becoming mandatory for filtration professionals by September 2026. This regulatory requirement increases the barrier to entry for suppliers who cannot provide detailed material safety documentation. Our report evaluates how these regulatory shifts are reshaping the competitive field and influencing customer preference toward suppliers with robust compliance infrastructures.
Segmentation Insights: Product and Material Shifts
The market is diversified across several product types, each serving distinct operational needs. Y-strainers continue to hold a significant portion of the market due to their simplicity and widespread use in piping systems. T-strainers and duplex strainers cater to applications requiring higher flow rates or redundancy. Temporary strainers are essential for construction and commissioning phases, while automatic strainers are gaining ground in facilities aiming to reduce labor costs associated with manual cleaning.
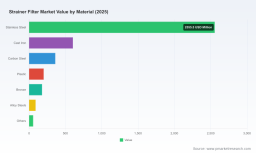
Material selection is equally critical. Stainless steel remains the dominant material choice for corrosion resistance and hygiene, particularly in food and pharmaceutical applications. Cast iron and carbon steel serve heavy-duty industrial environments where cost is a primary driver. Plastic strainers are seeing increased adoption in chemical processing where corrosion resistance outweighs structural strength requirements. The specific revenue distribution among these types and materials reveals where investment is flowing. For instance, the shift toward automatic self-cleaning systems is altering the maintenance service revenue model for many integrators.
Applications span a wide range, from water and wastewater treatment, which represents a substantial volume of demand, to oil and gas, chemical processing, and power generation. Food and beverage, pharmaceutical, and pulp and paper industries also contribute significant segments, each with unique material and certification requirements. The growth rates within these application sectors are not identical. Some sectors are driven by new infrastructure builds, while others are driven by replacement cycles and retrofitting. Identifying which application segment offers the highest margin potential in 2026 requires a detailed view of the segmentation splits provided in the complete study.
Regional Market Variations
Geography plays a decisive role in market dynamics. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present unique opportunities and challenges. Asia Pacific continues to be a hub for manufacturing capacity and growing industrial demand. North America and Europe are characterized by stricter regulatory environments and a focus on high-efficiency, compliant solutions. Latin America and the Middle East and Africa offer growth potential tied to infrastructure development and energy sector investments.
Trade policies and logistics costs create regional price disparities. A strainer filter sourced in one region may face different tariff structures when exported to another. The recent adjustments in US trade policy regarding stainless steel imports illustrate how quickly regional cost advantages can shift. Companies operating globally must navigate these complexities to maintain competitive pricing. The full report provides a regional breakdown that helps strategists prioritize market entry or expansion efforts based on actual revenue potential rather than estimated demand.
Why Access the Full Research Report
This article provides a high-level strategic overview, but the complexity of the strainer filter market demands precision. The 5.2 percent CAGR and the 4,050.0 Million USD base year valuation are just the starting points. To make informed decisions regarding procurement contracts, capacity planning, or market entry, you need the underlying data.
PW Consulting's comprehensive Strainer Filter Market report delivers the depth required for action. Inside, you will find:
- Detailed revenue forecasts segmented by product type, material, application, and region through 2032.
- A complete profile of key competitors including their strategic focus and recent developments.
- Analysis of regulatory impacts on material costs and compliance requirements.
- Insights into market concentration and pricing trends.
- Scenario planning data to help navigate tariff changes and supply chain disruptions.
Do not rely on generalized trends when your capital allocation depends on specific market realities. The full report bridges the gap between macro observation and micro execution. Access the complete intelligence today to secure your strategic advantage in the 2026 strainer filter market and beyond.
For detailed analysis of this topic, please visit the official page: Strainer Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com