

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Brakes Market to Reach $1,961.21 Million by 2032, Growing at 4.4% CAGR: PW Consulting

Strategic Imperative: Unlocking the Industrial Brakes Market Outlook for 2026 and Beyond
The global industrial landscape is entering a phase of precise mechanical evolution, where the means of production are increasingly demanding exacting standards for kinetic energy dissipation. At PW Consulting, we recognize that understanding the industrial brakes market is no longer just a matter of maintenance planning; it is a critical component of capital allocation, operational efficiency, and competitive positioning. This article serves as a strategic preview of our latest comprehensive market research, designed to equip enterprise decision-makers with the contextual intelligence required for the 2026 planning cycle. While this overview captures the macro trends and critical market dynamics, the full report provides the granular data necessary for precise forecasting and targeted investment.
Industrial Brakes Market
The sector exhibits resilience and steady expansion, underpinned by the foundational requirement that machinery, regardless of industry, must operate safely and efficiently. As we transition from the historical data of 2020 through 2025 into the forecast period of 2026 to 2032, the market trajectory suggests a continuation of measured growth. Enterprise leaders must look beyond the headline figures to understand the structural shifts driving this momentum, particularly regarding regional distribution, technological segmentation, and application-specific demands that define market segmentation.
Macro Trajectory and Market Scale
According to our latest analysis, the overall market size in 2025 is valued at approximately 1,454.4 million USD, having grown steadily from 1,200.0 million USD in 2020. This indicates a compound annual growth rate of 4.4% over the forecast period extending to 2032. While the top-line figures demonstrate consistent expansion, the strategic insight lies in understanding the distribution of this value across different geographies and sectors. The growth is not uniform; it is distributed across a complex web of regions, with Asia Pacific, North America, and Europe representing the bulk of revenue generation, while emerging markets in Latin America and the Mideast and Africa present distinct, albeit smaller, opportunities.
It is crucial for stakeholders to recognize that the 2026 outlook begins at an estimated 1,493.79 million USD and projects a continuous upward curve, reaching 1,961.21 million USD by 2032. This trajectory implies that the window for capturing market share in high-growth regions or high-value application segments is open, but competitive intensity is rising. The data reveals that while the market expands, the concentration of power among top players remains significant, with the top three companies holding a CR3 of 55.0% and the top five commanding a CR5 of 62.0%. This concentration suggests that while the pie is growing, the dominant players have entrenched positions, making strategic differentiation essential for mid-tier entrants and new investment opportunities.
Operational Intelligence: Deep Dive into Market Segmentation
The true value of this research lies in its dissection of the market into actionable segments. Decision-makers need to know not just that a market is growing, but which technologies and applications are driving that growth. Our report provides a granular breakdown that reveals the relative weight of disc brakes, drum brakes, caliper brakes, and other variants. Disc brakes, for instance, hold a commanding share of the type segmentation, reflecting a global shift in preference for braking technologies that offer superior heat dissipation and maintenance characteristics in specific industrial contexts. However, drum brakes remain relevant due to their simplicity and cost-effectiveness in rugged environments. Caliper brakes and other emerging types carve out specialized niches, particularly in applications requiring precise control and modular integration.
Application-Specific Dynamics
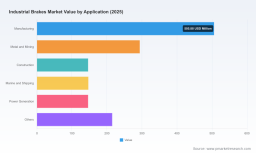
Application segmentation further clarifies where the demand is concentrated. Manufacturing is the primary driver, encompassing 505.88 million USD of the market, highlighting the reliance of continuous production lines on reliable braking systems for conveyors, packaging machinery, and material handling equipment. Metal and mining follows, representing a substantial 293.73 million USD, where heavy-duty braking solutions are critical for safety and load management in harsh environments. Construction, marine and shipping, and power generation each contribute meaningful segments, ranging from 146 to 147 million USD, indicating diverse use cases spanning mobile machinery, vessel operations, and energy infrastructure. The "others" category captures a broad array of specialized uses, reminding stakeholders that innovation is happening across the periphery as well.
Regional analysis in the full report maps these applications to specific geographic hotspots. While Asia Pacific leads in total volume, reflecting its massive manufacturing base, North America and Europe maintain significant shares due to mature industrial bases and high regulatory standards. Latin America and the Mideast and Africa represent smaller but strategically important markets where industrialization is accelerating. However, specific regional percentages and values are detailed exclusively in the downloadable dataset to empower analysts to build their own localized models without the constraints of pre-formatted summaries.
Competitive Landscape: The Major Players
The industrial brakes market is characterized by a competitive structure where key players have established strong footholds through specialized product portfolios and strategic focus. Our analysis profiles the core enterprises that define the competitive boundaries, offering insights into their headquarters, strategic positioning, and specific market offerings.
Regal Rexnord, headquartered in Bloomfield, Wisconsin, USA, stands as a prominent force in the sector. The company's profile emphasizes its specific offering for the industrial brakes market through the Warner Electric™ and Stearns™ brands, which provide industrial brakes and clutches tailored for packaging machinery. Their focus on high-performance solutions for the packaging sector aligns with the broader market trend of automation and efficiency in manufacturing. On June 16, 2026, Regal Rexnord demonstrated this commitment by exhibiting Warner Electric™ and Stearns™ brakes for packaging machinery at PACK EXPO International 2026, showcasing their direct engagement with trade events to capture opportunities in this application segment.
Niche Specialists and Modular Solutions
Coremo Ocmea, based in Milan, Italy, adds a distinct European dimension to the competitive landscape. The company focuses its offering on pneumatic caliper brakes and modular solutions, specifically targeting the converting and packaging industries. This specialization highlights the demand for flexible, pneumatically actuated braking systems that can integrate seamlessly into modern, modular production lines. The "modular solutions" aspect is particularly noteworthy, as it reflects a broader industry shift toward customizable machinery components that can adapt to varying production speeds and material handling requirements.
Stearns, also headquartered in Brookfield, Wisconsin, USA, reinforces the significance of the American market presence. Stearns offers spring-set power-off electric motor brakes and clutches designed for industrial packaging equipment. The spring-set mechanism is a key technology feature, providing a fail-safe design that ensures brakes engage automatically in the event of power loss, a critical safety requirement in industrial packaging environments. This company's focus mirrors the broader theme of safety and reliability driving product differentiation in the market.
These companies, along with others captured in the full report, compete not just on price but on technical capability, reliability, and the ability to integrate braking solutions into the broader ecosystem of industrial machinery. The high market concentration ratio indicates that these players have significant influence on pricing and technology standards, making competitive intelligence regarding their strategies essential for procurement and partnership decisions.
Dynamic Forces Shaping the 2026-2032 Horizon
Market growth does not occur in a vacuum. The period from 2026 to 2032 is influenced by a confluence of regulatory, economic, and raw material factors that can reshape demand patterns and cost structures. Our report integrates these external dynamics to provide a holistic view of the market environment.
Regulatory Pressures and Compliance Costs
Regulatory developments are exerting a profound influence on the industrial packaging and manufacturing sectors, which are key drivers of brake demand. The Packaging and Packaging Waste Regulation 2025/40 (PPWR), which entered into force on February 11, 2025, and will generally apply from August 12, 2026, represents a major shift in European policy. This regulation mandates national registers of producers to monitor compliance with Extended Producer Responsibility (EPR) requirements. For brake manufacturers and end-users, this implies that the machinery used in packaging production will be subject to stricter scrutiny regarding energy efficiency, waste generation, and operational lifespan. The compliance timeline aligns directly with the start of our forecast period, suggesting that the initial years of 2026-2028 may see increased investment in braking systems that support higher throughput and reduced downtime to meet regulatory standards for packaging production efficiency.
Simultaneously, EPR laws in the United States are moving toward compliance with key state deadlines in spring 2026, shifting packaging waste management costs to producers. This development may drive a consolidation of packaging production capabilities or a push for more durable, longer-lasting equipment, including industrial brakes, to mitigate total cost of ownership. Companies that can demonstrate the longevity and reliability of their braking systems may find a competitive advantage as producers seek to reduce the frequency of equipment replacement and maintenance.
Raw Material Volatility and Cost Implications
On the cost side, raw material fluctuations remain a persistent concern. Data indicates that the Producer Price Index for plastic materials and resin reached 285.0 in 2026, reflecting a 9.5% decrease from the previous year. While this decline in plastic costs might seem beneficial for the packaging industry, the broader implications for industrial brakes are nuanced. Plastic materials are often used in brake components such as friction pads, seals, and housing elements. A decrease in resin prices could lower the input costs for brake manufacturers, potentially improving margins or allowing for price stability in a competitive market. However, the market dynamics are complex, and cost savings in raw materials may be offset by increases in metal components or energy costs. The full report provides a deeper analysis of how these material cost trends intersect with supply chain logistics and regional pricing variations, enabling companies to model their procurement strategies more accurately.
Strategic Application of the Research
For enterprise leaders, the utility of this market research extends beyond passive observation. The data and insights contained in the full report are designed to support active strategic decision-making across several key functions.
In capital expenditure planning, the forecast data allows for precise timing of investments. Knowing that the market is projected to grow from 1,493.79 million USD in 2026 to 1,961.21 million USD in 2032 helps organizations validate the long-term viability of investments in braking technologies. Whether a company is expanding its manufacturing footprint, upgrading existing machinery, or entering new geographic markets, the market trajectory provides a quantitative basis for ROI projections.
Procurement and supply chain teams can leverage the segmentation data to negotiate more effectively. Understanding the relative dominance of disc brakes versus drum brakes, and the specific demands of the manufacturing and metal and mining applications, enables procurement professionals to align their purchasing strategies with current market supply and demand balances. The identification of key competitors like Regal Rexnord, Coremo Ocmea, and Stearns provides reference points for benchmarking product offerings and pricing structures.
Furthermore, the integration of regulatory and raw material insights allows for risk assessment and mitigation. Companies can anticipate how the PPWR and US EPR deadlines might alter demand patterns for packaging machinery brakes, or how fluctuations in plastic resin prices could affect component costs. This foresight enables proactive adjustments to inventory, supplier contracts, and product design roadmaps.
The market research also serves as a tool for competitive positioning. By analyzing the market concentration and the specific strengths of leading players, mid-sized manufacturers or new entrants can identify gaps in the market. For example, the high CR3 and CR5 figures suggest that the market is consolidated, but the growth to nearly 1,961 million USD by 2032 indicates room for expansion. Specialized players may find opportunities in underserved applications or regions, or by innovating in braking technologies that address specific pain points highlighted in the industry context, such as energy efficiency or modular integration.
Conclusion: The Value of Comprehensive Intelligence
The industrial brakes market is poised for steady growth over the 2026-2032 period, driven by the enduring needs of manufacturing, mining, construction, and energy sectors. However, the opportunities within this growth are nuanced, shaped by regional variations, technological preferences, application-specific demands, and a dynamic regulatory environment. The macro data tells a story of expansion, but the strategic decisions made by 2026 require a detailed map of the terrain.
Electric Parking Brake Market
This article has provided a high-level overview of the market size, CAGR, key segments, competitors, and industry dynamics. Yet, the depth of analysis required for precise strategic execution lies in the full dataset and proprietary analysis available in the complete PW Consulting report. The segment-specific revenue splits, exact regional allocations, and detailed competitor benchmarking are essential tools that transform general awareness into actionable intelligence. By accessing the full research, stakeholders can download the data, model their scenarios, and gain the confidence to navigate the complexities of the industrial brakes market with precision.
In a market where concentration is high and growth is steady, the advantage goes to those who understand the underlying structures. The forecast of a 4.4% CAGR and the trajectory toward nearly 2 billion USD by 2032 are compelling, but the path to capturing value depends on how well decision-makers can interpret the segmentation, dynamics, and competitive landscape. PW Consulting's comprehensive research is the instrument designed to provide that clarity, ensuring that your organization is not just reacting to the market, but strategically shaping its position within it.
For detailed analysis of this topic, please visit the official page: Industrial Brakes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com