

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Neutron Generator Market to Reach $93.45M by 2032, 6.95% CAGR from 2025
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Neutron Generators Market: Navigating Growth, Regulation, and Competitive Shifts in 2026
The global neutron generators market stands at a critical inflection point as organizations across energy, security, healthcare, and advanced materials sectors increasingly rely on compact, high-performance neutron sources to drive operational efficiency and innovation. Our latest market research delivers a comprehensive, data-driven assessment of this evolving landscape, providing executives, investors, and technology strategists with the actionable intelligence needed to make informed decisions throughout the 2026–2032 forecast horizon. For enterprises evaluating capital allocation, product roadmaps, or geographic expansion, this study functions as a strategic compass, translating complex market signals into clear, executable pathways.
Executive Market Trajectory: 2020–2032 Growth Arc
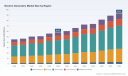
Drawing on historical performance data spanning 2020 through 2025, the market has demonstrated consistent expansion, evolving from a 45.23 million USD baseline in 2020 to an estimated 58.45 million USD in 2025. This trajectory reflects sustained industrial demand, incremental technological maturation, and broadening application portfolios across both developed and emerging economies. Looking ahead, the forecast period extends through 2032, with projected revenues climbing toward 93.45 million USD by the terminal year. The market is expected to advance at a compound annual growth rate of 6.95 percent, signaling steady, structurally supported expansion rather than speculative volatility.
For corporate planners, this growth profile carries immediate implications. Capital-intensive applications are increasingly favoring modular, high-yield neutron systems that reduce operational downtime and integrate seamlessly into existing workflows. Meanwhile, procurement cycles in regulated sectors are lengthening, demanding earlier strategic alignment between engineering teams, compliance officers, and supply chain managers. Organizations that institutionalize market intelligence now will be better positioned to anticipate demand spikes, prioritize capacity investments, and negotiate favorable terms with upstream component suppliers.
High Frequency X-Ray Generators Market
Segmentation Dynamics and Application Realities
The market structure reflects a diverse mix of deployment formats, end-use requirements, and regional maturity levels. Portable systems continue to capture meaningful share, driven by field-deployable inspection, on-site materials analysis, and mobile security screening requirements. Stationary configurations maintain strong institutional demand, particularly in laboratory environments, industrial quality assurance lines, and specialized medical research facilities where sustained output and calibration stability outweigh mobility considerations. Application demand spans oil and gas exploration, cargo and personnel security screening, academic and commercial research, as well as emerging medical and ancillary use cases. Regional consumption patterns reveal distinct maturity curves, with established industrial economies maintaining steady baseline procurement while high-growth corridors accelerate adoption through infrastructure modernization and specialized manufacturing investments.
Because segmentation boundaries increasingly overlap—portable units supporting stationary laboratory workflows, multi-application platforms serving both security and industrial inspection, and cross-border procurement channels adapting to shifting regulatory environments—a superficial view of market shares obscures the real strategic calculus. Decision-makers require granular visibility into how type preferences correlate with application intensity, how regional procurement behaviors influence pricing elasticity, and where transitional demand is creating short-term supply constraints. These are precisely the analytical dimensions addressed in depth within our report, where segment-level interactions are mapped against operational cost structures, lead-time variability, and technology adoption curves.
Competitive Landscape: Technology Differentiation and Strategic Positioning
The competitive arena features a blend of specialized technology manufacturers, established scientific instrumentation players, and research-driven innovators, each pursuing distinct value propositions and target ecosystems. Adelphi Technology, based in Redwood City, California, produces D-T (14.1 MeV), D-D (2.45 MeV), and moderated D-D thermal neutron generators tailored for industrial materials analysis, radiography, nondestructive testing, healthcare, and security applications. Sodern, headquartered in Bois-Guillaume, France, focuses on electric neutron sources and analyzers built around neutron activation principles, with particular emphasis on civil neutron tubes and generators for oil logging, waste characterization, and cross-belt analyzers used in cement, nickel, and copper processing.
Phoenix operates from Germany, supplying high-intensity neutron sources for nondestructive testing and neutron imaging across aerospace, defense, and industrial quality assurance applications. NSD Fusion / Gradel, also based in Germany, manufactures patented long-life neutron generators with operational lifetimes extending up to 20,000 hours, high specific power, and stable output suited to materials analysis, nondestructive testing, oilfield services, and security deployments. Thermo Fisher Scientific, located in Colorado Springs, Colorado, offers compact portable neutron generators such as the MP 320, P 385, and P 383, supporting elemental analysis, inelastic scattering, and both laboratory and field applications.
Recent procurement and product activity underscore how competitive dynamics are evolving in real time. Thermo Fisher Scientific integrated the Thermo Scientific Model D711 14 MeV neutron generator into new laboratory operating procedures to support student research, reflecting a broader institutional push toward accessible, education-aligned neutron capabilities. In early 2026, Uppsala University procured a 14 MeV deuterium-tritium neutron generator system model DT110.1gs for research facilities, while UKRI secured a contract for Neutron Generator Head model DT110.1gs delivery and installation, signaling sustained public-sector investment in advanced neutron infrastructure. Separately, the Hefei Comprehensive National Science Center advanced high-intensity compact D-D neutron generator technology, achieving stable yields up to 5 × 10^9 n/s with 98 percent effective operation time for neutron imaging, illustrating how regional research institutions are pushing performance thresholds that will eventually cascade into commercial specifications.
Market concentration remains moderately distributed, with the top three firms accounting for approximately 24.6 percent of collective revenue and the top five firms reaching about 32.1 percent. This fragmentation offers both opportunity and risk: new entrants and niche specialists can carve out defensible positions through application-specific engineering, while larger incumbents leverage scale, compliance infrastructure, and multi-product portfolios to consolidate share. Understanding which competitive levers are most effective in each segment—and where partnerships, licensing, or regional distribution agreements are reshaping market access—is essential for formulating durable growth strategies.
Regulatory and Geopolitical Dynamics Shaping Market Behavior
Neutron generator commercialization does not occur in a regulatory vacuum. Compliance requirements, export controls, and medical-device classification frameworks materially influence product design, sales cycles, and international market entry strategies. In the United States, electronic neutron generators are classified by the U.S. Nuclear Regulatory Commission as radiation-producing machines subject to Agreement State licensing rather than direct NRC jurisdiction. D-T neutron generators that incorporate tritium above specified activity thresholds require specific NRC or Agreement State tritium possession licenses, adding a compliance layer that affects manufacturing, handling, and end-user onboarding. High-performance neutron generators also fall under U.S. Export Administration Regulations, requiring individual validated export licenses for sales to restricted countries such as China and Russia, which directly shapes distribution planning and partner selection.
Medical applications introduce additional complexity. BNCT hospital-grade neutron generator systems are subject to Class III medical device approvals in the United States, CE Mark certification in Europe, and equivalent processes that require extensive clinical trial data. These approval pathways extend time-to-market and elevate validation costs, making early regulatory strategy a determinant of commercial viability rather than a downstream administrative step. On the international stage, neutron generators are classified as dual-use items under the Wassenaar Arrangement, subject to multilateral export licensing controls across 42 participating states including Europe, Japan, and Australia. For multinational enterprises, this means that even routine cross-border equipment transfers can trigger compliance reviews, delay project timelines, and require dedicated trade-compliance resources.
These regulatory and geopolitical factors are not peripheral concerns; they are structural inputs into pricing models, channel strategy, and risk-adjusted return calculations. Organizations that treat compliance as an afterthought often encounter costly rework, missed procurement windows, or restricted market access. By contrast, firms that integrate regulatory foresight into product architecture, supplier contracts, and international sales planning can convert compliance complexity into competitive differentiation.
What the Full Study Delivers: Operational Intelligence for 2026 Decision-Making
This market research is designed to move beyond top-line figures and provide the operational intelligence that executives need when allocating budgets, prioritizing R&D, or evaluating market-entry timing. The report covers historical performance baselines, multi-year forecast modeling, application-specific demand drivers, type-level technology maturity considerations, regional procurement behaviors, and competitive positioning across the principal market participants. It also maps regulatory touchpoints, export-control implications, and institutional procurement trends that directly affect go-to-market execution.
Neutron Generators Market
Beyond descriptive analysis, the study presents decision-oriented frameworks that help teams translate market signals into concrete actions. Readers will find structured assessments of where demand is most resilient, which technology pathways are gaining adoption momentum, how procurement timing varies across sectors, and what operational benchmarks matter most when comparing supplier offerings. The research is built to support capital planning, product strategy, sales segmentation, and risk evaluation, giving leadership teams a shared, evidence-based foundation for strategic discussion.
Because the market is evolving under the combined influence of technological advancement, regulatory change, and shifting industrial demand, partial data is rarely sufficient for high-stakes decisions. The complete report consolidates the full analytical architecture—forecast sensitivity considerations, segment correlation insights, competitive benchmark details, and procurement trend mapping—into a single resource that can be operationalized across business units.
Conclusion: Turning Market Visibility into Strategic Advantage
The 2026–2032 period will reward organizations that approach the neutron generators market with disciplined analysis, regulatory awareness, and a clear understanding of where technology, application demand, and competitive dynamics intersect. With sustained growth projected through the end of the decade, the strategic question is not whether the market will expand, but how enterprises will position themselves to capture value efficiently and responsibly. Detailed segmentation data, application-level growth trajectories, regional procurement patterns, and complete competitive benchmarks are developed in full within our comprehensive market study. For decision-makers who require precision intelligence to guide investment, product planning, and market strategy, the complete report provides the depth, structure, and forward-looking analysis needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Neutron Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Softeners Market to Reach $5,244M by 2032 at 6.85% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Global Water Softeners Market: Navigating Growth and Consolidation Through 2032
Executive Overview
Hard water remains a persistent challenge across residential, commercial, and industrial sectors, driving sustained demand for reliable softening solutions. As infrastructure ages, regulatory standards tighten, and end-user awareness of scale prevention and appliance longevity improves, the water softeners market has entered a phase of structural expansion. Our latest market research publication maps this trajectory with granular precision, offering decision-makers a clear lens into revenue flows, technological shifts, and competitive positioning. The study spans historical performance from 2020 through 2025 and extends a forward-looking forecast window from 2026 to 2032, anchored in a base year of 2025. By translating macro-level momentum into actionable strategic guidance, this intelligence serves as a critical reference point for capital allocation, product development, channel strategy, and partnership evaluation.
The market has demonstrated consistent upward movement over the past five years, with total revenue climbing from approximately 2500 million USD in 2020 to 3310 million USD in 2025. This growth trajectory reflects a combination of rising household penetration, industrial water treatment mandates, and renewed commercial facility upgrades. The forecast period projects continued expansion, with market valuation expected to reach 3649.48 million USD in 2026 and advance steadily toward 5244.0 million USD by 2032. Underlying this progression is a forecast CAGR of 6.85%, a rate that signals durable demand rather than transient spikes. For executives planning multi-year initiatives, this growth curve provides a reliable scaffold for scenario modeling, capacity planning, and market entry timing.
Growth Trajectory and Structural Drivers
The sustained expansion observed between 2020 and 2025 was not accidental. It emerged from a convergence of consumer priorities, operational cost pressures, and regional infrastructure modernization. As water quality concerns gained prominence, end-users increasingly recognized the long-term economic benefits of hardness mitigation, including reduced scale buildup, extended equipment lifespans, and improved cleaning efficiency. Residential adoption benefited from heightened awareness of household appliance protection and wellness-oriented purchasing behavior. Commercial operators integrated softening systems into facility management programs to stabilize maintenance costs and ensure consistent water quality across hospitality, healthcare, and multi-unit residential properties. Industrial users, meanwhile, continued to prioritize water treatment as a component of process reliability and compliance management.
Water Hardness Removal Market
Looking ahead to the 2026–2032 forecast window, several structural catalysts will shape the pace and composition of demand. Technological refinement in resin performance, brine management, and system automation is lowering total cost of ownership while improving user experience. Energy-conscious designs are aligning softening equipment with broader sustainability agendas, making water treatment investments more compatible with corporate environmental targets. Channel evolution is also accelerating, as direct-to-consumer models, specialized dealer networks, and integrated plumbing partnerships reshape how systems are specified, installed, and serviced. These dynamics create a market environment where growth is not merely a function of unit volume but also of value-added service, differentiation, and lifecycle management.
Forecast Window and Decision-Making Implications
The 2026–2032 forecast period is particularly significant for enterprises weighing expansion, product refresh cycles, or geographic diversification. The projected escalation from 3649.48 million USD in 2026 to 5244.0 million USD by 2032 underscores a market that is broadening in both scale and complexity. For manufacturers, this implies the need to balance volume growth with margin protection, especially as competitive intensity increases and consumer expectations around efficiency and ease of maintenance rise. For distributors and service providers, the forecast highlights opportunities in installation scale, remote monitoring, and preventive maintenance contracts. For investors and corporate development teams, the trajectory points to a sector where consolidation, brand positioning, and technology differentiation will increasingly determine which participants capture disproportionate share.
Strategic planning in this environment requires more than headline figures. Decision-makers need visibility into how demand fragments across application contexts, how system types evolve in response to regulatory and consumer preferences, and how regional markets diverge in purchasing behavior, infrastructure readiness, and competitive saturation. Our research is structured to deliver this multi-dimensional view without overwhelming stakeholders with undifferentiated data dumps. Instead, the report organizes findings around operational questions: where should new capacity be directed, which product architectures align with durable demand, and how should channel investments be prioritized to maximize return in a maturing landscape?
Competitive Landscape and Strategic Positioning
The market’s growth trajectory unfolds against a backdrop of concentrated yet dynamic competition. Aggregate market structure indicates meaningful consolidation, with the top three participants collectively accounting for approximately 65.4% of revenue and the top five reaching around 78.2%. This concentration signals that scale, brand equity, distribution reach, and service infrastructure remain decisive advantages. At the same time, differentiation is intensifying as companies compete on system architecture, ease of installation, certification claims, and residential or commercial-specific feature sets.
Several established players illustrate the strategic diversity shaping the sector. Culligan International, headquartered in Illinois, maintains a broad residential and commercial presence built around cation exchange resin technology for hardness reduction, leveraging a well-recognized brand and extensive service networks. A.O. Smith Corporation, based in Milwaukee, Wisconsin, focuses on residential PRO water softeners with energy-efficient single-tank designs, aligning product development with efficiency-conscious consumer expectations. Kinetico Incorporated, operating from Newbury, Ohio, differentiates through non-electric water softeners certified for reducing calcium and magnesium deposits, appealing to customers seeking mechanically robust, low-maintenance solutions. Hellenbrand, located in Waunakee, Wisconsin, supplies both residential and commercial systems, including the ProMate EcoMax series, reflecting a portfolio strategy that spans application segments while emphasizing performance and efficiency.
These profiles are not merely company summaries; they reveal how incumbents position themselves across the value chain. Some compete primarily on brand trust and service density. Others prioritize engineering trade-offs such as energy consumption, electrical dependency, or installation simplicity. Together, they define the competitive benchmarks against which new entrants, regional challengers, and product innovators must calibrate their strategies. The report examines these positioning patterns in detail, mapping how product portfolios, channel structures, and regional footprints interact to shape share dynamics and barrier-to-entry conditions.
Report Architecture and Operational Utility
This market research publication is designed for practical application rather than passive reference. It combines macro-level market sizing with structured segmentation analysis, allowing stakeholders to trace how overall revenue translates into distinct market pathways. The report examines the market by region, by type, and by application, providing a layered view of where demand concentrates, how system preferences diverge, and which segments exhibit the strongest momentum. Rather than presenting isolated percentages or fixed monetary values for each segment, the analysis emphasizes relative scale, ordering, and strategic context so that readers can interpret where opportunities and risks are most pronounced.
The study also integrates competitive profiling, market concentration metrics, and forward-looking scenario considerations to support strategic decision-making. Readers will find structured evaluations of how leading companies position their offerings, where service and distribution capabilities matter most, and which product categories are likely to see the most intense innovation pressure. The report further addresses the operational implications of market evolution, including installation and maintenance workflows, customer retention levers, and the role of certifications and performance claims in purchasing decisions.
Water Softeners Market
By organizing intelligence around both market structure and competitive behavior, the publication enables users to quickly narrow in on the questions most relevant to their function. Executives can use the findings to inform portfolio priorities and geographic focus. Product leaders can assess architectural trends and differentiate against established designs. Sales and channel teams can align go-to-market efforts with demand patterns and regional readiness. Corporate development teams can evaluate partnership targets, acquisition rationale, and consolidation pathways within a clearly defined concentration framework.
Strategic Takeaways for 2026 Planning
As organizations finalize 2026 strategies, the water softeners market presents a landscape defined by steady expansion, concentrated competition, and increasing emphasis on efficiency, service, and differentiation. Several strategic priorities emerge from this environment. First, growth planning should account for the market’s move from early adoption momentum toward more mature, service-driven demand patterns, where installation quality, maintenance reliability, and system longevity increasingly influence repeat purchasing and referrals. Second, competitive positioning will depend on clarity of product architecture and the ability to communicate tangible benefits around scale prevention, energy use, and operational convenience. Third, channel strategy must be calibrated to regional demand behavior and to the preferences of end-users who value either integrated service relationships or streamlined purchasing experiences.
The forecast period also implies that market participants will need to manage the tension between volume growth and margin discipline. As demand broadens and competition sharpens, pricing pressure may intensify in certain segments, making value-added services, differentiated features, and efficient supply chain execution essential to sustained profitability. Leaders should also monitor how certification standards, consumer education, and regulatory expectations evolve, since these factors can accelerate adoption in some contexts while reshaping specification requirements in others.
Conclusion
The global water softeners market is advancing along a clear growth path, supported by durable demand drivers and a competitive environment where scale and differentiation both matter. The 2026–2032 forecast window offers a practical planning horizon for organizations seeking to align product strategy, channel investments, and expansion decisions with market reality. Our full research publication expands on the macro trends outlined here, providing detailed segmentation analysis, competitive profiling, regional context, and forward-looking strategic guidance that together form a comprehensive decision-support toolkit.
To access the complete dataset, segment-level evaluation, company positioning detail, and scenario-ready market projections, we invite leaders to review the full Water Softeners Market report. The complete intelligence package is structured to support both immediate 2026 planning and multi-year strategic commitments, giving stakeholders the clarity required to act with confidence in a growing but increasingly competitive market.
For detailed analysis of this topic, please visit the official page: Water Softeners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Accounting Market Hits $2.6B in 2025, Projects 7.8% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the 2026 Decision-Maker: Why the Cloud Accounting Software Market Research Matters Now
The shift from on-premise ledgers to cloud-native financial ecosystems is no longer a question of if, but how fast and how intelligently enterprises can execute. As we move through 2026, finance leaders, procurement directors, and technology strategists are grappling with a market that has matured beyond simple digitization. It is now a competitive arena defined by AI-driven automation, regulatory tightening, and subscription economics that treat financial infrastructure as a continuous service rather than a one-time capital expenditure. PW Consulting has just released a comprehensive market research study on the Cloud Accounting Software landscape, and this overview outlines why the findings should be central to your 2026–2032 planning cycle.
Online Accounting Software Market
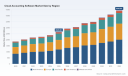
This research is not a static snapshot. It spans historical tracking from 2020 through 2025 and extends a six-year forecast horizon to 2032, giving decision-makers a longitudinal view of adoption curves, pricing shifts, and competitive repositioning. The overarching trajectory points to a compound annual growth rate of 7.8 percent, a figure that reflects sustained enterprise demand, expansion within small and mid-sized segments, and the accelerating migration away from legacy desktop systems. Total revenue measured in US dollars has grown from approximately 1,863 million in 2020 to roughly 2,645 million by 2025, and the forward curve projects continued expansion toward 4,440 million by 2032. These numbers are not just indicators of a healthy market; they are signals of structural change in how organizations manage cash flow, compliance, reporting, and financial collaboration.
Cloud Accounting Software Market
For 2026 decision-makers, the strategic value of this study lies in its ability to translate macro momentum into actionable positioning. The forecast period captures a window where platform differentiation is increasingly driven by embedded analytics, real-time bank connectivity, and ecosystem partnerships rather than core ledger functionality alone. Procurement teams can use the analysis to evaluate subscription models that align cost with actual usage, while finance transformation offices can leverage the competitive mapping to understand where consolidation pressure is building and where niche players are carving defensible territory. The research is structured to help executives move from broad market awareness to precise vendor evaluation, investment prioritization, and risk mitigation.
What the Report Delivers: From Market Architecture to Execution Playbooks
This study is designed as an operational intelligence asset, not a descriptive summary. It unpacks the cloud accounting software market across multiple dimensions so that strategy, product, and finance leaders can pressure-test their assumptions against documented trends and forward-looking scenarios. The analytical framework covers market sizing, segmentation behavior, concentration dynamics, regulatory catalysts, and the strategic moves of leading vendors. Each section is written with the explicit goal of supporting decision-making in budgeting, vendor selection, partnership evaluation, and internal capability roadmapping.
Readers will find a detailed breakdown of how the market is structured across deployment and service models, including the dominance of SaaS-oriented delivery and the continued role of alternative licensing arrangements. The report examines how organizations of different scales are absorbing cloud accounting tools, with particular attention to how small and mid-sized enterprises are driving volume growth while larger enterprises are expanding their footprint through ERP-integrated financial modules. Regional performance is also mapped, highlighting where adoption is most advanced, where growth is accelerating, and what local compliance or data-residency considerations are shaping deployment choices. These structural insights are essential for anyone allocating budget across geographies or deciding whether to standardize globally or adapt locally.
Beyond segmentation, the research provides a rigorously documented competitive landscape. It profiles the companies that are defining product direction, pricing strategy, and ecosystem integration in cloud accounting. The analysis goes beyond feature checklists to evaluate how each player is positioning against substitutes, where they are leaning into automation and advisory capabilities, and how recent corporate actions are reshaping the market’s center of gravity. This section is especially valuable for procurement and vendor management teams that need to understand not just what a platform can do today, but how a vendor’s roadmap and partnerships may alter total cost of ownership, integration burden, and long-term strategic fit.
The report also integrates the operational realities that influence adoption and retention. These include pay-as-you-go subscription dynamics that reduce upfront licensing friction, the importance of regional data storage options in meeting evolving privacy expectations, and the growing necessity of real-time regulatory monitoring to avoid compounding compliance penalties. By connecting market behavior with practical operational levers, the study helps leaders evaluate cloud accounting investments through a total-value lens rather than a narrow price-per-user comparison.
Competitive Landscape: Who Is Shaping the Market and How
The cloud accounting software space is defined by a concentrated group of incumbents and a long tail of specialized challengers. The research highlights a market environment in which the top three players account for roughly 58.5 percent of revenue and the top five extend that share to about 72.4 percent. This level of concentration indicates that scale, brand trust, and ecosystem breadth still matter enormously, but it also leaves meaningful room for differentiated offerings in specific segments, regions, and use cases. Understanding this concentration dynamic is critical for 2026 planning, because it informs both bargaining power in procurement negotiations and the likelihood of platform consolidation.
Several established vendors anchor the market with distinct strategic identities. Intuit continues to leverage QuickBooks Online as a leading cloud accounting solution for small to mid-sized businesses, with a strong emphasis on automated invoicing, expense tracking, and AI-powered insights. Xero has built its position around a cloud-native platform for small businesses and accounting firms, focusing on real-time collaboration, bank feeds, and invoice automation. Sage offers a broader range of options through Sage 50 Cloud and Sage Intacct, extending from small business accounting to enterprise-grade finance management, including budgeting, inventory, and compliance tools. Oracle remains relevant through Oracle NetSuite, which serves mid-market to large enterprise customers with ERP-integrated cloud accounting, advanced reporting, and inventory capabilities. These four names illustrate the breadth of the incumbent base and the different ways vendors are approaching scale, verticalization, and platform integration.
The competitive field also includes vendors with sharp positioning in specific audiences or geographies. FreshBooks is tailored to service-based small businesses, combining invoicing, time tracking, and client portals in a cloud-based workflow. Zoho Books targets startups and small teams with affordable cloud accounting that integrates CRM, inventory management, and multi-currency support. Wave provides a free-to-start entry point for microbusinesses, offering invoicing, expense tracking, and payroll integration as an accessible on-ramp to digital finance. Acumatica positions itself as a cloud ERP accounting platform for growing mid-sized businesses, adding supply chain and financial management depth. MYOB remains closely associated with small to medium businesses in Australia and New Zealand, emphasizing localized tax and compliance features. Together, these profiles demonstrate that cloud accounting is not a one-size market; it is a layered ecosystem where vendor fit depends heavily on company size, industry, geography, and operational complexity.
Recent corporate actions further illustrate how competition is intensifying around analytics, automation, and ecosystem reach. In March 2025, Intuit launched QuickBooks Cloud Plus with advanced AI-driven analytics for real-time financial insights and automated compliance alerts, signaling a push toward advisory-grade functionality. In February 2025, Xero acquired Fathom, a financial analysis and reporting platform, to strengthen its analytics and value-added services. Later in 2025, Xero partnered with Stripe to embed payables and receivables automation inside the accounting platform for faster cash flow, illustrating a broader trend toward embedded financial operations. In April 2025, Sage partnered with Microsoft Azure to develop a hybrid cloud accounting platform for large enterprises, highlighting the continuing relevance of infrastructure partnerships in enterprise deployments. These moves matter because they show vendors competing not only on core ledger accuracy but also on the speed, intelligence, and integration depth that finance teams increasingly expect.
Market Dynamics: Regulations, Economics, and the 2026 Compliance Imperative
Strategic planning for cloud accounting in 2026 cannot be separated from the regulatory and economic environment shaping deployment decisions. One of the most consequential developments is the AML/CTF Tranche 2 requirement, effective from July 2026, which requires accounting firms to implement demonstrable access controls for data privacy compliance in cloud accounting platforms. This creates a tangible compliance burden that interacts directly with vendor selection, because access control capabilities, auditability, and role-based permissions are becoming procurement criteria rather than optional features. For firms operating across multiple entities or jurisdictions, the ability to prove control maturity is now part of the operational contract with any cloud financial system.
Accounting standards are also evolving in ways that affect how organizations assess and expense cloud-based financial technology. ASU 2025-06, effective for fiscal years beginning after December 15, 2027, modernizes accounting for internal-use software to align with agile development practices. While this change is not limited to cloud accounting, it influences how enterprises treat implementation, customization, and continuous improvement investments in cloud financial systems. Decision-makers should anticipate that capital-versus-expense treatment, internal reporting, and project governance may shift as organizations adopt more iterative deployment models rather than large, fixed-scope implementations.
Beyond regulation, the economic structure of cloud accounting continues to reshape how organizations justify adoption. Pay-as-you-go subscription models reduce upfront licensing fees and align costs with actual usage, which is especially attractive for small businesses that need predictable cash flow management. At the same time, the stakes of non-compliance are rising in practical terms. Sales tax compliance in cloud accounting requires real-time regulatory monitoring across jurisdictions to avoid average annual penalty costs that can reach approximately 47,000 dollars. This figure underscores why automation, jurisdiction-aware rule sets, and strong integration with transaction data are becoming central value drivers rather than peripheral conveniences.
Data privacy considerations add another layer of complexity. Cloud accounting platforms increasingly offer data storage options within the United States or Europe to support evolving global privacy laws and compliance expectations. For multinational organizations and service providers handling client data, these options are not just technical details; they are enablers of trust, audit readiness, and cross-border operational continuity. The 2026 planner must therefore evaluate cloud accounting solutions not only on functionality and price, but also on where data resides, how access is governed, and how quickly the platform can adapt to new regulatory requirements.
Why This Research Should Anchor Your 2026 Strategy
The Cloud Accounting Software Market research is built for leaders who need to convert market momentum into informed decisions. It provides the structural context to understand where growth is coming from, the competitive intelligence to evaluate vendor stability and differentiation, and the operational framing to connect platforms with compliance, cost, and data governance requirements. In a market moving at a 7.8 percent compound annual growth pace and approaching nearly 4.4 billion dollars by 2032, the margin between reactive procurement and strategic deployment is widening. Organizations that map their cloud accounting decisions to documented market behavior will be better positioned to manage risk, control total cost of ownership, and align financial systems with broader transformation goals.
The full report goes further than this overview can. It contains the detailed segmentation analysis, regional performance patterns, application-level adoption behavior, and vendor-by-vendor strategic assessments that executives need to justify investment, negotiate with vendors, and prioritize implementation roadmaps. If you are planning cloud accounting adoption, renewal, replacement, or integration in 2026, this study is designed to serve as a decision-grade reference rather than a high-level introduction.
To access the complete market sizing, forecasting tables, competitive profiles, and the full set of dynamics shaping the next six years, visit the source page for the PW Consulting Cloud Accounting Software Market research. The full intelligence package is available there for teams that need to move from strategic awareness to execution-ready clarity.
For detailed analysis of this topic, please visit the official page: Cloud Accounting Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Contact Lens Solution Market Hits $2.2B in 2025, Nears $2.9B by 2032
By pmarketresearch, 2026-09-15
Strategic Horizons 2026: Navigating Growth and Consolidation in the Global Contact Lens Solution Market
Executive Preview
The contact lens solution market stands at a pivotal juncture as we move through 2026, characterized by steady quantitative expansion and an increasingly complex competitive architecture. Recent comprehensive analysis from PW Consulting indicates that the global market, estimated at USD 2,200 Million in 2025, is projected to reach approximately USD 2,900 Million by 2032. This trajectory reflects a compound annual growth rate of 4.5 percent over the forecast period, signaling a resilient industry ecosystem that continues to attract strategic investment despite macroeconomic headwinds and evolving regulatory frameworks.
For executives, product managers, and commercial strategists, these aggregate figures represent more than baseline growth. They encapsulate shifting consumer preferences, the maturation of silicone hydrogel adoption, persistent emphasis on ocular health and hygiene, and the strategic importance of formulation innovation. The current market landscape is shaped by a historical progression from USD 1,850.0 Million in 2020 through successive annual expansions, reaching USD 2,104.55 Million in 2024 and crossing the USD 2,200.0 Million threshold in 2025. This consistent upward momentum provides a reliable foundation for demand forecasting, capacity planning, and portfolio optimization.
Our freshly published Contact Lens Solution Market research offers an actionable, data-rich roadmap tailored for 2026 decision-making. It moves beyond surface-level narratives to deliver granular demand patterns, competitive benchmarking, regulatory touchpoints, and scenario-based projections that enable organizations to align their go-to-market strategies with realistic commercial pathways. The following overview highlights the strategic architecture of the study while preserving the detailed segmentation intelligence that readers can access through the complete report.
Macro Trajectory and Forecasting Architecture
The projected growth pattern from 2026 through 2032 illustrates a market that is expanding in size while simultaneously experiencing subtle cyclical adjustments and regional recalibration. Following the 2025 baseline of USD 2,200.0 Million, the forecast indicates market expansion to approximately USD 2,324.99 Million in 2026, advancing to USD 2,476.25 Million in 2027 and USD 2,579.58 Million in 2028. A modest consolidation phase appears around 2029, with values stabilizing near USD 2,558.63 Million before resuming growth toward USD 2,682.82 Million in 2030, USD 2,728.37 Million in 2031, and the terminal forecast figure of USD 2,900.0 Million in 2032.
This ebb-and-flow structure is not an anomaly; it reflects the integration of demand saturation in mature channels, distribution recalibration, product cycle timing, and the lag effects of regulatory or raw material fluctuations. Decision-makers who rely on linear extrapolations risk misallocating resources or underestimating the strategic value of timing-specific interventions. Our forecasting framework incorporates historical continuity from 2020 through 2025, ensuring that short-term operational plans are anchored in empirically observed performance rather than speculative optimism.
Strategic Segmentation and Commercial Implications
A central pillar of this research is its segmentation architecture, which enables companies to isolate high-potential avenues without losing sight of the broader market system. The analysis evaluates demand distribution across application types, formulation categories, and geographical footprint, offering a structured lens through which to prioritize product development, sales force deployment, and packaging strategy.
Within application-driven demand, the study examines how rinsing, cleaning, and disinfecting functions interact with lens material evolution, wearer compliance behavior, and professional recommendations from optometrists and ophthalmologists. Rather than presenting static percentages, the report explores the relative commercial weight of each function, the operational implications for manufacturing and fill-finish processes, and the consumer education dynamics that influence repeat purchase frequency. These insights are critical for organizations seeking to position formulations that balance convenience with clinical trust.
The type-based evaluation provides a parallel view of competitive differentiation across multi-purpose systems, hydrogen peroxide-based formulations, and complementary categories. Each type carries distinct value propositions, stability considerations, packaging constraints, and user-experience expectations. By examining how these categories perform in practical usage environments and how they align with evolving lens material compatibility, the research helps stakeholders determine where incremental innovation can generate disproportionate returns and where commoditization risks may require defensive pricing or service-based differentiation.
Geographically, the report maps the global landscape through a functional distribution lens that highlights the operational characteristics of major regional markets. Instead of reducing complex trade dynamics to simplistic regional rankings, the analysis explores market penetration patterns, channel maturity, retail and pharmacy influence, and the role of local regulatory expectations in shaping product availability. This enables enterprises to identify where near-term volume capture is achievable versus where longer-term brand-building and distribution partnership strategies will yield more sustainable outcomes.
Competitive Dynamics and Enterprise Positioning
The contact lens solution sector remains notably concentrated, with the top three enterprises collectively representing approximately 65 percent of market revenue and the top five firms accounting for around 75 percent. Such concentration intensifies the strategic stakes for both incumbents and challengers. Established players must defend share through continuous formulation enhancement, brand reinforcement, and channel efficiency, while emerging or niche participants need clear differentiation vectors to gain retailer trust and professional endorsement.
Contact Lenses Market
The competitive landscape examined in this study features organizations with distinct operational identities and strategic priorities. Bausch + Lomb Incorporated, headquartered in Rochester, NY, maintains a strong presence through its multi-purpose portfolios, emphasizing hydration, cleaning, and disinfection attributes that align with mainstream wearer routines. Alcon Inc., based in Fort Worth, TX, leverages its solution lines to address disinfection performance, protein removal, and all-day comfort, reinforcing clinical credibility alongside consumer convenience. CooperVision, Inc., operating from New York, NY, supports both soft and rigid lens care through multipurpose and peroxide system offerings, reflecting the importance of lens-type compatibility in product strategy.
International players contribute further dimensionality to the market structure. Menicon Co., Ltd., located in Nagoya, Japan, supports silicone hydrogel and rigid gas permeable lens ecosystems, highlighting the importance of material-specific formulation expertise. Contamac Holdings Limited, based in London, UK, specializes in lens materials and multipurpose or peroxide solutions for GP, scleral, and hybrid lenses, positioning itself within specialized care segments. Oté Pharma Sol B.V., from Uden, Netherlands, emphasizes preservative-free and peroxide-based options for soft and RGP lenses, reflecting demand for gentler formulation profiles. OPHTECS Corp., headquartered in Tokyo, Japan, advances innovative care solutions that span multipurpose and specialized formulations, underscoring the continued relevance of product differentiation in a crowded category.
Beyond the incumbents, recent industry activity illustrates how regulatory milestones and product innovation continuously reshape commercial expectations. In December 2025, Bruno Vision Care LLC received FDA clearance for the first EDOF daily disposable contact lens incorporating extended depth of focus optics. While this development directly concerns lens hardware, it signals broader momentum in vision correction technology and reinforces the strategic interdependence between lens design, wearer demographics, and care solution requirements. As lens formats evolve, solution providers must anticipate compatibility demands, consumer education needs, and packaging or instructional adjustments.
Regulatory, Raw Material, and Reimbursement Considerations
Market performance in this category is heavily mediated by regulatory expectations, formulation governance, and reimbursement accessibility. Contact lens solutions are regulated as Class II FDA devices, requiring 510(k) clearance and sterility testing per USP <71>. Compliance with 21 CFR § 800.12 for tamper-resistant packaging and labeling adds another operational layer, while any significant design or formulation change triggers the need for updated 510(k) notifications. These requirements shape development timelines, cost structures, and the agility with which companies can launch iterative improvements.
Formulation integrity also depends on the careful selection and control of standard ingredients such as preservatives, wetting agents, disinfectants, and humectants. These components must ensure sterility, compatibility with diverse lens materials, and consistent user experience. Supply chain resilience, vendor qualification, and quality assurance protocols therefore become strategic assets rather than routine procurement matters. Any disruption in raw material availability or qualification standards can affect fill rates, regional availability, and time-to-market for reformulated offerings.
On the consumer side, reimbursement accessibility through Health FSA and FSA accounts when purchased for vision care treatment influences purchase behavior and channel selection. This financial mechanism can enhance affordability and encourage consistent replenishment, particularly in markets where out-of-pocket sensitivity is high. However, it also requires clear documentation, retail enrollment support, and consumer communication strategies that convert reimbursement eligibility into tangible repeat purchase behavior. The study incorporates these factors into a broader examination of demand durability and channel economics.
Contact Lens Solution Market
Report Contents and Decision-Ready Framework
The complete report is designed to support cross-functional planning with practical, implementation-focused content. It provides:
- A full market size and forecast model spanning the historical period and the 2026-2032 outlook, structured for scenario testing and revenue planning
- Segment-level evaluation across application functions, formulation types, and regional distribution patterns to guide portfolio prioritization
- Competitive profiling of key market participants, with attention to product architectures, strategic emphasis, and positioning logic
- Analysis of regulatory requirements, formulation ingredients, packaging constraints, and reimbursement dynamics that affect commercial execution
- Exploration of demand drivers, distribution channel behavior, professional endorsement influence, and consumer compliance patterns
- Identification of near-term opportunities and risk factors that can affect production planning, pricing strategy, and market entry timing
To maintain the depth and integrity of the analysis, detailed regional values, application-level revenue breakdowns, and type-specific market shares are provided within the full report rather than in this overview. This approach preserves the strategic narrative while ensuring that precise figures remain accessible to stakeholders who require them for internal modeling, investment justification, and operational planning.
Strategic Takeaways for 2026
As organizations prepare for the remainder of 2026 and look toward the end of the decade, several strategic imperatives emerge from the market structure. First, growth is real but must be managed with discipline, given the concentration of revenue among leading firms and the cyclical nature of the forecast curve. Second, differentiation increasingly depends on formulation credibility, lens compatibility, packaging reliability, and consumer education rather than price competition alone. Third, regulatory compliance and quality assurance are not overhead items but core strategic capabilities that influence speed, cost, and market access. Fourth, reimbursement frameworks and channel dynamics can materially affect repeat purchase behavior and should be integrated into commercial planning.
The Contact Lens Solution Market research from PW Consulting equips leaders with the intelligence required to navigate these complexities. By combining historical continuity, forecast discipline, segmentation clarity, and competitive context, the study supports more confident decisions around product focus, geographic prioritization, partner selection, and capacity alignment. The full report contains the precise figures, segmentation resolution, and comparative detail needed for rigorous internal analysis and executive-level strategy development.
For detailed analysis of this topic, please visit the official page: Contact Lens Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting BMS Report: Market Hits $13.64B in 2025, Forecasts 15.55% CAGR to $37.51B by 2032
By pmarketresearch, 2026-09-15
Powering the Future: Strategic Intelligence for the Battery Management System Market 2026-2032
Introduction: The Critical Role of BMS in a Decarbonizing World
The global transition toward electrification and renewable energy integration is no longer a speculative forecast; it is an operational reality reshaping industrial landscapes. At the heart of this transformation lies the Battery Management System (BMS), the critical electronic brain that ensures safety, performance, and longevity across lithium-ion and emerging battery chemistries. As enterprises navigate the complexities of 2026, understanding the trajectory of the BMS market is not merely an academic exercise but a strategic imperative.
PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip decision-makers with the granular intelligence required to capitalize on emerging opportunities. This report serves as a definitive guide through the rapidly evolving ecosystem of battery management technologies, offering a clear view of where value is being created and where risks are accumulating. The following insights provide a preview of the strategic depth contained within our full analysis.
Market Trajectory: Scale and Growth Dynamics
The momentum behind the BMS sector is underpinned by robust historical performance and an aggressive growth forecast. Our analysis tracks revenue developments from 2020 through the base year of 2025, establishing a solid foundation for forward-looking projections. In 2020, the global market generated approximately 8.6 billion USD. By 2025, this figure had climbed to 13.64 billion USD, reflecting a compound annual growth trajectory that underscores the accelerating adoption of battery-dependent technologies.
Looking ahead to the forecast period spanning 2026 to 2032, the market is projected to reach 37.51 billion USD. This expansion represents a sustained CAGR of 15.55 percent, signaling that demand drivers are not transient but structural. Such growth rates indicate a market that is maturing yet still expanding rapidly, driven by the dual engines of electric mobility and stationary energy storage. For stakeholders, this trajectory suggests that timing investments correctly will be crucial, as the window to establish competitive positioning before market saturation in certain segments begins to narrow is OPEN.
Building Energy Management System (BEMS) Market
It is important to note that while top-line growth is impressive, the distribution of value across different technological and application layers varies significantly. Our full report dissects these layers to reveal where the highest margins and fastest adoption rates are concentrated, allowing clients to prioritize resources effectively.
Segmentation Insights: Technology, Application, and Regional Nuances
To navigate this market successfully, one must understand the interplay between chemistry types, end-use applications, and geographic dynamics. The report provides a detailed breakdown of the market by technology, distinguishing between Lithium-ion and Lead-acid systems, alongside emerging alternatives. While Lithium-ion continues to dominate due to its energy density and declining cost profiles, specific industrial and legacy applications still rely heavily on established chemistries. Understanding the shifting balance between these types is essential for suppliers manufacturing components or integrators designing systems.
Similarly, the application landscape is diverse. Electric Vehicles (EVs) remain a primary growth vector, but Energy Storage Systems (ESS) and consumer electronics also contribute substantial revenue streams. Each application imposes unique requirements on BMS functionality, ranging from high-current handling in industrial settings to precise communication protocols in solar-plus-storage configurations. Our analysis maps these requirements against current supply capabilities to identify gaps and opportunities.
Geographically, the market exhibits distinct characteristics. While North America and Europe maintain significant shares driven by regulatory mandates and established automotive sectors, the Asia Pacific region represents a massive volume center. Latin America and the Middle East and Africa are emerging as niche but strategically important markets for specific storage and mobility solutions. The full report avoids generic regional summaries, instead providing context on trade flows, local manufacturing capabilities, and regulatory influences that impact market accessibility in each zone.
Competitive Landscape: Key Players and Strategic Moves
The BMS market is characterized by a mix of specialized manufacturers, integrated energy companies, and engineering firms offering custom solutions. Market concentration metrics indicate a CR3 of 25 percent and a CR5 of 35 percent, suggesting that while leading players hold significant influence, the market remains fragmented enough for agile competitors to carve out niches. Success in this environment depends on differentiation through technology, reliability, and ecosystem integration.
Several key companies define the current competitive contours. Daly BMS, based in China, has strengthened its position through continuous product innovation, recently launching a 4th Generation Home Energy Storage BMS with WiFi and Bluetooth connectivity to enhance user monitoring and app integration. Further expanding its ecosystem, Daly announced a new 500W Portable Charger in 2026, demonstrating a strategy to bundle charging solutions with BMS-integrated systems.
In the custom solutions space, Kuruibms has focused on C&I energy storage and EV applications, releasing a market guide in 2026 highlighting top BMS factories to assist buyers in navigating the supply chain. Victron Energy, headquartered in the Netherlands, continues to refine its VE.Bus and Lynx Smart BMS models, updating documentation in early 2026 to ensure compatibility with multiplus inverters and broader energy storage architectures. These updates reflect an industry-wide push toward seamless interoperability between BMS units and inverters.
Battery Management System (BMS) Market
North American and European players are also active. UgoWork in Canada emphasizes safety and fleet deployment by integrating UL 1998 certified BMS with lithium-ion batteries for material handling. Novelic in France designs comprehensive BMS for e-mobility, integrating monitoring and cooling. In Germany, comemso electronics provides critical testing and simulation tools that allow other manufacturers to optimize balancing algorithms, indirectly shaping the quality of BMS deployed in EVs. Meanwhile, Nuvation Engineering and Elithion Inc. in the United States offer custom and embedded BMS solutions for industrial and automotive integration, catering to clients requiring tailored specifications.
Recent industry developments also highlight the importance of ecosystem compatibility. For instance, Sol-Ark issued a battery integration guide in 2026 confirming support for various BMS-equipped storage partners, illustrating how inverter manufacturers are increasingly vetting and aligning with specific BMS providers to reduce integration friction for end users. The full report analyzes these partnerships and product launches to determine which strategic alliances are likely to yield long-term market share gains.
Market Dynamics: Supply Chain, Raw Materials, and Regulatory Pressures
Beyond company profiles and segmentation, the macro-environment plays a decisive role in shaping market outcomes. Raw material volatility remains a key concern for manufacturers and integrators. Spot lithium carbonate prices in China increased from approximately 9,300 USD per ton in January 2025 to 10,300 USD per ton by November 2025, driven by surging energy storage demand and mine disruptions. Similarly, Chinese lithium hydroxide prices rose from roughly 10,300 USD to 11,200 USD per ton over the same period. These movements impact bill-of-materials costs and can compress margins if not managed through strategic sourcing or hedging.
Conversely, the United States saw lithium carbonate annual average prices decline by 31 percent to 9,000 USD per ton in 2025 due to short-term oversupply, though battery-grade prices remain elevated year-over-year. This divergence creates complex arbitrage situations and supply chain decisions for global players. The report examines how these price dynamics influence regional manufacturing strategies and the competitiveness of localized production versus imports.
Regulatory shifts are equally impactful. China's policy of reducing VAT export rebates on lithium-ion batteries, effective from April 1, 2026, prompted a front-loading of production and exports, contributing to price volatility and altering trade flows. In Africa, Zimbabwe imposed a ban on exports of all raw minerals, including lithium concentrate, effective February 2026, further tightening global supply. These regulatory actions underscore the geopolitical risks inherent in the battery supply chain. Our analysis provides scenario planning tools to help clients assess exposure to trade policy changes and raw material restrictions.
Report Contents: Operational Intelligence for Decision Makers
This market research is structured to deliver actionable intelligence rather than abstract data. The full document includes detailed profiles of key companies, analyzing their product portfolios, recent developments, and strategic positioning. We provide a comprehensive segmentation analysis that breaks down revenue and volume by type, application, and region, enabling clients to benchmark their performance against market averages.
The report also features a deep dive into market dynamics, covering drivers, restraints, and opportunities. We examine the impact of raw material price fluctuations, regulatory changes, and technological advancements on market growth. Additionally, the study offers strategic recommendations for various stakeholder groups, including manufacturers, investors, and end-users. These recommendations are grounded in data-driven forecasts and competitive analysis, ensuring that decisions are informed by the latest market realities.
Readers will also find historical data from 2020 to 2025, providing context for current trends, alongside forecast data extending to 2032. This long-term view allows organizations to plan capital expenditures, R&D investments, and market entry strategies with confidence. The inclusion of recent product launches, market guides, and compatibility updates ensures that the analysis reflects the most current state of the industry.
Conclusion: Navigating the Next Wave of Growth
The Battery Management System market stands at a pivotal juncture. With a projected revenue of 37.51 billion USD by 2032 and a CAGR of 15.55 percent, the sector offers substantial opportunities for those who can navigate its complexities. However, success requires more than just observing growth trends; it demands a nuanced understanding of competitive dynamics, supply chain vulnerabilities, and regional regulatory environments.
PW Consulting's comprehensive report provides the depth and clarity needed to make informed strategic decisions. By uncovering hidden patterns in segmentation, evaluating the impact of recent industry developments, and modeling future scenarios, this research empowers organizations to stay ahead of the curve. We invite you to access the full report to gain the complete intelligence picture and leverage these insights for your 2026 planning and beyond. The future of energy storage and electric mobility depends on robust battery management; ensure your strategy is built on the best available data.
For detailed analysis of this topic, please visit the official page: Battery Management System (BMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plasma Sterilizer Market Hits $515M in 2025, Projected 6.1% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperative: Navigating the Plasma Sterilizers Market in 2026 and Beyond
The global healthcare infrastructure is undergoing a paradigm shift in infection control protocols, driven by increasing surgical volumes, stringent regulatory frameworks, and the critical need for sterilizing heat-sensitive medical instruments. For executives and strategic planners, understanding the trajectory of the Plasma Sterilizers Market is no longer optional; it is a fundamental component of capital allocation and risk management. This analysis draws from the comprehensive market intelligence provided in our latest research, offering a high-level view of the landscape while underscoring the necessity of granular data for precise decision-making in 2026.
Market Trajectory and Historical Performance
The plasma sterilization sector has demonstrated consistent resilience and growth over the past half-decade. Historical data from 2020 to 2025 indicates a mature yet expanding market, with revenue climbing from 350.0 million USD to 515.0 million USD. This upward trend reflects the steady adoption of low-temperature sterilization technologies in settings where steam autoclaving is ineffective.
Looking toward the forecast period spanning 2026 to 2032, the market is projected to continue its expansion. The compound annual growth rate (CAGR) is estimated at 6.1 percent. By 2032, overall market revenue is anticipated to reach 775.43 million USD. These figures suggest a stable growth environment, though they mask the underlying volatility and opportunity pockets that exist within specific segments. For a business leader, knowing the aggregate number is the starting point; understanding the drivers behind the variance between 2026 and 2032 is where strategic advantage is found.
The 2026 Decision Matrix: Why Deep Intelligence Matters
As organizations plan their operational roadmaps for 2026, relying on top-line market figures is insufficient. The market is characterized by distinct technological preferences, regional disparities, and application-specific demands that aggregate data cannot reveal. The following sections outline the critical dimensions where detailed intelligence transforms vague strategy into actionable execution.
Technological Segmentation and Device Form Factors
The market is divided into distinct product categories, each serving different clinical and operational needs. Floor-standing units represent a significant portion of the market value, catering to large hospitals and central sterilization departments that require high throughput. However, the rise of portable and table-top plasma sterilizers indicates a shifting trend toward point-of-care sterilization and decentralized processing.
Our report dissects these categories to reveal which form factors are gaining traction in specific clinical settings. For procurement managers, the choice between a floor-standing system and a portable unit involves trade-offs regarding capital expenditure, maintenance logistics, and workflow integration. Understanding the revenue split and growth velocity of each type allows organizations to align their procurement strategies with actual utilization rates rather than legacy habits. The data suggests that while larger systems dominate current revenue, the flexibility of smaller units is driving incremental adoption in specialized clinics and veterinary practices.
Application Diversity: Hospitals and Manufacturing
Demand is not monolithic across end-users. Hospitals remain the primary consumers of plasma sterilization technology, driven by the need to process complex surgical instruments and implantable devices. However, the pharmaceutical and medical device manufacturing sectors represent a high-value secondary market. In these environments, sterilization is critical for ensuring product safety and compliance with good manufacturing practices (GMP).
Plasma Sterilizers Market
The research provides a detailed breakdown of how demand is distributed across these applications. For manufacturers, the opportunity lies in integrating sterilization validation into the product development lifecycle. For healthcare providers, the focus is on throughput and compatibility with diverse instrument sets. The report examines the specific revenue contributions of hospitals versus manufacturing sectors, highlighting where the highest margin opportunities and volume demands reside. Ignoring the nuance between these application fields can lead to misaligned product positioning or failed market entry strategies.
Regional Dynamics and Global Distribution
Geography plays a pivotal role in market accessibility and growth potential. While North America has historically maintained a dominant position in terms of revenue generation, other regions are exhibiting evolving maturity levels. Europe holds a substantial share, reflecting strong healthcare infrastructure and regulatory compliance standards. Meanwhile, the Asia Pacific region presents a different growth profile, often characterized by increasing healthcare expenditure and expanding hospital networks.
Latin America and the Middle East and Africa constitute smaller portions of the global revenue base but offer emerging opportunities as healthcare systems modernize. Our analysis avoids generic regional generalizations. Instead, it provides specific insights into which regions are driving volume versus value. For international players, knowing where the revenue is concentrated helps in prioritizing distribution channels and regulatory approvals. For instance, a strategy focused on high-volume, low-cost units might target different regions compared to a strategy focused on premium, high-throughput systems. The full report details the specific revenue magnitudes for each region, enabling a precise geographic prioritization matrix.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with a significant portion of revenue held by leading players. The competition is defined not just by market share but by technological innovation, regulatory clearance, and specific product differentiation. Understanding the moves made by key competitors is essential for anticipating market shifts and identifying gaps in the offering.
Key Market Participants
Several companies define the current competitive landscape, each with distinct strategic focuses:
- Tuttnauer , headquartered in Breda, Netherlands, is known for producing the PlazMax line of low-temperature hydrogen peroxide plasma sterilizers. Their focus remains on instruments that are sensitive to heat and moisture, positioning their technology as a reliable solution for general medical instrument sterilization.
- Advanced Sterilization Products (ASP) , based in Irvine, California, continues to be a pivotal player with its STERRAD 100NX Sterilizer featuring ALLClear Technology. This platform is widely recognized for low-temperature hydrogen peroxide gas plasma sterilization.
- Plasmapp , from Seoul, South Korea, markets the STERLINK medical cryo plasma sterilizer. With FDA clearance for units under 20 L capacity, they target specific niches requiring compact, low-temperature sterilization solutions.
- Steris Corporation , located in Warrendale, Pennsylvania, offers V-PRO low-temperature plasma sterilization systems. Their portfolio is heavily integrated into the broader medical device and hospital sterilization ecosystem.
- VetOvation , operating in the United States, provides Sterlink gas plasma sterilizers specifically tailored for veterinary hospital applications, highlighting a specialized vertical within the broader market.
Recent Developments and Regulatory Shifts
The competitive environment is dynamically influenced by regulatory clearances and technological updates. In April 2025, Advanced Sterilization Products Inc. received FDA 510(k) Clearance for the STERRAD 100NX Sterilizer with ALLClear Technology (K250802). This clearance validates the use of hydrogen peroxide gas plasma sterilization for a broad range of medical instruments, reinforcing the platform's compliance standing.
Furthermore, in August 2024, ASP collaborated with PENTAX Medical to secure FDA clearance for the ULTRA GI Cycle. This cycle is designed for use in the STERRAD 100NX Sterilizer with ALLClear Technology specifically for duodenoscope reprocessing. This development underscores the importance of specialized cycles for complex devices like duodenoscopes, where infection control is critical. Similarly, PENTAX Medical received FDA clearance in August 2024 for the DEC Duodenoscope, which is compatible with the STERRAD 100NX Sterilizer plasma technology.
These events highlight a trend where regulatory approval is not just a one-time hurdle but an ongoing process of expanding indications and compatible device portfolios. For competitors and investors, tracking these clearances is vital for assessing the longevity and scope of competing platforms.
Regulatory and Reimbursement Dynamics
The operating environment for plasma sterilizers is heavily influenced by regulatory standards and institutional reimbursements. Recognition by major health bodies provides the foundational trust required for adoption. Hydrogen peroxide gas plasma sterilizers are recognized by the CDC and FDA as Established Category A low-temperature sterilization processes. This classification confirms their compatibility with heat- and moisture-sensitive medical devices, providing a regulatory seal of approval that drives procurement in regulated healthcare environments.
Additionally, the standardization of validation processes is tightening. The FDA has recognized ISO 22441:2022 as the standard for low-temperature vaporized hydrogen peroxide sterilization validation and routine control. Compliance with this standard is becoming a baseline expectation for manufacturers and users alike. Our report analyzes how these regulatory benchmarks impact market entry barriers and operational costs. Organizations must ensure their sterilization protocols align with these evolving standards to avoid compliance risks. The full intelligence provided in the study details how these regulations influence regional adoption rates and product design requirements.
Desktop Plasma Cleaner Market
Strategic Outlook for 2026
As the market moves through the forecast period, the convergence of technological maturity, regulatory enforcement, and healthcare expansion will define the growth trajectory. The projected revenue growth from 563.22 million USD in 2026 to 775.43 million USD in 2032 indicates a robust market potential. However, capturing this value requires more than observing the growth curve.
Strategic decisions in 2026 will hinge on understanding the interplay between product types, application needs, and regional readiness. For instance, the concentration of market share among top players suggests that partnership or niche specialization may be necessary for new entrants. The specific revenue contributions of regions like North America versus Asia Pacific will dictate where capital should be deployed for maximum return. Similarly, the divergence between hospital-based demand and manufacturing requirements necessitates tailored value propositions.
This overview provides a foundational understanding of the Plasma Sterilizers Market landscape. However, the true utility for strategic planning lies in the granular details that drive these aggregates. The exact revenue splits, the precise CAGR variations across segments, and the detailed competitive profiling contained in the full report are essential for building a resilient strategy.
To access the complete dataset, including specific regional revenue figures, detailed segmentation splits, and comprehensive company profiles with recent strategic developments, we invite you to secure the full market research report. In a market defined by 6.1 percent CAGR and evolving regulatory standards, the difference between average performance and market leadership often lies in the depth of intelligence available to decision-makers.
For detailed analysis of this topic, please visit the official page: Plasma Sterilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ESP Market Hits $8.3B in 2025, Projected $12.79B by 2032 at 6.4% CAGR
By pmarketresearch, 2026-09-15
Electrostatic Precipitators Market: Strategic Intelligence for the 2026–2032 Investment Horizon
As global industrial emissions face intensifying regulatory scrutiny and energy transition mandates, electrostatic precipitators (ESP) have evolved from conventional particulate control equipment to mission-critical infrastructure within the broader decarbonization and air quality compliance ecosystem. Our latest research publication, Electrostatic Precipitators (ESP) Market: Strategic Forecast & Competitive Intelligence 2026–2032 , delivers a rigorously modeled, commercially actionable assessment designed specifically for executive teams, capital allocators, and technology procurement leaders navigating the next multi-year cycle. This briefing outlines why this analysis is strategically indispensable for 2026 decision-making, what operational intelligence it provides, and how organizations can leverage its architecture to secure competitive advantage in a rapidly consolidating market.
Why This Research Matters for 2026 Decision-Making
Corporate strategy in environmental control technology is no longer driven by isolated compliance requirements; it is shaped by capital efficiency, supply chain localization, digital integration, and long-term asset lifecycle economics. The 2026–2032 period represents a structural inflection point where legacy ESP installations require modernization, new industrial capacity demands higher collection efficiencies, and regulatory frameworks tighten particulate emission thresholds across multiple jurisdictions. Organizations that enter this cycle with fragmented data or outdated cost assumptions risk misaligned procurement, suboptimal capacity planning, and exposure to margin compression.
Our report is engineered to close that intelligence gap. It translates historical trajectory, forward-looking growth signals, and competitive positioning into a decision-ready framework. By anchoring analysis in verified historical performance and modeling forward under multiple adoption scenarios, the study equips strategy, operations, and procurement teams with the visibility needed to time investments, evaluate supplier risk, and align technology roadmaps with corporate sustainability and compliance targets.
Market Trajectory and Forward-Looking Growth Signals
The ESP market has demonstrated consistent expansion across recent years, reflecting sustained industrial demand, upgrade cycles for existing installations, and the continued deployment of particulate control systems in power generation, heavy processing, and emerging waste-to-energy applications. The historical baseline from 2020 through 2025 shows a market that has steadily scaled, with revenue progressing from approximately USD 6.5 billion at the start of the period to roughly USD 8.3 billion by the base year. This progression underscores an entrenched demand environment rather than a transient compliance spike.
Worldwide Dry Electrostatic Precipitator Market
Forward momentum remains firmly positive. The forecast trajectory for 2026 projects revenue approaching USD 9.06 billion, followed by continued expansion through 2032, with the terminal year reaching approximately USD 12.79 billion. This path corresponds to a compound annual growth rate of 6.4 percent over the forecast window. Importantly, the growth curve is not uniform across all demand drivers; it reflects a combination of capacity additions, regulatory-driven retrofits, operator preferences for higher-efficiency configurations, and incremental adoption in sectors that previously relied on alternative filtration approaches. These dynamics create a multi-layered opportunity landscape where procurement timing, technology selection, and aftermarket service strategy materially influence total cost of ownership.
Strategic readers will note that the growth narrative is best understood not as a single-volume projection, but as a portfolio of application-specific demand pulses, regional deployment rhythms, and technology-specific replacement cycles. The full study decomposes these layers without exposing the granular splits prematurely, ensuring that interested stakeholders engage directly with the complete modeling architecture to extract the precise segmentation intelligence relevant to their operating footprint.
Market Structure, Competitive Dynamics, and Strategic Positioning
The ESP competitive environment is moderately concentrated, with the top three participants collectively accounting for approximately 38.2 percent of market revenue and the top five representing about 55.0 percent. This concentration indicates a market where scale, installed-base advantages, service network density, and proven high-efficiency collection capabilities create meaningful barriers for new entrants, while still leaving space for specialized manufacturers, regional integrators, and technology innovators to differentiate through application-specific engineering, digital control modules, and customized wet or dry ESP configurations.
Several established players illustrate the breadth of competitive strategies currently shaping the market. Babcock & Wilcox Enterprises, Inc. continues to reinforce its leadership position with an extensive installed base exceeding 5,000 systems worldwide and demonstrated high-efficiency collection performance up to 99.9 percent across wet and dry ESP platforms for utility and industrial power generation. In June 2025, the company secured more than USD 18 million in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, reaffirming the commercial importance of lifecycle rebuild programs alongside new equipment deliveries.
FLSmidth & Co. A/S has been advancing application-specific ESP solutions for cement and industrial environments, increasingly integrating AI-enhanced control systems to optimize collection performance and operational stability. In February 2025, the company expanded its service center network with a new facility in Dammam, Saudi Arabia, strengthening regional support for advanced emission control technologies, including electrostatic precipitators. This localized service expansion reflects a broader industry pattern: competitive advantage is increasingly determined by the proximity of technical support, parts availability, and predictive maintenance capabilities rather than equipment supply alone.
Valmet Oyj supplies ESP solutions tailored to pulp and paper recovery boilers, where process conditions demand robust particulate capture and integration with recovery cycles. In February 2024, the company shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler, with completion targeted by the end of 2025. Mitsubishi Heavy Industries, Ltd. has similarly extended its high-efficiency ESP footprint into large-scale industrial applications, including a September 2024 delivery of an ESP unit for a 700,000-tonne chemical pulp project in China. These engagements demonstrate how major suppliers are aligning ESP deployments with sector-specific process engineering rather than treating particulate control as a standalone commodity purchase.
Beyond these highlighted developments, the competitive field includes a broad set of specialists and industrial integrators. DÜRR AG emphasizes advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Ducon Technologies Inc. manufactures custom wet and dry ESP systems for power, cement, and steel applications. Fuel Tech, Inc. combines ESP with flue gas conditioning and NOx reduction technologies for coal-fired utilities. GEA Group AG manufactures ESP for food, pharmaceutical, and chemical industry environments. KC Cottrell, Inc. focuses on wet ESP for utility and industrial applications. Monroe Environmental, LLC provides industrial ESP solutions for air quality control. GEECO Enercon GmbH specializes in high-efficiency ESP systems for industrial and power sector emission control. Sumitomo Heavy Industries, Ltd. develops ESP integrated with flue gas treatment systems. Trion, Inc. targets commercial and industrial air filtration. Wood plc delivers ESP as part of broader power generation and environmental control system offerings.
This diversified competitive fabric matters strategically because procurement decisions increasingly weigh total value over nominal equipment price. Operators evaluate supplier track record in specific applications, availability of rebuild and upgrade programs, ability to integrate digital controls and flue gas conditioning, and capacity to support compliance with evolving emission limits. The comprehensive competitive section of our report maps these positioning dimensions across the profiled companies, enabling readers to benchmark capabilities, identify partnership or sourcing opportunities, and assess where consolidation, regional expansion, or technology differentiation is likely to reshape supplier relationships.
Structural Drivers and Operational Constraints Shaping Investment Logic
Market growth is reinforced by a combination of regulatory pressure, process modernization, and operational reliability requirements. In the United States, the EPA Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, directly accelerating ESP deployment and upgrade activity in utility environments. Alongside this, U.S. federal regulations on particulate matter emissions from industrial sources continue to compel industries to adopt ESP technologies for compliance, expanding the addressable base beyond traditional power generation.
These regulatory tailwinds interact with practical operational considerations. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment, elevating the importance of lifecycle economics and financing strategy. Electrical energy consumption in electrostatic precipitators can be substantial, with resulting high operating costs for large-scale installations, making energy-efficient design, optimized voltage control, and intelligent operational scheduling relevant to long-term profitability. Together, these factors mean that market participants cannot evaluate ESP investments purely on collection efficiency metrics; they must incorporate compliance risk reduction, maintenance exposure, energy intensity, and the potential for modular or phased deployment.
The report integrates these structural drivers into a cohesive analytical narrative, linking regulatory timelines, material and energy cost realities, and technology evolution paths to demand behavior across major application clusters. Rather than treating compliance as a static checkbox, the analysis frames ESP adoption as an ongoing capital and operational decision influenced by enforcement cadence, plant age profiles, fuel mix transitions, and the economics of retrofitting existing units versus installing new systems.
Inside the Report: Operational Content for Executive Action
This study is structured to support practical decisions rather than abstract market commentary. It provides a comprehensive map of the ESP market across technology configurations, application environments, and regional deployment patterns, with historical data and forward forecasts embedded in a consistent analytical framework. The report details revenue progression, growth drivers, constraint factors, and the interplay between regulatory mandates and operational economics, giving readers a clear view of where demand is expanding, where replacement cycles are intensifying, and where competitive competition is concentrating.
Beyond macro trajectory, the publication delivers actionable supplier intelligence. It profiles leading manufacturers and specialized OEMs, outlines their application focus, recent contract and expansion activity, and the strategic implications of their market moves. This competitive mapping is paired with an assessment of market concentration dynamics, enabling readers to understand where scale advantages matter most and where niche or application-specific suppliers can create differentiated value. The report also incorporates sector-level considerations such as material selection pressures, digital control adoption, energy consumption profiles, and compliance-driven procurement behavior, providing context that procurement, engineering, and strategy teams can apply directly to sourcing and investment planning.
Importantly, the full study is designed to be modular in use. Executives can extract high-level growth signals and strategic implications for board-level planning; procurement and engineering teams can drill into supplier capabilities and application fit; and investors or corporate development teams can assess concentration patterns, regional momentum, and the types of commercial activity—such as rebuild contracts, service network expansion, and integrated system deliveries—that signal where value is being captured in the value chain.
How to Use This Intelligence for 2026 Strategy and Sourcing
For organizations planning capital expenditures, compliance upgrades, or vendor evaluations in 2026, the strategic value of this research lies in its ability to convert market signals into operational choices. The growth path, competitive structure, and regulatory context described in the report provide a basis for timing retrofit and replacement programs, evaluating whether to prioritize efficiency upgrades or capacity additions, and selecting suppliers whose installed-base experience and service reach align with specific application requirements. The inclusion of recent contract awards, network expansions, and project deliveries offers tangible reference points for assessing supplier momentum and execution capability.
Electrostatic Precipitators (ESP) Market
At the same time, the most precise segmentation data, regional deployment splits, and application-level revenue breakdowns are reserved within the complete research package. This intentional structure ensures that the full strategic picture—including the detailed allocation of demand across technology types, end-use sectors, and geographies—is available to decision-makers who require resolution fine enough to guide licensing, sourcing, and investment commitments.
Final Perspective
The ESP market entering 2026 is defined by sustained demand growth, a moderately concentrated competitive field, and a regulatory and operational environment that rewards integrated, high-efficiency, and service-supported solutions. Our research translates these conditions into a forward-looking, decision-oriented framework that supports compliance planning, capital allocation, supplier evaluation, and long-range technology strategy. For leaders who need more than headline growth figures—who require supplier-level insight, structural driver analysis, and a forecast architecture aligned with real procurement and investment cycles—this report offers the depth and commercial relevance necessary to act with confidence. Access to the complete segmentation detail and full competitive intelligence is available through the full study, where the complete dataset and methodology can be reviewed in context.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Viscose Filament Yarn Market Reaches $2.89B in 2025, Projected 5.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Next Decade: Unlocking the Viscose Filament Yarns Market Opportunity
The global textile and industrial materials landscape is undergoing a structural transformation. As sustainability mandates tighten, supply chains reconfigure, and performance expectations rise, Viscose Filament Yarns (VFY) have emerged as a critical intermediary between traditional cellulosic manufacturing and next-generation sustainable textiles. For executives, procurement leaders, and strategic planners, understanding where this market is headed is no longer optional; it is a prerequisite for capital allocation, product positioning, and regional expansion.
PW Consulting’s latest deep-dive research on the Viscose Filament Yarns Market is designed to convert macroeconomic complexity into actionable decision architecture. Drawing on a rigorous historical baseline spanning 2020 through 2025 and projecting forward through 2032, this report offers a multi-dimensional view of value creation, competitive pressure points, and regulatory inflection moments that will define the industry over the next seven years.
The market’s trajectory signals a steady expansion path. From a global revenue baseline of approximately 2.27 billion USD in 2020, the sector has advanced through consistent year-over-year growth, reaching an estimated 2.89 billion USD in 2025. The forward-looking forecast places the market on a measured 5.5 percent compound annual growth rate trajectory, with valuations expected to surpass 3.0 billion USD in 2026 and continue a sustained upward curve toward the early 2030s. These figures are not merely historical artifacts; they encode the underlying demand resilience of textile applications, the gradual diversification into medical and industrial end-uses, and the persistent influence of regional manufacturing gravity. More importantly, they establish the scale at which competitive advantage must now be engineered.
For business leaders operating in or adjacent to this market, the strategic question is no longer whether the category will grow, but how to position within a landscape where feedstock volatility, certification expectations, trade policy shifts, and product differentiation intersect simultaneously. This research was built to answer precisely that question.
Viscose Fiber Market
Why This Research Matters for 2026 Decision-Making
The year 2026 represents a pivotal planning horizon. Companies are finalizing capacity commitments, renegotiating supplier frameworks, and aligning product roadmaps with incoming regulatory and sustainability requirements. In this environment, decision-makers need more than aggregated market size numbers. They need a structured view of how demand is distributed across end-use verticals, how regional manufacturing footprints influence pricing and supply security, and how type-level product segmentation reflects commercial priorities such as luster, dyeability, and downstream processing compatibility.
This report is engineered to support that level of operational reasoning. Rather than presenting a single-line growth narrative, the analysis connects market size evolution with the underlying structural drivers that will determine which participants capture margin resilience and which face squeeze. Readers will find a carefully designed framework for interpreting where volume concentrates, where value differentiation is emerging, and where external shocks—whether raw material price swings or trade remedy actions—can reshape short-term profitability.
Equally important, the research is designed to support cross-functional alignment. Strategy teams can use the forecast architecture to test expansion assumptions. Commercial teams can use the segmentation logic to refine positioning against competing fiber categories. Sustainability and compliance teams can use the regulatory and certification discussion to identify where traceability and certification are moving from differentiator to requirement. By integrating these lenses into one coherent intelligence package, the report reduces the risk of siloed decision-making.
Inside the Report: What the Analysis Delivers
A market study earns its value through practical utility. This report is structured to give executives a working map of the Viscose Filament Yarns landscape, not just a static description of it. The analytical content is built to support scenario planning, competitive benchmarking, and entry-or-retreat decisions across multiple dimensions.
At the core of the report is a historically grounded forecast model that traces how the market has moved from its 2020 base through the most recent baseline year and into the projection window extending to 2032. This temporal structure allows readers to evaluate whether recent growth patterns reflect cyclical recovery, structural demand shifts, or region-specific manufacturing expansion. The forecast framework is presented in a way that supports sensitivity reasoning, enabling users to test how changes in feedstock cost, demand elasticity, or trade conditions could alter outcomes.
The segmentation architecture is deliberately designed to illuminate commercial reality. Readers will examine how the market divides by geography, revealing where production concentration, demand pull, and supply chain thickness shape regional competitiveness. The report also breaks down the category by product type, distinguishing between bright and dull viscose filament yarns and explaining how these variants map to different textile finishing requirements, end-market preferences, and price-performance trade-offs. In parallel, the application view provides a structured reading of where demand is anchored, with textiles representing the dominant anchor of market volume and medical, industrial, and other end-uses contributing more specialized, often higher-value demand streams.
Beyond segmentation, the report delivers operational content that leadership teams can use immediately. This includes a supplier and competitor landscape that maps out the strategic posture of key manufacturing players, an assessment of capacity and product range dynamics, and a review of recent launches, facility expansions, and production upgrades that signal where the industry is placing its bets. The study also addresses raw material exposure, particularly the role of dissolving wood pulp and other cellulosic inputs in shaping production economics. Where relevant, pricing movement and feedstock shifts are discussed as leading indicators rather than isolated events, helping readers anticipate cost pressure before it reaches the bottom line.
To support execution, the research also examines the regulatory and standards environment shaping procurement and product design. From sustainability claim verification to trade remedy investigations and regional policy direction, the report connects compliance pressure with commercial consequence. This is especially important for organizations that source across borders or plan to position certified, traceable, or recycled-content yarns as part of their differentiation strategy.
Competitive Landscape: Who Is Shaping the Market
The Viscose Filament Yarns market is defined by a concentrated yet strategically diverse competitive field. Market leadership is not uniform; it varies by region, product range, sustainability positioning, and integration depth across the cellulosic value chain. Understanding these differences is essential for evaluating supplier risk, partnership opportunities, and competitive threats.
Several large-scale producers anchor the industry. In India, Grasim Industries Limited stands out as a major viscose filament yarn manufacturer with broad denier coverage and a developing emphasis on traceable, sustainably sourced product lines. Its recent introduction of a sustainable traceable variant under its established brand family reflects a wider industry push toward verifiable sourcing and differentiated product storytelling. Across China, the competitive picture is equally significant, with multiple integrated players operating at substantial scale. Jilin Chemical Fiber Co., Ltd. represents a producer focused on expandingNext-generation grades with certified wood feedstocks and recycled cotton content, signaling that sustainability-related input strategies are increasingly becoming part of core production planning rather than peripheral branding.
Xinxiang Bailu Chemical Fiber Co., Ltd. contributes to the Chinese manufacturing base with a diversified viscose product set spanning filament, embroidery, and dyeing yarns. Yibin Grace Group Co., Ltd. has pushed further into recycled-content positioning, supported by dedicated capacity and the establishment of a recycled textile dissolving pulp facility, an infrastructure move that points to longer-term feedstock independence and circularity ambitions. Sinopec Yizheng Chemical Fibre Co., Ltd. reflects the advantage of integration within a larger state-linked industrial complex, where filament production is tied to broader dissolving pulp and chemical fiber operations. Sateri Holdings Limited operates at exceptional scale within the broader viscose fiber ecosystem and uses that scale to support filament offerings alongside staple and lyocell products, with a strong international footprint and certification-aligned supply chain.
At the premium and sustainability-led end of the spectrum, Lenzing AG remains a defining reference point for closed-loop, wood-based filament and related cellulosic yarns, particularly where high-luster, biodegradable, and performance-oriented characteristics matter. The presence of such players underscores a broader competitive dynamic: the market is not simply competing on volume, but on fiber quality, environmental credentials, processing efficiency, and downstream compatibility.
Viscose Filament Yarns Market
This competitive diversity creates both opportunity and risk. Buyers can leverage supplier variety to negotiate terms, secure supply, and access differentiated product attributes. Producers, in turn, must defend position through capacity reliability, feedstock strategy, product breadth, and increasingly, verifiable sustainability performance. The report maps these dynamics in detail so that readers can judge where consolidation pressure may intensify, where niche leadership can be defended, and where new entrants or expansions may alter regional balance.
Market Dynamics: Feedstock, Regulation, and Trade Pressures
No forecast exists in a vacuum. The Viscose Filament Yarns market is sensitive to a set of external forces that can amplify or dampen growth outcomes over the forecast period. One of the most immediate is raw material economics. Dissolving wood pulp prices have shown periodic volatility, with quarter-over-quarter movement in key sourcing regions directly affecting production cost structures. When feedstock costs rise, pricing power, margin endurance, and contract timing become critical variables. The report treats these cost dynamics as integral to market interpretation rather than as background noise, helping readers understand how input fluctuations can propagate into pricing, regional competitiveness, and demand timing.
Regulatory and policy developments are shaping the market with equal force. Sustainability claim verification is moving from aspirational positioning toward enforceable expectation. The EU Green Deal textile strategy and related Green Claims Directive implementation are accelerating demand for credibly certified viscose filament yarns, especially those supported by FSC or PEFC-aligned sourcing. For manufacturers and buyers alike, certification is increasingly tied to market access, premium positioning, and reputational risk management. The report contextualizes these shifts so that organizations can separate near-term compliance burdens from longer-term strategic requirements.
Trade policy adds another layer of complexity. Anti-dumping investigations and duty recommendations targeting viscose rayon filament yarn imports have emerged in key markets, including actions involving India and Chinese-origin supply. Where such measures progress toward formal duties, they can alter sourcing patterns, change relative price relationships, and affect the competitiveness of cross-border supply chains. These developments are particularly relevant for companies that rely on imported filament or operate in regions where trade remedy outcomes may shift the balance between domestic and overseas supply.
Finally, price movements in the Asian market illustrate how quickly regional conditions can shift. Recent pricing surges tied to cellulose feedstock volatility demonstrate that regional price signals can diverge from global averages and create short-term windows of advantage or disadvantage. By integrating these dynamics into the broader market narrative, the report gives readers a more realistic foundation for planning than a simple demand-growth storyline would provide.
How to Use This Research for Strategic Advantage
The strongest market research does not simply describe the past; it sharpens the next decision cycle. This report is intended to support a range of strategic actions. For organizations evaluating capacity expansion or product line extension, the segmentation and forecast structure provides a basis for testing where demand depth justifies investment. For procurement and sourcing teams, the regional and competitor analysis supports supplier diversification, contract strategy, and exposure management in environments where feedstock and trade conditions can change quickly.
For commercial leaders, the bright versus dull product distinction and the application mix offer a framework for aligning product attributes with customer priorities, whether those priorities center on aesthetics, dye behavior, processing efficiency, or end-use performance. For sustainability and compliance functions, the regulatory discussion helps prioritize certification pathways, traceability investments, and claims substantiation in markets where verifiable sustainability is becoming a condition of participation rather than a voluntary advantage.
Most importantly, the report supports integrated decision-making. Growth potential, competitive intensity, feedstock exposure, and regulatory direction are rarely independent. This research connects them so that executives can evaluate trade-offs more clearly, challenge internal assumptions more effectively, and align strategy across functions with a shared view of the market’s direction.
Conclusion
The Viscose Filament Yarns Market is entering a period in which scale, sustainability, and supply-chain resilience must be managed together. Historical growth has established a meaningful base, and the forward forecast points to continued expansion through the end of the decade and into the early 2030s. Yet the real strategic challenge lies beneath the headline trajectory: understanding where demand is concentrated, how competitors are positioning themselves, how feedstock and trade dynamics influence margin, and how sustainability requirements are reshaping procurement expectations.
PW Consulting’s full market research report provides the depth required to navigate that complexity. It combines historical context, forecast architecture, segmentation logic, competitive profiling, and market-dynamic analysis into a single decision-ready framework. For leaders who need to move beyond surface-level market sizing and toward targeted, evidence-based strategy, the complete study offers the intelligence necessary to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Viscose Filament Yarns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Biogas Market Hits $63.48B in 2025, Projected to Reach $90.82B by 2032 at 5.27% CAGR
By pmarketresearch, 2026-09-15
Navigating the Biogas Transition: Strategic Intelligence for 2026 and Beyond
The global energy landscape is undergoing a structural shift, driven by decarbonization mandates and the urgent need for sustainable waste management solutions. At the heart of this transformation is the biogas sector, a market that has evolved from a niche renewable energy source into a critical component of the circular economy. For corporate strategists, investors, and policymakers, understanding the trajectory of this market is no longer optional it is a prerequisite for resilient decision-making.
PW Consulting is pleased to introduce our latest comprehensive market research, designed specifically to equip stakeholders with the actionable intelligence needed to navigate the complexities of 2026 and the subsequent seven-year forecast period. This report moves beyond surface-level headlines to deliver a granular analysis of market dynamics, competitive positioning, and risk factors that define the current operational environment.
As we enter a new fiscal year, the decisions made today regarding asset allocation, supply chain partnerships, and technology adoption will dictate competitive advantage for the remainder of the decade. The following analysis outlines the macro-economic context and the strategic value embedded within this new research publication, offering a preview of the depth and rigor applied to our findings.
Macro-Economic Trajectory and Market Size
The biogas industry has demonstrated remarkable resilience and growth potential over the past five years. Our historical analysis covering the period from 2020 through 2025 reveals a consistent upward trend in revenue generation across the sector. The market valuation data indicates that the industry has successfully navigated supply chain disruptions and regulatory shifts that challenged other renewable sectors during the same timeframe.
Looking forward, the forecast period spanning 2026 to 2032 suggests a sustained growth trajectory. Our models project a Compound Annual Growth Rate (CAGR) of 5.27 percent over this horizon. This growth rate, while steady, masks significant volatility in specific sub-sectors and regions, which our report unpacks in detail. The market is expected to reach substantial valuation milestones by 2032, reflecting not only organic expansion but also increasing integration into broader energy grids and transport fuel mandates.
It is important to note that while the aggregate numbers show growth, the base year data from 2025 highlights a market that is maturing. The transition from high-growth experimental phases to commercial-scale deployment is evident in the revenue patterns. Stakeholders must understand where the growth is concentrated to avoid overexposure to saturating segments while capitalizing on emerging opportunities. Our full analysis provides the specific vessel for this understanding without relying on generalized industry averages.
Segmentation Dynamics and Feedstock Realities
The composition of the biogas market is defined by diverse input materials and application endpoints. Understanding the weight of different feedstock types is essential for evaluating supply chain security and operational costs. Our segmentation analysis covers agricultural waste, municipal waste, sewage sludge, and energy crops. However, raw numbers only tell part of the story.
Recent industry intelligence gathered from IEA Bioenergy Task 37 indicates that manure feedstock prices have risen due to volatility in fertilizer markets, directly increasing operational costs for manure-based anaerobic digestion plants. This cost pressure alters the profitability equations for specific plant types. Similarly, data from the Global Methane Initiative suggests that feedstock prices for cow dung in India have doubled due to disruptions affecting agricultural demand, leading to unprofitability and plant shutdowns in certain regions. These are not isolated incidents but indicators of structural risks within specific feedstock categories.
On the application side, the market serves ends ranging from electricity generation and heating to combined heat and power systems and biofuel production. The mix of these applications varies significantly by geography and regulatory environment. Our report dissects which applications are driving margin expansion versus those that rely heavily on subsidies. By analyzing the interplay between feedstock availability and end-use demand, we identify where logistical bottlenecks may emerge in 2026 and beyond.
Competitive Landscape and Key Players
The competitive environment in the biogas sector is characterized by a mix of specialized technology providers, large-scale operators, and influential industry associations. While market concentration metrics suggest a relatively fragmented landscape on paper, influence is often concentrated among key innovators and strategic developers who are setting the standards for technology and sustainability.
Our research profiles several core enterprises that are shaping the market. In the United Kingdom, Future Biogas stands out as a leading operator and developer, notably securing offtake agreements for unsubsidised biomethane projects, such as their facility for AstraZeneca. This signals a shift towards corporate power purchase agreements that reduce reliance on public subsidies.
Technology providers are equally critical. Clarke Energy, based in the UK, has expanded its footprint as a supplier of biogas upgrading systems. Their recent commissioning of the first membrane-based biogas upgrader in India demonstrates the globalization of technology deployment. In Germany, EnviTec Biogas AG remains a pivotal manufacturer of plant technology and components for anaerobic digestion systems worldwide, while VORN Bioenergy GmbH focuses on operating and developing facilities.
Corporate involvement is also increasing. Air Products and Chemicals from the USA provides membrane solutions for biogas separation, highlighting the convergence of industrial gas expertise with renewable energy infrastructure. Other significant players include Entsorga S.p.A. in Italy, known for waste-to-energy facilities, Green Data Science in Germany specializing in biomethane upgrading, and Genia Bioenergy in Spain, which focuses on livestock and agricultural waste facilities.
Industry associations play a surveillance and advocacy role that indirectly shapes market conditions. The American Biogas Council provides critical industry data, reporting that US biogas investment exceeded 2 billion dollars in 2025 with 70 new projects coming online. Meanwhile, the European Biogas Association released its 15th Statistical Report highlighting 165 new biomethane plants operational in the EU during 2024-2025. These data points inform our assessment of market momentum but the strategic implications vary widely by stakeholder type.
Biogas Power Plants Market
Regulatory and Operational Dynamics
No strategic analysis of the biogas market is complete without a rigorous examination of the regulatory framework. The period from 2025 to 2026 is seeing significant policy adjustments that alter the economic viability of projects. In Europe, the EU Methane Regulation 2024 requires detection and repair of methane leakage. However, recent analysis by the European Environmental Bureau points out there are no equivalent mandatory requirements for biogas and biomethane plants, creating a regulatory asymmetry that informed investors should monitor closely.
Furthermore, the EU energy crop limit for biomethane has been tightened. According to the HyFuelUp consortium, a floor deduction reduces the limit from 12 percent to 4 percent in 2025/2026. This shift pushes the market away from energy crops and towards waste-based feedstocks, fundamentally changing the supply chain requirements for producers.
Economic incentives are also undergoing revision. For instance, the Danish gas distribution company Evida proposed a new tariff model from January 2025 imposing a large feed-in tariff that reduces incentives for green biogas producers. Such changes at the regional level can ripple through investment models, affecting internal rates of return and payback periods.
Biogas Market
Our report synthesizes these regulatory fragments into a cohesive risk matrix. We analyze how these policies impact different project types and geographies, allowing readers to anticipate compliance costs and permitting delays. The goal is to provide a clear view of where policy support is strengthening and where it is thinning.
Why This Research Matters for 2026 Decision Making
In a market defined by policy volatility and feedstock fluctuations, generic market reports fail to provide the specificity needed for high-stakes decisions. Our research is built on the premise that competitive advantage comes from anticipating change before it becomes mainstream news. We do not just report what happened; we model what happens next.
For operations managers, this study offers insights into supply chain resilience, particularly regarding feedstock procurement in volatile markets. For financial analysts, the breakdown of revenue streams by application and region helps in valuation modeling and risk assessment. For policymakers and association leaders, the analysis of industry developments and regulatory gaps offers a benchmark against which to measure future policy efficacy.
The report includes detailed profiles of key companies, analysis of recent developments such as new plant launches and investment milestones, and a forward-looking assessment of market concentration. We also incorporate industry context noise, turning raw facts about material costs and regulatory changes into strategic signals.
This level of detail is crucial because the biogas market is not a monolith. A strategy that works for agricultural waste in Europe may not translate to municipal waste in Asia Pacific or energy crops in Latin America. Our segmentation analysis respects these differences, providing the nuance required to tailor strategies to specific contexts.
Conclusion
The biogas sector offers significant opportunities for growth and sustainability impact, but capturing that value requires precise intelligence. As the market moves toward 2032, the convergence of regulatory pressure, technological innovation, and feedstock economics will create winners and losers. PW Consulting's new Biogas Market research is designed to ensure that your organization is positioned among the winners.
To fully leverage the findings outlined in this preview, we invite you to access the complete report on our website. The full document contains the specific data tables, deep-dive regional analysis, and detailed financial modeling necessary to build a robust 2026 strategy. Trust in data-driven insight to navigate the complexities of the biogas revolution.
For detailed analysis of this topic, please visit the official page: Biogas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pelvic Organ Prolapse Repair Device Market to Hit $1,573.3M by 2032, 8.32% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Pelvic Organ Prolapse Repair Device Market: Navigating Growth and Complexity in 2026
The global landscape for pelvic organ prolapse repair devices is undergoing a profound transformation. For medical device executives, investors, and strategic planners, understanding the nuanced interplay between regulatory shifts, material science advancements, and evolving surgical preferences is no longer optional—it is critical for survival and growth. As we move into 2026, the market presents a complex matrix of opportunities tempered by significant compliance and reimbursement challenges. This article serves as a strategic primer, drawing from our latest comprehensive market research report, designed to equip leadership teams with the foresight needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the global market for pelvic organ prolapse repair devices, valued at approximately 892.5 million USD in 2025, is on a steady upward trajectory. The sector is projected to expand significantly over the coming years, reaching a valuation of 1,573.3 million USD by 2032. This growth is underpinned by an estimated Compound Annual Growth Rate (CAGR) of 8.32 percent during the forecast period. However, raw top-line numbers only tell a fraction of the story. The real strategic value lies in understanding the drivers behind this expansion, the fragmentation within the competitive landscape, and the specific dynamics reshaping product portfolios and surgical protocols.
Market Trajectory and Value Driver Analysis
The historical data from 2020 to 2025 reveals a consistent pattern of growth, recovering from 712.5 million USD in 2020 to the current 2025 baseline. This historical resilience sets the stage for the forecast period. The projected increase from 957.66 million USD in 2026 to over 1.5 billion USD by 2032 suggests a market that is maturing but still expanding. For stakeholders, this implies that while the low-hanging fruit of early adoption may be diminishing, significant volume remains in emerging markets and in the adoption of advanced procedural kits.
Several macroeconomic and demographic factors are converging to drive this demand. The aging global population continues to be a primary catalyst, as the prevalence of pelvic floor disorders increases with age. Furthermore, there is a shifting preference toward minimally invasive procedures and outpatient settings, driven by cost containment pressures within healthcare systems. This shift influences not just the volume of procedures but the type of devices being procured. For instance, the move toward single-use procedural instrumentation configurations reduces the need for extensive institutional sterilization infrastructure in ambulatory settings, aligning with hospital efficiency goals. Understanding where this shift is most pronounced geographically and by procedure type is essential for market entry or expansion strategies.
The Competitive Landscape: Consolidation and Innovation
The competitive environment is characterized by a moderate level of concentration. Our analysis shows that the top three companies hold approximately 58.0 percent of the market share, while the top five control around 62.0 percent. This concentration indicates that while there are dominant players, there is still substantial room for challengers and niche innovators to carve out significant value positions. The presence of major multinational corporations alongside specialized innovators creates a dynamic ecosystem where acquisition targets and partnership opportunities are frequent.
Pelvic Organ Prolapse Repair Device Market
Key players are actively differentiating their portfolios through technological innovation and strategic positioning. Johnson & Johnson MedTech (Ethicon) continues to leverage its scale to offer bioresorbable materials and minimally invasive kits aimed at restoring pelvic ligament support. Similarly, Boston Scientific Corporation provides the Capio SLIM suture-capturing device and Upsylon Y-Mesh, focusing on pelvic floor reconstruction and prolapse repair. These large entities benefit from established distribution networks and comprehensive reimbursement support.
However, the market is also seeing activity from specialized players. Coloplast Group develops and supplies biologic mesh solutions and procedural kits, capitalizing on the shift toward biological materials. Cook Medical Incorporated supplies customized mesh solutions and instrumentation for patient-specific reconstruction, addressing the need for tailored surgical outcomes. Integra LifeSciences and CooperSurgical, Inc. also remain pivotal, providing biologic grafts, support systems, and procedural kits. Additionally, companies like Utah Medical Products, Inc. focus on manufacturing instruments and support systems that streamline the procedural workflow.
Innovation is also coming from newer entrants disrupting traditional paradigms. Escala Medical, based in Israel, offers the Mendit device, an FDA-cleared incision-free anchor system for pelvic organ prolapse surgical repair. This type of innovation represents a shift away from traditional mesh or graft reliance toward anchor-based systems. In June 2025, Escala Medical raised 4.5m EUR (approximately 5.3m USD) to accelerate commercialization and global expansion of the Mendit device, signaling strong investor confidence in alternative surgical approaches. Meanwhile, regulatory clearances continue to shape the non-surgical segment. In March 2024, Cosm Medical received FDA 510(k) clearance for the Gynethotics Pessary, a collapsible device for temporary nonsurgical management, highlighting the ongoing demand for conservative management options alongside surgical interventions.
Regulatory and Reimbursement Dynamics
No strategic analysis of this market is complete without a rigorous examination of the regulatory and reimbursement environment. These factors often dictate the viability of product lines and the speed of adoption. The regulatory landscape presents a dichotomy of challenges and opportunities. The FDA maintains that transvaginal surgical mesh devices for pelvic organ prolapse do not have a favorable benefit-risk profile due to potential additional risks compared to native tissue repair. This stance has fundamentally altered product development roadmaps for many manufacturers, pushing innovation toward bioresorbable materials and alternative support systems.
In response to these regulatory pressures, new bioresorbable mesh solutions from major manufacturers emphasize faster tissue integration to address post-operative complication concerns in pelvic organ prolapse repair. This technological pivot is not merely a compliance exercise but a competitive differentiator. Companies that can demonstrate superior tissue integration and reduced complication rates are likely to secure preferential positioning with surgeons and hospital procurement committees. Furthermore, biological grafts are noted as the fastest-growing segment in pelvic organ prolapse repair following reduced synthetic mesh use. This trend underscores the importance of material science in the current market cycle.
On the reimbursement front, clarity is essential for financial modeling. Pelvic organ prolapse repair procedures such as transabdominal allograft treatment use CPT code 57280, which is reimbursed under Medicare physician fee schedules. Understanding the nuances of coding and payment guides, such as the Boston Scientific 2026 Coding and Payment Guide, is vital for sales teams and market access strategists. Variations in reimbursement policies across different regions can significantly impact the total addressable market for specific device types. Our full report delves into these nuances, providing the granular data necessary to model revenue streams accurately under different regulatory scenarios.
Strategic Implications for 2026 Decision Makers
As we approach 2026, several strategic imperatives emerge for organizations operating in this space. First, portfolio diversification is key. Given the regulatory scrutiny on synthetic mesh, companies must balance their offerings with biologic grafts and non-mesh support systems. Relying too heavily on a single material class exposes a firm to significant risk if regulatory guidance tightens further. Second, geographic expansion strategies must be data-driven. Different regions exhibit different adoption rates for new technologies and varying levels of regulatory strictness. Understanding where the market volume is concentrated without relying on generic data is crucial for resource allocation.
Third, partnerships and M&A activity should be monitored closely. The presence of companies like Escala Medical securing funding for novel devices suggests that venture capital is willing to back innovation in this sector. For larger incumbents, acquiring these technologies could accelerate their pipeline and mitigate risks associated with internal R&D delays. Fourth, sales and marketing efforts should align with the shift toward ambulatory settings. Emphasizing single-use instrumentation and ease of use in marketing collateral can resonate with facilities looking to optimize throughput and reduce sterilization costs.
Unlocking the Full Intelligence Picture
While this overview highlights the macro trends, the competitive moves, and the regulatory constraints, it necessarily omits the granular data required for immediate operational planning. To make informed decisions for 2026 and beyond, leadership needs access to detailed segmentation analysis, precise regional breakdowns, and specific application-based growth rates. Our full market research report provides this depth. It dissects the market by specific device types, application categories, and regional dynamics, offering the precise metrics needed to validate strategic hypotheses.
Vaginal Pessary Market
The report includes comprehensive profiles of key companies, detailed analysis of recent developments, and a thorough examination of the industry context noise that impacts market viability. It moves beyond general observations to provide actionable intelligence on market share distributions, growth vectors within specific segments, and the financial implications of regulatory changes. For executives who need to justify capital allocation, R&D spending, or market entry strategies to their boards, this level of detail is indispensable.
The pelvic organ prolapse repair device market is poised for significant growth, but the path to capturing that value is fraught with complexity. The difference between success and stagnation lies in the quality of intelligence guiding your strategy. We invite you to access the full research study to obtain the complete dataset, including specific regional valuations, segment percentage splits, and detailed company competitive analysis. Equip your organization with the precise knowledge required to lead in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Pelvic Organ Prolapse Repair Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com