

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pelvic Organ Prolapse Repair Device Market to Hit $1,573.3M by 2032, 8.32% CAGR

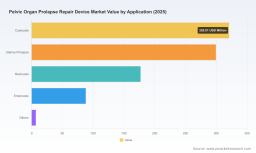
Strategic Intelligence for the Pelvic Organ Prolapse Repair Device Market: Navigating Growth and Complexity in 2026
The global landscape for pelvic organ prolapse repair devices is undergoing a profound transformation. For medical device executives, investors, and strategic planners, understanding the nuanced interplay between regulatory shifts, material science advancements, and evolving surgical preferences is no longer optional—it is critical for survival and growth. As we move into 2026, the market presents a complex matrix of opportunities tempered by significant compliance and reimbursement challenges. This article serves as a strategic primer, drawing from our latest comprehensive market research report, designed to equip leadership teams with the foresight needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the global market for pelvic organ prolapse repair devices, valued at approximately 892.5 million USD in 2025, is on a steady upward trajectory. The sector is projected to expand significantly over the coming years, reaching a valuation of 1,573.3 million USD by 2032. This growth is underpinned by an estimated Compound Annual Growth Rate (CAGR) of 8.32 percent during the forecast period. However, raw top-line numbers only tell a fraction of the story. The real strategic value lies in understanding the drivers behind this expansion, the fragmentation within the competitive landscape, and the specific dynamics reshaping product portfolios and surgical protocols.
Market Trajectory and Value Driver Analysis
The historical data from 2020 to 2025 reveals a consistent pattern of growth, recovering from 712.5 million USD in 2020 to the current 2025 baseline. This historical resilience sets the stage for the forecast period. The projected increase from 957.66 million USD in 2026 to over 1.5 billion USD by 2032 suggests a market that is maturing but still expanding. For stakeholders, this implies that while the low-hanging fruit of early adoption may be diminishing, significant volume remains in emerging markets and in the adoption of advanced procedural kits.
Several macroeconomic and demographic factors are converging to drive this demand. The aging global population continues to be a primary catalyst, as the prevalence of pelvic floor disorders increases with age. Furthermore, there is a shifting preference toward minimally invasive procedures and outpatient settings, driven by cost containment pressures within healthcare systems. This shift influences not just the volume of procedures but the type of devices being procured. For instance, the move toward single-use procedural instrumentation configurations reduces the need for extensive institutional sterilization infrastructure in ambulatory settings, aligning with hospital efficiency goals. Understanding where this shift is most pronounced geographically and by procedure type is essential for market entry or expansion strategies.
The Competitive Landscape: Consolidation and Innovation
The competitive environment is characterized by a moderate level of concentration. Our analysis shows that the top three companies hold approximately 58.0 percent of the market share, while the top five control around 62.0 percent. This concentration indicates that while there are dominant players, there is still substantial room for challengers and niche innovators to carve out significant value positions. The presence of major multinational corporations alongside specialized innovators creates a dynamic ecosystem where acquisition targets and partnership opportunities are frequent.
Pelvic Organ Prolapse Repair Device Market
Key players are actively differentiating their portfolios through technological innovation and strategic positioning. Johnson & Johnson MedTech (Ethicon) continues to leverage its scale to offer bioresorbable materials and minimally invasive kits aimed at restoring pelvic ligament support. Similarly, Boston Scientific Corporation provides the Capio SLIM suture-capturing device and Upsylon Y-Mesh, focusing on pelvic floor reconstruction and prolapse repair. These large entities benefit from established distribution networks and comprehensive reimbursement support.
However, the market is also seeing activity from specialized players. Coloplast Group develops and supplies biologic mesh solutions and procedural kits, capitalizing on the shift toward biological materials. Cook Medical Incorporated supplies customized mesh solutions and instrumentation for patient-specific reconstruction, addressing the need for tailored surgical outcomes. Integra LifeSciences and CooperSurgical, Inc. also remain pivotal, providing biologic grafts, support systems, and procedural kits. Additionally, companies like Utah Medical Products, Inc. focus on manufacturing instruments and support systems that streamline the procedural workflow.
Innovation is also coming from newer entrants disrupting traditional paradigms. Escala Medical, based in Israel, offers the Mendit device, an FDA-cleared incision-free anchor system for pelvic organ prolapse surgical repair. This type of innovation represents a shift away from traditional mesh or graft reliance toward anchor-based systems. In June 2025, Escala Medical raised 4.5m EUR (approximately 5.3m USD) to accelerate commercialization and global expansion of the Mendit device, signaling strong investor confidence in alternative surgical approaches. Meanwhile, regulatory clearances continue to shape the non-surgical segment. In March 2024, Cosm Medical received FDA 510(k) clearance for the Gynethotics Pessary, a collapsible device for temporary nonsurgical management, highlighting the ongoing demand for conservative management options alongside surgical interventions.
Regulatory and Reimbursement Dynamics
No strategic analysis of this market is complete without a rigorous examination of the regulatory and reimbursement environment. These factors often dictate the viability of product lines and the speed of adoption. The regulatory landscape presents a dichotomy of challenges and opportunities. The FDA maintains that transvaginal surgical mesh devices for pelvic organ prolapse do not have a favorable benefit-risk profile due to potential additional risks compared to native tissue repair. This stance has fundamentally altered product development roadmaps for many manufacturers, pushing innovation toward bioresorbable materials and alternative support systems.
In response to these regulatory pressures, new bioresorbable mesh solutions from major manufacturers emphasize faster tissue integration to address post-operative complication concerns in pelvic organ prolapse repair. This technological pivot is not merely a compliance exercise but a competitive differentiator. Companies that can demonstrate superior tissue integration and reduced complication rates are likely to secure preferential positioning with surgeons and hospital procurement committees. Furthermore, biological grafts are noted as the fastest-growing segment in pelvic organ prolapse repair following reduced synthetic mesh use. This trend underscores the importance of material science in the current market cycle.
On the reimbursement front, clarity is essential for financial modeling. Pelvic organ prolapse repair procedures such as transabdominal allograft treatment use CPT code 57280, which is reimbursed under Medicare physician fee schedules. Understanding the nuances of coding and payment guides, such as the Boston Scientific 2026 Coding and Payment Guide, is vital for sales teams and market access strategists. Variations in reimbursement policies across different regions can significantly impact the total addressable market for specific device types. Our full report delves into these nuances, providing the granular data necessary to model revenue streams accurately under different regulatory scenarios.
Strategic Implications for 2026 Decision Makers
As we approach 2026, several strategic imperatives emerge for organizations operating in this space. First, portfolio diversification is key. Given the regulatory scrutiny on synthetic mesh, companies must balance their offerings with biologic grafts and non-mesh support systems. Relying too heavily on a single material class exposes a firm to significant risk if regulatory guidance tightens further. Second, geographic expansion strategies must be data-driven. Different regions exhibit different adoption rates for new technologies and varying levels of regulatory strictness. Understanding where the market volume is concentrated without relying on generic data is crucial for resource allocation.
Third, partnerships and M&A activity should be monitored closely. The presence of companies like Escala Medical securing funding for novel devices suggests that venture capital is willing to back innovation in this sector. For larger incumbents, acquiring these technologies could accelerate their pipeline and mitigate risks associated with internal R&D delays. Fourth, sales and marketing efforts should align with the shift toward ambulatory settings. Emphasizing single-use instrumentation and ease of use in marketing collateral can resonate with facilities looking to optimize throughput and reduce sterilization costs.
Unlocking the Full Intelligence Picture
While this overview highlights the macro trends, the competitive moves, and the regulatory constraints, it necessarily omits the granular data required for immediate operational planning. To make informed decisions for 2026 and beyond, leadership needs access to detailed segmentation analysis, precise regional breakdowns, and specific application-based growth rates. Our full market research report provides this depth. It dissects the market by specific device types, application categories, and regional dynamics, offering the precise metrics needed to validate strategic hypotheses.
Vaginal Pessary Market
The report includes comprehensive profiles of key companies, detailed analysis of recent developments, and a thorough examination of the industry context noise that impacts market viability. It moves beyond general observations to provide actionable intelligence on market share distributions, growth vectors within specific segments, and the financial implications of regulatory changes. For executives who need to justify capital allocation, R&D spending, or market entry strategies to their boards, this level of detail is indispensable.
The pelvic organ prolapse repair device market is poised for significant growth, but the path to capturing that value is fraught with complexity. The difference between success and stagnation lies in the quality of intelligence guiding your strategy. We invite you to access the full research study to obtain the complete dataset, including specific regional valuations, segment percentage splits, and detailed company competitive analysis. Equip your organization with the precise knowledge required to lead in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Pelvic Organ Prolapse Repair Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com