

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Contact Lens Solution Market Hits $2.2B in 2025, Nears $2.9B by 2032

Strategic Horizons 2026: Navigating Growth and Consolidation in the Global Contact Lens Solution Market
Executive Preview
The contact lens solution market stands at a pivotal juncture as we move through 2026, characterized by steady quantitative expansion and an increasingly complex competitive architecture. Recent comprehensive analysis from PW Consulting indicates that the global market, estimated at USD 2,200 Million in 2025, is projected to reach approximately USD 2,900 Million by 2032. This trajectory reflects a compound annual growth rate of 4.5 percent over the forecast period, signaling a resilient industry ecosystem that continues to attract strategic investment despite macroeconomic headwinds and evolving regulatory frameworks.
For executives, product managers, and commercial strategists, these aggregate figures represent more than baseline growth. They encapsulate shifting consumer preferences, the maturation of silicone hydrogel adoption, persistent emphasis on ocular health and hygiene, and the strategic importance of formulation innovation. The current market landscape is shaped by a historical progression from USD 1,850.0 Million in 2020 through successive annual expansions, reaching USD 2,104.55 Million in 2024 and crossing the USD 2,200.0 Million threshold in 2025. This consistent upward momentum provides a reliable foundation for demand forecasting, capacity planning, and portfolio optimization.
Our freshly published Contact Lens Solution Market research offers an actionable, data-rich roadmap tailored for 2026 decision-making. It moves beyond surface-level narratives to deliver granular demand patterns, competitive benchmarking, regulatory touchpoints, and scenario-based projections that enable organizations to align their go-to-market strategies with realistic commercial pathways. The following overview highlights the strategic architecture of the study while preserving the detailed segmentation intelligence that readers can access through the complete report.
Macro Trajectory and Forecasting Architecture
The projected growth pattern from 2026 through 2032 illustrates a market that is expanding in size while simultaneously experiencing subtle cyclical adjustments and regional recalibration. Following the 2025 baseline of USD 2,200.0 Million, the forecast indicates market expansion to approximately USD 2,324.99 Million in 2026, advancing to USD 2,476.25 Million in 2027 and USD 2,579.58 Million in 2028. A modest consolidation phase appears around 2029, with values stabilizing near USD 2,558.63 Million before resuming growth toward USD 2,682.82 Million in 2030, USD 2,728.37 Million in 2031, and the terminal forecast figure of USD 2,900.0 Million in 2032.
This ebb-and-flow structure is not an anomaly; it reflects the integration of demand saturation in mature channels, distribution recalibration, product cycle timing, and the lag effects of regulatory or raw material fluctuations. Decision-makers who rely on linear extrapolations risk misallocating resources or underestimating the strategic value of timing-specific interventions. Our forecasting framework incorporates historical continuity from 2020 through 2025, ensuring that short-term operational plans are anchored in empirically observed performance rather than speculative optimism.
Strategic Segmentation and Commercial Implications
A central pillar of this research is its segmentation architecture, which enables companies to isolate high-potential avenues without losing sight of the broader market system. The analysis evaluates demand distribution across application types, formulation categories, and geographical footprint, offering a structured lens through which to prioritize product development, sales force deployment, and packaging strategy.
Within application-driven demand, the study examines how rinsing, cleaning, and disinfecting functions interact with lens material evolution, wearer compliance behavior, and professional recommendations from optometrists and ophthalmologists. Rather than presenting static percentages, the report explores the relative commercial weight of each function, the operational implications for manufacturing and fill-finish processes, and the consumer education dynamics that influence repeat purchase frequency. These insights are critical for organizations seeking to position formulations that balance convenience with clinical trust.
The type-based evaluation provides a parallel view of competitive differentiation across multi-purpose systems, hydrogen peroxide-based formulations, and complementary categories. Each type carries distinct value propositions, stability considerations, packaging constraints, and user-experience expectations. By examining how these categories perform in practical usage environments and how they align with evolving lens material compatibility, the research helps stakeholders determine where incremental innovation can generate disproportionate returns and where commoditization risks may require defensive pricing or service-based differentiation.
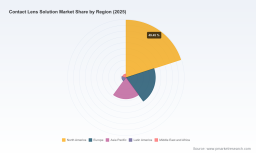
Geographically, the report maps the global landscape through a functional distribution lens that highlights the operational characteristics of major regional markets. Instead of reducing complex trade dynamics to simplistic regional rankings, the analysis explores market penetration patterns, channel maturity, retail and pharmacy influence, and the role of local regulatory expectations in shaping product availability. This enables enterprises to identify where near-term volume capture is achievable versus where longer-term brand-building and distribution partnership strategies will yield more sustainable outcomes.
Competitive Dynamics and Enterprise Positioning
The contact lens solution sector remains notably concentrated, with the top three enterprises collectively representing approximately 65 percent of market revenue and the top five firms accounting for around 75 percent. Such concentration intensifies the strategic stakes for both incumbents and challengers. Established players must defend share through continuous formulation enhancement, brand reinforcement, and channel efficiency, while emerging or niche participants need clear differentiation vectors to gain retailer trust and professional endorsement.
Contact Lenses Market
The competitive landscape examined in this study features organizations with distinct operational identities and strategic priorities. Bausch + Lomb Incorporated, headquartered in Rochester, NY, maintains a strong presence through its multi-purpose portfolios, emphasizing hydration, cleaning, and disinfection attributes that align with mainstream wearer routines. Alcon Inc., based in Fort Worth, TX, leverages its solution lines to address disinfection performance, protein removal, and all-day comfort, reinforcing clinical credibility alongside consumer convenience. CooperVision, Inc., operating from New York, NY, supports both soft and rigid lens care through multipurpose and peroxide system offerings, reflecting the importance of lens-type compatibility in product strategy.
International players contribute further dimensionality to the market structure. Menicon Co., Ltd., located in Nagoya, Japan, supports silicone hydrogel and rigid gas permeable lens ecosystems, highlighting the importance of material-specific formulation expertise. Contamac Holdings Limited, based in London, UK, specializes in lens materials and multipurpose or peroxide solutions for GP, scleral, and hybrid lenses, positioning itself within specialized care segments. Oté Pharma Sol B.V., from Uden, Netherlands, emphasizes preservative-free and peroxide-based options for soft and RGP lenses, reflecting demand for gentler formulation profiles. OPHTECS Corp., headquartered in Tokyo, Japan, advances innovative care solutions that span multipurpose and specialized formulations, underscoring the continued relevance of product differentiation in a crowded category.
Beyond the incumbents, recent industry activity illustrates how regulatory milestones and product innovation continuously reshape commercial expectations. In December 2025, Bruno Vision Care LLC received FDA clearance for the first EDOF daily disposable contact lens incorporating extended depth of focus optics. While this development directly concerns lens hardware, it signals broader momentum in vision correction technology and reinforces the strategic interdependence between lens design, wearer demographics, and care solution requirements. As lens formats evolve, solution providers must anticipate compatibility demands, consumer education needs, and packaging or instructional adjustments.
Regulatory, Raw Material, and Reimbursement Considerations
Market performance in this category is heavily mediated by regulatory expectations, formulation governance, and reimbursement accessibility. Contact lens solutions are regulated as Class II FDA devices, requiring 510(k) clearance and sterility testing per USP <71>. Compliance with 21 CFR § 800.12 for tamper-resistant packaging and labeling adds another operational layer, while any significant design or formulation change triggers the need for updated 510(k) notifications. These requirements shape development timelines, cost structures, and the agility with which companies can launch iterative improvements.
Formulation integrity also depends on the careful selection and control of standard ingredients such as preservatives, wetting agents, disinfectants, and humectants. These components must ensure sterility, compatibility with diverse lens materials, and consistent user experience. Supply chain resilience, vendor qualification, and quality assurance protocols therefore become strategic assets rather than routine procurement matters. Any disruption in raw material availability or qualification standards can affect fill rates, regional availability, and time-to-market for reformulated offerings.
On the consumer side, reimbursement accessibility through Health FSA and FSA accounts when purchased for vision care treatment influences purchase behavior and channel selection. This financial mechanism can enhance affordability and encourage consistent replenishment, particularly in markets where out-of-pocket sensitivity is high. However, it also requires clear documentation, retail enrollment support, and consumer communication strategies that convert reimbursement eligibility into tangible repeat purchase behavior. The study incorporates these factors into a broader examination of demand durability and channel economics.
Contact Lens Solution Market
Report Contents and Decision-Ready Framework
The complete report is designed to support cross-functional planning with practical, implementation-focused content. It provides:
- A full market size and forecast model spanning the historical period and the 2026-2032 outlook, structured for scenario testing and revenue planning
- Segment-level evaluation across application functions, formulation types, and regional distribution patterns to guide portfolio prioritization
- Competitive profiling of key market participants, with attention to product architectures, strategic emphasis, and positioning logic
- Analysis of regulatory requirements, formulation ingredients, packaging constraints, and reimbursement dynamics that affect commercial execution
- Exploration of demand drivers, distribution channel behavior, professional endorsement influence, and consumer compliance patterns
- Identification of near-term opportunities and risk factors that can affect production planning, pricing strategy, and market entry timing
To maintain the depth and integrity of the analysis, detailed regional values, application-level revenue breakdowns, and type-specific market shares are provided within the full report rather than in this overview. This approach preserves the strategic narrative while ensuring that precise figures remain accessible to stakeholders who require them for internal modeling, investment justification, and operational planning.
Strategic Takeaways for 2026
As organizations prepare for the remainder of 2026 and look toward the end of the decade, several strategic imperatives emerge from the market structure. First, growth is real but must be managed with discipline, given the concentration of revenue among leading firms and the cyclical nature of the forecast curve. Second, differentiation increasingly depends on formulation credibility, lens compatibility, packaging reliability, and consumer education rather than price competition alone. Third, regulatory compliance and quality assurance are not overhead items but core strategic capabilities that influence speed, cost, and market access. Fourth, reimbursement frameworks and channel dynamics can materially affect repeat purchase behavior and should be integrated into commercial planning.
The Contact Lens Solution Market research from PW Consulting equips leaders with the intelligence required to navigate these complexities. By combining historical continuity, forecast discipline, segmentation clarity, and competitive context, the study supports more confident decisions around product focus, geographic prioritization, partner selection, and capacity alignment. The full report contains the precise figures, segmentation resolution, and comparative detail needed for rigorous internal analysis and executive-level strategy development.
For detailed analysis of this topic, please visit the official page: Contact Lens Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com