

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Softeners Market to Reach $5,244M by 2032 at 6.85% CAGR

Strategic Intelligence in the Global Water Softeners Market: Navigating Growth and Consolidation Through 2032
Executive Overview
Hard water remains a persistent challenge across residential, commercial, and industrial sectors, driving sustained demand for reliable softening solutions. As infrastructure ages, regulatory standards tighten, and end-user awareness of scale prevention and appliance longevity improves, the water softeners market has entered a phase of structural expansion. Our latest market research publication maps this trajectory with granular precision, offering decision-makers a clear lens into revenue flows, technological shifts, and competitive positioning. The study spans historical performance from 2020 through 2025 and extends a forward-looking forecast window from 2026 to 2032, anchored in a base year of 2025. By translating macro-level momentum into actionable strategic guidance, this intelligence serves as a critical reference point for capital allocation, product development, channel strategy, and partnership evaluation.
The market has demonstrated consistent upward movement over the past five years, with total revenue climbing from approximately 2500 million USD in 2020 to 3310 million USD in 2025. This growth trajectory reflects a combination of rising household penetration, industrial water treatment mandates, and renewed commercial facility upgrades. The forecast period projects continued expansion, with market valuation expected to reach 3649.48 million USD in 2026 and advance steadily toward 5244.0 million USD by 2032. Underlying this progression is a forecast CAGR of 6.85%, a rate that signals durable demand rather than transient spikes. For executives planning multi-year initiatives, this growth curve provides a reliable scaffold for scenario modeling, capacity planning, and market entry timing.
Growth Trajectory and Structural Drivers
The sustained expansion observed between 2020 and 2025 was not accidental. It emerged from a convergence of consumer priorities, operational cost pressures, and regional infrastructure modernization. As water quality concerns gained prominence, end-users increasingly recognized the long-term economic benefits of hardness mitigation, including reduced scale buildup, extended equipment lifespans, and improved cleaning efficiency. Residential adoption benefited from heightened awareness of household appliance protection and wellness-oriented purchasing behavior. Commercial operators integrated softening systems into facility management programs to stabilize maintenance costs and ensure consistent water quality across hospitality, healthcare, and multi-unit residential properties. Industrial users, meanwhile, continued to prioritize water treatment as a component of process reliability and compliance management.
Water Hardness Removal Market
Looking ahead to the 2026–2032 forecast window, several structural catalysts will shape the pace and composition of demand. Technological refinement in resin performance, brine management, and system automation is lowering total cost of ownership while improving user experience. Energy-conscious designs are aligning softening equipment with broader sustainability agendas, making water treatment investments more compatible with corporate environmental targets. Channel evolution is also accelerating, as direct-to-consumer models, specialized dealer networks, and integrated plumbing partnerships reshape how systems are specified, installed, and serviced. These dynamics create a market environment where growth is not merely a function of unit volume but also of value-added service, differentiation, and lifecycle management.
Forecast Window and Decision-Making Implications
The 2026–2032 forecast period is particularly significant for enterprises weighing expansion, product refresh cycles, or geographic diversification. The projected escalation from 3649.48 million USD in 2026 to 5244.0 million USD by 2032 underscores a market that is broadening in both scale and complexity. For manufacturers, this implies the need to balance volume growth with margin protection, especially as competitive intensity increases and consumer expectations around efficiency and ease of maintenance rise. For distributors and service providers, the forecast highlights opportunities in installation scale, remote monitoring, and preventive maintenance contracts. For investors and corporate development teams, the trajectory points to a sector where consolidation, brand positioning, and technology differentiation will increasingly determine which participants capture disproportionate share.
Strategic planning in this environment requires more than headline figures. Decision-makers need visibility into how demand fragments across application contexts, how system types evolve in response to regulatory and consumer preferences, and how regional markets diverge in purchasing behavior, infrastructure readiness, and competitive saturation. Our research is structured to deliver this multi-dimensional view without overwhelming stakeholders with undifferentiated data dumps. Instead, the report organizes findings around operational questions: where should new capacity be directed, which product architectures align with durable demand, and how should channel investments be prioritized to maximize return in a maturing landscape?
Competitive Landscape and Strategic Positioning
The market’s growth trajectory unfolds against a backdrop of concentrated yet dynamic competition. Aggregate market structure indicates meaningful consolidation, with the top three participants collectively accounting for approximately 65.4% of revenue and the top five reaching around 78.2%. This concentration signals that scale, brand equity, distribution reach, and service infrastructure remain decisive advantages. At the same time, differentiation is intensifying as companies compete on system architecture, ease of installation, certification claims, and residential or commercial-specific feature sets.
Several established players illustrate the strategic diversity shaping the sector. Culligan International, headquartered in Illinois, maintains a broad residential and commercial presence built around cation exchange resin technology for hardness reduction, leveraging a well-recognized brand and extensive service networks. A.O. Smith Corporation, based in Milwaukee, Wisconsin, focuses on residential PRO water softeners with energy-efficient single-tank designs, aligning product development with efficiency-conscious consumer expectations. Kinetico Incorporated, operating from Newbury, Ohio, differentiates through non-electric water softeners certified for reducing calcium and magnesium deposits, appealing to customers seeking mechanically robust, low-maintenance solutions. Hellenbrand, located in Waunakee, Wisconsin, supplies both residential and commercial systems, including the ProMate EcoMax series, reflecting a portfolio strategy that spans application segments while emphasizing performance and efficiency.
These profiles are not merely company summaries; they reveal how incumbents position themselves across the value chain. Some compete primarily on brand trust and service density. Others prioritize engineering trade-offs such as energy consumption, electrical dependency, or installation simplicity. Together, they define the competitive benchmarks against which new entrants, regional challengers, and product innovators must calibrate their strategies. The report examines these positioning patterns in detail, mapping how product portfolios, channel structures, and regional footprints interact to shape share dynamics and barrier-to-entry conditions.
Report Architecture and Operational Utility
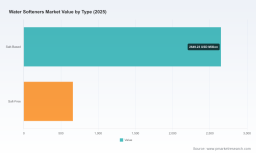
This market research publication is designed for practical application rather than passive reference. It combines macro-level market sizing with structured segmentation analysis, allowing stakeholders to trace how overall revenue translates into distinct market pathways. The report examines the market by region, by type, and by application, providing a layered view of where demand concentrates, how system preferences diverge, and which segments exhibit the strongest momentum. Rather than presenting isolated percentages or fixed monetary values for each segment, the analysis emphasizes relative scale, ordering, and strategic context so that readers can interpret where opportunities and risks are most pronounced.
The study also integrates competitive profiling, market concentration metrics, and forward-looking scenario considerations to support strategic decision-making. Readers will find structured evaluations of how leading companies position their offerings, where service and distribution capabilities matter most, and which product categories are likely to see the most intense innovation pressure. The report further addresses the operational implications of market evolution, including installation and maintenance workflows, customer retention levers, and the role of certifications and performance claims in purchasing decisions.
Water Softeners Market
By organizing intelligence around both market structure and competitive behavior, the publication enables users to quickly narrow in on the questions most relevant to their function. Executives can use the findings to inform portfolio priorities and geographic focus. Product leaders can assess architectural trends and differentiate against established designs. Sales and channel teams can align go-to-market efforts with demand patterns and regional readiness. Corporate development teams can evaluate partnership targets, acquisition rationale, and consolidation pathways within a clearly defined concentration framework.
Strategic Takeaways for 2026 Planning
As organizations finalize 2026 strategies, the water softeners market presents a landscape defined by steady expansion, concentrated competition, and increasing emphasis on efficiency, service, and differentiation. Several strategic priorities emerge from this environment. First, growth planning should account for the market’s move from early adoption momentum toward more mature, service-driven demand patterns, where installation quality, maintenance reliability, and system longevity increasingly influence repeat purchasing and referrals. Second, competitive positioning will depend on clarity of product architecture and the ability to communicate tangible benefits around scale prevention, energy use, and operational convenience. Third, channel strategy must be calibrated to regional demand behavior and to the preferences of end-users who value either integrated service relationships or streamlined purchasing experiences.
The forecast period also implies that market participants will need to manage the tension between volume growth and margin discipline. As demand broadens and competition sharpens, pricing pressure may intensify in certain segments, making value-added services, differentiated features, and efficient supply chain execution essential to sustained profitability. Leaders should also monitor how certification standards, consumer education, and regulatory expectations evolve, since these factors can accelerate adoption in some contexts while reshaping specification requirements in others.
Conclusion
The global water softeners market is advancing along a clear growth path, supported by durable demand drivers and a competitive environment where scale and differentiation both matter. The 2026–2032 forecast window offers a practical planning horizon for organizations seeking to align product strategy, channel investments, and expansion decisions with market reality. Our full research publication expands on the macro trends outlined here, providing detailed segmentation analysis, competitive profiling, regional context, and forward-looking strategic guidance that together form a comprehensive decision-support toolkit.
To access the complete dataset, segment-level evaluation, company positioning detail, and scenario-ready market projections, we invite leaders to review the full Water Softeners Market report. The complete intelligence package is structured to support both immediate 2026 planning and multi-year strategic commitments, giving stakeholders the clarity required to act with confidence in a growing but increasingly competitive market.
For detailed analysis of this topic, please visit the official page: Water Softeners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com