

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Viscose Filament Yarn Market Reaches $2.89B in 2025, Projected 5.5% CAGR to 2032

Strategic Intelligence for the Next Decade: Unlocking the Viscose Filament Yarns Market Opportunity
The global textile and industrial materials landscape is undergoing a structural transformation. As sustainability mandates tighten, supply chains reconfigure, and performance expectations rise, Viscose Filament Yarns (VFY) have emerged as a critical intermediary between traditional cellulosic manufacturing and next-generation sustainable textiles. For executives, procurement leaders, and strategic planners, understanding where this market is headed is no longer optional; it is a prerequisite for capital allocation, product positioning, and regional expansion.
PW Consulting’s latest deep-dive research on the Viscose Filament Yarns Market is designed to convert macroeconomic complexity into actionable decision architecture. Drawing on a rigorous historical baseline spanning 2020 through 2025 and projecting forward through 2032, this report offers a multi-dimensional view of value creation, competitive pressure points, and regulatory inflection moments that will define the industry over the next seven years.
The market’s trajectory signals a steady expansion path. From a global revenue baseline of approximately 2.27 billion USD in 2020, the sector has advanced through consistent year-over-year growth, reaching an estimated 2.89 billion USD in 2025. The forward-looking forecast places the market on a measured 5.5 percent compound annual growth rate trajectory, with valuations expected to surpass 3.0 billion USD in 2026 and continue a sustained upward curve toward the early 2030s. These figures are not merely historical artifacts; they encode the underlying demand resilience of textile applications, the gradual diversification into medical and industrial end-uses, and the persistent influence of regional manufacturing gravity. More importantly, they establish the scale at which competitive advantage must now be engineered.
For business leaders operating in or adjacent to this market, the strategic question is no longer whether the category will grow, but how to position within a landscape where feedstock volatility, certification expectations, trade policy shifts, and product differentiation intersect simultaneously. This research was built to answer precisely that question.
Viscose Fiber Market
Why This Research Matters for 2026 Decision-Making
The year 2026 represents a pivotal planning horizon. Companies are finalizing capacity commitments, renegotiating supplier frameworks, and aligning product roadmaps with incoming regulatory and sustainability requirements. In this environment, decision-makers need more than aggregated market size numbers. They need a structured view of how demand is distributed across end-use verticals, how regional manufacturing footprints influence pricing and supply security, and how type-level product segmentation reflects commercial priorities such as luster, dyeability, and downstream processing compatibility.
This report is engineered to support that level of operational reasoning. Rather than presenting a single-line growth narrative, the analysis connects market size evolution with the underlying structural drivers that will determine which participants capture margin resilience and which face squeeze. Readers will find a carefully designed framework for interpreting where volume concentrates, where value differentiation is emerging, and where external shocks—whether raw material price swings or trade remedy actions—can reshape short-term profitability.
Equally important, the research is designed to support cross-functional alignment. Strategy teams can use the forecast architecture to test expansion assumptions. Commercial teams can use the segmentation logic to refine positioning against competing fiber categories. Sustainability and compliance teams can use the regulatory and certification discussion to identify where traceability and certification are moving from differentiator to requirement. By integrating these lenses into one coherent intelligence package, the report reduces the risk of siloed decision-making.
Inside the Report: What the Analysis Delivers
A market study earns its value through practical utility. This report is structured to give executives a working map of the Viscose Filament Yarns landscape, not just a static description of it. The analytical content is built to support scenario planning, competitive benchmarking, and entry-or-retreat decisions across multiple dimensions.
At the core of the report is a historically grounded forecast model that traces how the market has moved from its 2020 base through the most recent baseline year and into the projection window extending to 2032. This temporal structure allows readers to evaluate whether recent growth patterns reflect cyclical recovery, structural demand shifts, or region-specific manufacturing expansion. The forecast framework is presented in a way that supports sensitivity reasoning, enabling users to test how changes in feedstock cost, demand elasticity, or trade conditions could alter outcomes.
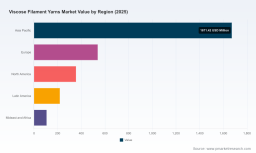
The segmentation architecture is deliberately designed to illuminate commercial reality. Readers will examine how the market divides by geography, revealing where production concentration, demand pull, and supply chain thickness shape regional competitiveness. The report also breaks down the category by product type, distinguishing between bright and dull viscose filament yarns and explaining how these variants map to different textile finishing requirements, end-market preferences, and price-performance trade-offs. In parallel, the application view provides a structured reading of where demand is anchored, with textiles representing the dominant anchor of market volume and medical, industrial, and other end-uses contributing more specialized, often higher-value demand streams.
Beyond segmentation, the report delivers operational content that leadership teams can use immediately. This includes a supplier and competitor landscape that maps out the strategic posture of key manufacturing players, an assessment of capacity and product range dynamics, and a review of recent launches, facility expansions, and production upgrades that signal where the industry is placing its bets. The study also addresses raw material exposure, particularly the role of dissolving wood pulp and other cellulosic inputs in shaping production economics. Where relevant, pricing movement and feedstock shifts are discussed as leading indicators rather than isolated events, helping readers anticipate cost pressure before it reaches the bottom line.
To support execution, the research also examines the regulatory and standards environment shaping procurement and product design. From sustainability claim verification to trade remedy investigations and regional policy direction, the report connects compliance pressure with commercial consequence. This is especially important for organizations that source across borders or plan to position certified, traceable, or recycled-content yarns as part of their differentiation strategy.
Competitive Landscape: Who Is Shaping the Market
The Viscose Filament Yarns market is defined by a concentrated yet strategically diverse competitive field. Market leadership is not uniform; it varies by region, product range, sustainability positioning, and integration depth across the cellulosic value chain. Understanding these differences is essential for evaluating supplier risk, partnership opportunities, and competitive threats.
Several large-scale producers anchor the industry. In India, Grasim Industries Limited stands out as a major viscose filament yarn manufacturer with broad denier coverage and a developing emphasis on traceable, sustainably sourced product lines. Its recent introduction of a sustainable traceable variant under its established brand family reflects a wider industry push toward verifiable sourcing and differentiated product storytelling. Across China, the competitive picture is equally significant, with multiple integrated players operating at substantial scale. Jilin Chemical Fiber Co., Ltd. represents a producer focused on expandingNext-generation grades with certified wood feedstocks and recycled cotton content, signaling that sustainability-related input strategies are increasingly becoming part of core production planning rather than peripheral branding.
Xinxiang Bailu Chemical Fiber Co., Ltd. contributes to the Chinese manufacturing base with a diversified viscose product set spanning filament, embroidery, and dyeing yarns. Yibin Grace Group Co., Ltd. has pushed further into recycled-content positioning, supported by dedicated capacity and the establishment of a recycled textile dissolving pulp facility, an infrastructure move that points to longer-term feedstock independence and circularity ambitions. Sinopec Yizheng Chemical Fibre Co., Ltd. reflects the advantage of integration within a larger state-linked industrial complex, where filament production is tied to broader dissolving pulp and chemical fiber operations. Sateri Holdings Limited operates at exceptional scale within the broader viscose fiber ecosystem and uses that scale to support filament offerings alongside staple and lyocell products, with a strong international footprint and certification-aligned supply chain.
At the premium and sustainability-led end of the spectrum, Lenzing AG remains a defining reference point for closed-loop, wood-based filament and related cellulosic yarns, particularly where high-luster, biodegradable, and performance-oriented characteristics matter. The presence of such players underscores a broader competitive dynamic: the market is not simply competing on volume, but on fiber quality, environmental credentials, processing efficiency, and downstream compatibility.
Viscose Filament Yarns Market
This competitive diversity creates both opportunity and risk. Buyers can leverage supplier variety to negotiate terms, secure supply, and access differentiated product attributes. Producers, in turn, must defend position through capacity reliability, feedstock strategy, product breadth, and increasingly, verifiable sustainability performance. The report maps these dynamics in detail so that readers can judge where consolidation pressure may intensify, where niche leadership can be defended, and where new entrants or expansions may alter regional balance.
Market Dynamics: Feedstock, Regulation, and Trade Pressures
No forecast exists in a vacuum. The Viscose Filament Yarns market is sensitive to a set of external forces that can amplify or dampen growth outcomes over the forecast period. One of the most immediate is raw material economics. Dissolving wood pulp prices have shown periodic volatility, with quarter-over-quarter movement in key sourcing regions directly affecting production cost structures. When feedstock costs rise, pricing power, margin endurance, and contract timing become critical variables. The report treats these cost dynamics as integral to market interpretation rather than as background noise, helping readers understand how input fluctuations can propagate into pricing, regional competitiveness, and demand timing.
Regulatory and policy developments are shaping the market with equal force. Sustainability claim verification is moving from aspirational positioning toward enforceable expectation. The EU Green Deal textile strategy and related Green Claims Directive implementation are accelerating demand for credibly certified viscose filament yarns, especially those supported by FSC or PEFC-aligned sourcing. For manufacturers and buyers alike, certification is increasingly tied to market access, premium positioning, and reputational risk management. The report contextualizes these shifts so that organizations can separate near-term compliance burdens from longer-term strategic requirements.
Trade policy adds another layer of complexity. Anti-dumping investigations and duty recommendations targeting viscose rayon filament yarn imports have emerged in key markets, including actions involving India and Chinese-origin supply. Where such measures progress toward formal duties, they can alter sourcing patterns, change relative price relationships, and affect the competitiveness of cross-border supply chains. These developments are particularly relevant for companies that rely on imported filament or operate in regions where trade remedy outcomes may shift the balance between domestic and overseas supply.
Finally, price movements in the Asian market illustrate how quickly regional conditions can shift. Recent pricing surges tied to cellulose feedstock volatility demonstrate that regional price signals can diverge from global averages and create short-term windows of advantage or disadvantage. By integrating these dynamics into the broader market narrative, the report gives readers a more realistic foundation for planning than a simple demand-growth storyline would provide.
How to Use This Research for Strategic Advantage
The strongest market research does not simply describe the past; it sharpens the next decision cycle. This report is intended to support a range of strategic actions. For organizations evaluating capacity expansion or product line extension, the segmentation and forecast structure provides a basis for testing where demand depth justifies investment. For procurement and sourcing teams, the regional and competitor analysis supports supplier diversification, contract strategy, and exposure management in environments where feedstock and trade conditions can change quickly.
For commercial leaders, the bright versus dull product distinction and the application mix offer a framework for aligning product attributes with customer priorities, whether those priorities center on aesthetics, dye behavior, processing efficiency, or end-use performance. For sustainability and compliance functions, the regulatory discussion helps prioritize certification pathways, traceability investments, and claims substantiation in markets where verifiable sustainability is becoming a condition of participation rather than a voluntary advantage.
Most importantly, the report supports integrated decision-making. Growth potential, competitive intensity, feedstock exposure, and regulatory direction are rarely independent. This research connects them so that executives can evaluate trade-offs more clearly, challenge internal assumptions more effectively, and align strategy across functions with a shared view of the market’s direction.
Conclusion
The Viscose Filament Yarns Market is entering a period in which scale, sustainability, and supply-chain resilience must be managed together. Historical growth has established a meaningful base, and the forward forecast points to continued expansion through the end of the decade and into the early 2030s. Yet the real strategic challenge lies beneath the headline trajectory: understanding where demand is concentrated, how competitors are positioning themselves, how feedstock and trade dynamics influence margin, and how sustainability requirements are reshaping procurement expectations.
PW Consulting’s full market research report provides the depth required to navigate that complexity. It combines historical context, forecast architecture, segmentation logic, competitive profiling, and market-dynamic analysis into a single decision-ready framework. For leaders who need to move beyond surface-level market sizing and toward targeted, evidence-based strategy, the complete study offers the intelligence necessary to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Viscose Filament Yarns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com