

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Neutron Generator Market to Reach $93.45M by 2032, 6.95% CAGR from 2025

Strategic Intelligence for the Neutron Generators Market: Navigating Growth, Regulation, and Competitive Shifts in 2026
The global neutron generators market stands at a critical inflection point as organizations across energy, security, healthcare, and advanced materials sectors increasingly rely on compact, high-performance neutron sources to drive operational efficiency and innovation. Our latest market research delivers a comprehensive, data-driven assessment of this evolving landscape, providing executives, investors, and technology strategists with the actionable intelligence needed to make informed decisions throughout the 2026–2032 forecast horizon. For enterprises evaluating capital allocation, product roadmaps, or geographic expansion, this study functions as a strategic compass, translating complex market signals into clear, executable pathways.
Executive Market Trajectory: 2020–2032 Growth Arc
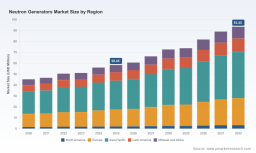
Drawing on historical performance data spanning 2020 through 2025, the market has demonstrated consistent expansion, evolving from a 45.23 million USD baseline in 2020 to an estimated 58.45 million USD in 2025. This trajectory reflects sustained industrial demand, incremental technological maturation, and broadening application portfolios across both developed and emerging economies. Looking ahead, the forecast period extends through 2032, with projected revenues climbing toward 93.45 million USD by the terminal year. The market is expected to advance at a compound annual growth rate of 6.95 percent, signaling steady, structurally supported expansion rather than speculative volatility.
For corporate planners, this growth profile carries immediate implications. Capital-intensive applications are increasingly favoring modular, high-yield neutron systems that reduce operational downtime and integrate seamlessly into existing workflows. Meanwhile, procurement cycles in regulated sectors are lengthening, demanding earlier strategic alignment between engineering teams, compliance officers, and supply chain managers. Organizations that institutionalize market intelligence now will be better positioned to anticipate demand spikes, prioritize capacity investments, and negotiate favorable terms with upstream component suppliers.
High Frequency X-Ray Generators Market
Segmentation Dynamics and Application Realities
The market structure reflects a diverse mix of deployment formats, end-use requirements, and regional maturity levels. Portable systems continue to capture meaningful share, driven by field-deployable inspection, on-site materials analysis, and mobile security screening requirements. Stationary configurations maintain strong institutional demand, particularly in laboratory environments, industrial quality assurance lines, and specialized medical research facilities where sustained output and calibration stability outweigh mobility considerations. Application demand spans oil and gas exploration, cargo and personnel security screening, academic and commercial research, as well as emerging medical and ancillary use cases. Regional consumption patterns reveal distinct maturity curves, with established industrial economies maintaining steady baseline procurement while high-growth corridors accelerate adoption through infrastructure modernization and specialized manufacturing investments.
Because segmentation boundaries increasingly overlap—portable units supporting stationary laboratory workflows, multi-application platforms serving both security and industrial inspection, and cross-border procurement channels adapting to shifting regulatory environments—a superficial view of market shares obscures the real strategic calculus. Decision-makers require granular visibility into how type preferences correlate with application intensity, how regional procurement behaviors influence pricing elasticity, and where transitional demand is creating short-term supply constraints. These are precisely the analytical dimensions addressed in depth within our report, where segment-level interactions are mapped against operational cost structures, lead-time variability, and technology adoption curves.
Competitive Landscape: Technology Differentiation and Strategic Positioning
The competitive arena features a blend of specialized technology manufacturers, established scientific instrumentation players, and research-driven innovators, each pursuing distinct value propositions and target ecosystems. Adelphi Technology, based in Redwood City, California, produces D-T (14.1 MeV), D-D (2.45 MeV), and moderated D-D thermal neutron generators tailored for industrial materials analysis, radiography, nondestructive testing, healthcare, and security applications. Sodern, headquartered in Bois-Guillaume, France, focuses on electric neutron sources and analyzers built around neutron activation principles, with particular emphasis on civil neutron tubes and generators for oil logging, waste characterization, and cross-belt analyzers used in cement, nickel, and copper processing.
Phoenix operates from Germany, supplying high-intensity neutron sources for nondestructive testing and neutron imaging across aerospace, defense, and industrial quality assurance applications. NSD Fusion / Gradel, also based in Germany, manufactures patented long-life neutron generators with operational lifetimes extending up to 20,000 hours, high specific power, and stable output suited to materials analysis, nondestructive testing, oilfield services, and security deployments. Thermo Fisher Scientific, located in Colorado Springs, Colorado, offers compact portable neutron generators such as the MP 320, P 385, and P 383, supporting elemental analysis, inelastic scattering, and both laboratory and field applications.
Recent procurement and product activity underscore how competitive dynamics are evolving in real time. Thermo Fisher Scientific integrated the Thermo Scientific Model D711 14 MeV neutron generator into new laboratory operating procedures to support student research, reflecting a broader institutional push toward accessible, education-aligned neutron capabilities. In early 2026, Uppsala University procured a 14 MeV deuterium-tritium neutron generator system model DT110.1gs for research facilities, while UKRI secured a contract for Neutron Generator Head model DT110.1gs delivery and installation, signaling sustained public-sector investment in advanced neutron infrastructure. Separately, the Hefei Comprehensive National Science Center advanced high-intensity compact D-D neutron generator technology, achieving stable yields up to 5 × 10^9 n/s with 98 percent effective operation time for neutron imaging, illustrating how regional research institutions are pushing performance thresholds that will eventually cascade into commercial specifications.
Market concentration remains moderately distributed, with the top three firms accounting for approximately 24.6 percent of collective revenue and the top five firms reaching about 32.1 percent. This fragmentation offers both opportunity and risk: new entrants and niche specialists can carve out defensible positions through application-specific engineering, while larger incumbents leverage scale, compliance infrastructure, and multi-product portfolios to consolidate share. Understanding which competitive levers are most effective in each segment—and where partnerships, licensing, or regional distribution agreements are reshaping market access—is essential for formulating durable growth strategies.
Regulatory and Geopolitical Dynamics Shaping Market Behavior
Neutron generator commercialization does not occur in a regulatory vacuum. Compliance requirements, export controls, and medical-device classification frameworks materially influence product design, sales cycles, and international market entry strategies. In the United States, electronic neutron generators are classified by the U.S. Nuclear Regulatory Commission as radiation-producing machines subject to Agreement State licensing rather than direct NRC jurisdiction. D-T neutron generators that incorporate tritium above specified activity thresholds require specific NRC or Agreement State tritium possession licenses, adding a compliance layer that affects manufacturing, handling, and end-user onboarding. High-performance neutron generators also fall under U.S. Export Administration Regulations, requiring individual validated export licenses for sales to restricted countries such as China and Russia, which directly shapes distribution planning and partner selection.
Medical applications introduce additional complexity. BNCT hospital-grade neutron generator systems are subject to Class III medical device approvals in the United States, CE Mark certification in Europe, and equivalent processes that require extensive clinical trial data. These approval pathways extend time-to-market and elevate validation costs, making early regulatory strategy a determinant of commercial viability rather than a downstream administrative step. On the international stage, neutron generators are classified as dual-use items under the Wassenaar Arrangement, subject to multilateral export licensing controls across 42 participating states including Europe, Japan, and Australia. For multinational enterprises, this means that even routine cross-border equipment transfers can trigger compliance reviews, delay project timelines, and require dedicated trade-compliance resources.
These regulatory and geopolitical factors are not peripheral concerns; they are structural inputs into pricing models, channel strategy, and risk-adjusted return calculations. Organizations that treat compliance as an afterthought often encounter costly rework, missed procurement windows, or restricted market access. By contrast, firms that integrate regulatory foresight into product architecture, supplier contracts, and international sales planning can convert compliance complexity into competitive differentiation.
What the Full Study Delivers: Operational Intelligence for 2026 Decision-Making
This market research is designed to move beyond top-line figures and provide the operational intelligence that executives need when allocating budgets, prioritizing R&D, or evaluating market-entry timing. The report covers historical performance baselines, multi-year forecast modeling, application-specific demand drivers, type-level technology maturity considerations, regional procurement behaviors, and competitive positioning across the principal market participants. It also maps regulatory touchpoints, export-control implications, and institutional procurement trends that directly affect go-to-market execution.
Neutron Generators Market
Beyond descriptive analysis, the study presents decision-oriented frameworks that help teams translate market signals into concrete actions. Readers will find structured assessments of where demand is most resilient, which technology pathways are gaining adoption momentum, how procurement timing varies across sectors, and what operational benchmarks matter most when comparing supplier offerings. The research is built to support capital planning, product strategy, sales segmentation, and risk evaluation, giving leadership teams a shared, evidence-based foundation for strategic discussion.
Because the market is evolving under the combined influence of technological advancement, regulatory change, and shifting industrial demand, partial data is rarely sufficient for high-stakes decisions. The complete report consolidates the full analytical architecture—forecast sensitivity considerations, segment correlation insights, competitive benchmark details, and procurement trend mapping—into a single resource that can be operationalized across business units.
Conclusion: Turning Market Visibility into Strategic Advantage
The 2026–2032 period will reward organizations that approach the neutron generators market with disciplined analysis, regulatory awareness, and a clear understanding of where technology, application demand, and competitive dynamics intersect. With sustained growth projected through the end of the decade, the strategic question is not whether the market will expand, but how enterprises will position themselves to capture value efficiently and responsibly. Detailed segmentation data, application-level growth trajectories, regional procurement patterns, and complete competitive benchmarks are developed in full within our comprehensive market study. For decision-makers who require precision intelligence to guide investment, product planning, and market strategy, the complete report provides the depth, structure, and forward-looking analysis needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Neutron Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com