

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ESP Market Hits $8.3B in 2025, Projected $12.79B by 2032 at 6.4% CAGR

Electrostatic Precipitators Market: Strategic Intelligence for the 2026–2032 Investment Horizon
As global industrial emissions face intensifying regulatory scrutiny and energy transition mandates, electrostatic precipitators (ESP) have evolved from conventional particulate control equipment to mission-critical infrastructure within the broader decarbonization and air quality compliance ecosystem. Our latest research publication, Electrostatic Precipitators (ESP) Market: Strategic Forecast & Competitive Intelligence 2026–2032 , delivers a rigorously modeled, commercially actionable assessment designed specifically for executive teams, capital allocators, and technology procurement leaders navigating the next multi-year cycle. This briefing outlines why this analysis is strategically indispensable for 2026 decision-making, what operational intelligence it provides, and how organizations can leverage its architecture to secure competitive advantage in a rapidly consolidating market.
Why This Research Matters for 2026 Decision-Making
Corporate strategy in environmental control technology is no longer driven by isolated compliance requirements; it is shaped by capital efficiency, supply chain localization, digital integration, and long-term asset lifecycle economics. The 2026–2032 period represents a structural inflection point where legacy ESP installations require modernization, new industrial capacity demands higher collection efficiencies, and regulatory frameworks tighten particulate emission thresholds across multiple jurisdictions. Organizations that enter this cycle with fragmented data or outdated cost assumptions risk misaligned procurement, suboptimal capacity planning, and exposure to margin compression.
Our report is engineered to close that intelligence gap. It translates historical trajectory, forward-looking growth signals, and competitive positioning into a decision-ready framework. By anchoring analysis in verified historical performance and modeling forward under multiple adoption scenarios, the study equips strategy, operations, and procurement teams with the visibility needed to time investments, evaluate supplier risk, and align technology roadmaps with corporate sustainability and compliance targets.
Market Trajectory and Forward-Looking Growth Signals
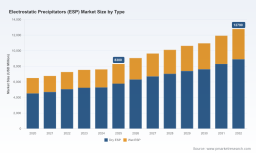
The ESP market has demonstrated consistent expansion across recent years, reflecting sustained industrial demand, upgrade cycles for existing installations, and the continued deployment of particulate control systems in power generation, heavy processing, and emerging waste-to-energy applications. The historical baseline from 2020 through 2025 shows a market that has steadily scaled, with revenue progressing from approximately USD 6.5 billion at the start of the period to roughly USD 8.3 billion by the base year. This progression underscores an entrenched demand environment rather than a transient compliance spike.
Worldwide Dry Electrostatic Precipitator Market
Forward momentum remains firmly positive. The forecast trajectory for 2026 projects revenue approaching USD 9.06 billion, followed by continued expansion through 2032, with the terminal year reaching approximately USD 12.79 billion. This path corresponds to a compound annual growth rate of 6.4 percent over the forecast window. Importantly, the growth curve is not uniform across all demand drivers; it reflects a combination of capacity additions, regulatory-driven retrofits, operator preferences for higher-efficiency configurations, and incremental adoption in sectors that previously relied on alternative filtration approaches. These dynamics create a multi-layered opportunity landscape where procurement timing, technology selection, and aftermarket service strategy materially influence total cost of ownership.
Strategic readers will note that the growth narrative is best understood not as a single-volume projection, but as a portfolio of application-specific demand pulses, regional deployment rhythms, and technology-specific replacement cycles. The full study decomposes these layers without exposing the granular splits prematurely, ensuring that interested stakeholders engage directly with the complete modeling architecture to extract the precise segmentation intelligence relevant to their operating footprint.
Market Structure, Competitive Dynamics, and Strategic Positioning
The ESP competitive environment is moderately concentrated, with the top three participants collectively accounting for approximately 38.2 percent of market revenue and the top five representing about 55.0 percent. This concentration indicates a market where scale, installed-base advantages, service network density, and proven high-efficiency collection capabilities create meaningful barriers for new entrants, while still leaving space for specialized manufacturers, regional integrators, and technology innovators to differentiate through application-specific engineering, digital control modules, and customized wet or dry ESP configurations.
Several established players illustrate the breadth of competitive strategies currently shaping the market. Babcock & Wilcox Enterprises, Inc. continues to reinforce its leadership position with an extensive installed base exceeding 5,000 systems worldwide and demonstrated high-efficiency collection performance up to 99.9 percent across wet and dry ESP platforms for utility and industrial power generation. In June 2025, the company secured more than USD 18 million in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, reaffirming the commercial importance of lifecycle rebuild programs alongside new equipment deliveries.
FLSmidth & Co. A/S has been advancing application-specific ESP solutions for cement and industrial environments, increasingly integrating AI-enhanced control systems to optimize collection performance and operational stability. In February 2025, the company expanded its service center network with a new facility in Dammam, Saudi Arabia, strengthening regional support for advanced emission control technologies, including electrostatic precipitators. This localized service expansion reflects a broader industry pattern: competitive advantage is increasingly determined by the proximity of technical support, parts availability, and predictive maintenance capabilities rather than equipment supply alone.
Valmet Oyj supplies ESP solutions tailored to pulp and paper recovery boilers, where process conditions demand robust particulate capture and integration with recovery cycles. In February 2024, the company shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler, with completion targeted by the end of 2025. Mitsubishi Heavy Industries, Ltd. has similarly extended its high-efficiency ESP footprint into large-scale industrial applications, including a September 2024 delivery of an ESP unit for a 700,000-tonne chemical pulp project in China. These engagements demonstrate how major suppliers are aligning ESP deployments with sector-specific process engineering rather than treating particulate control as a standalone commodity purchase.
Beyond these highlighted developments, the competitive field includes a broad set of specialists and industrial integrators. DÜRR AG emphasizes advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Ducon Technologies Inc. manufactures custom wet and dry ESP systems for power, cement, and steel applications. Fuel Tech, Inc. combines ESP with flue gas conditioning and NOx reduction technologies for coal-fired utilities. GEA Group AG manufactures ESP for food, pharmaceutical, and chemical industry environments. KC Cottrell, Inc. focuses on wet ESP for utility and industrial applications. Monroe Environmental, LLC provides industrial ESP solutions for air quality control. GEECO Enercon GmbH specializes in high-efficiency ESP systems for industrial and power sector emission control. Sumitomo Heavy Industries, Ltd. develops ESP integrated with flue gas treatment systems. Trion, Inc. targets commercial and industrial air filtration. Wood plc delivers ESP as part of broader power generation and environmental control system offerings.
This diversified competitive fabric matters strategically because procurement decisions increasingly weigh total value over nominal equipment price. Operators evaluate supplier track record in specific applications, availability of rebuild and upgrade programs, ability to integrate digital controls and flue gas conditioning, and capacity to support compliance with evolving emission limits. The comprehensive competitive section of our report maps these positioning dimensions across the profiled companies, enabling readers to benchmark capabilities, identify partnership or sourcing opportunities, and assess where consolidation, regional expansion, or technology differentiation is likely to reshape supplier relationships.
Structural Drivers and Operational Constraints Shaping Investment Logic
Market growth is reinforced by a combination of regulatory pressure, process modernization, and operational reliability requirements. In the United States, the EPA Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, directly accelerating ESP deployment and upgrade activity in utility environments. Alongside this, U.S. federal regulations on particulate matter emissions from industrial sources continue to compel industries to adopt ESP technologies for compliance, expanding the addressable base beyond traditional power generation.
These regulatory tailwinds interact with practical operational considerations. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment, elevating the importance of lifecycle economics and financing strategy. Electrical energy consumption in electrostatic precipitators can be substantial, with resulting high operating costs for large-scale installations, making energy-efficient design, optimized voltage control, and intelligent operational scheduling relevant to long-term profitability. Together, these factors mean that market participants cannot evaluate ESP investments purely on collection efficiency metrics; they must incorporate compliance risk reduction, maintenance exposure, energy intensity, and the potential for modular or phased deployment.
The report integrates these structural drivers into a cohesive analytical narrative, linking regulatory timelines, material and energy cost realities, and technology evolution paths to demand behavior across major application clusters. Rather than treating compliance as a static checkbox, the analysis frames ESP adoption as an ongoing capital and operational decision influenced by enforcement cadence, plant age profiles, fuel mix transitions, and the economics of retrofitting existing units versus installing new systems.
Inside the Report: Operational Content for Executive Action
This study is structured to support practical decisions rather than abstract market commentary. It provides a comprehensive map of the ESP market across technology configurations, application environments, and regional deployment patterns, with historical data and forward forecasts embedded in a consistent analytical framework. The report details revenue progression, growth drivers, constraint factors, and the interplay between regulatory mandates and operational economics, giving readers a clear view of where demand is expanding, where replacement cycles are intensifying, and where competitive competition is concentrating.
Beyond macro trajectory, the publication delivers actionable supplier intelligence. It profiles leading manufacturers and specialized OEMs, outlines their application focus, recent contract and expansion activity, and the strategic implications of their market moves. This competitive mapping is paired with an assessment of market concentration dynamics, enabling readers to understand where scale advantages matter most and where niche or application-specific suppliers can create differentiated value. The report also incorporates sector-level considerations such as material selection pressures, digital control adoption, energy consumption profiles, and compliance-driven procurement behavior, providing context that procurement, engineering, and strategy teams can apply directly to sourcing and investment planning.
Importantly, the full study is designed to be modular in use. Executives can extract high-level growth signals and strategic implications for board-level planning; procurement and engineering teams can drill into supplier capabilities and application fit; and investors or corporate development teams can assess concentration patterns, regional momentum, and the types of commercial activity—such as rebuild contracts, service network expansion, and integrated system deliveries—that signal where value is being captured in the value chain.
How to Use This Intelligence for 2026 Strategy and Sourcing
For organizations planning capital expenditures, compliance upgrades, or vendor evaluations in 2026, the strategic value of this research lies in its ability to convert market signals into operational choices. The growth path, competitive structure, and regulatory context described in the report provide a basis for timing retrofit and replacement programs, evaluating whether to prioritize efficiency upgrades or capacity additions, and selecting suppliers whose installed-base experience and service reach align with specific application requirements. The inclusion of recent contract awards, network expansions, and project deliveries offers tangible reference points for assessing supplier momentum and execution capability.
Electrostatic Precipitators (ESP) Market
At the same time, the most precise segmentation data, regional deployment splits, and application-level revenue breakdowns are reserved within the complete research package. This intentional structure ensures that the full strategic picture—including the detailed allocation of demand across technology types, end-use sectors, and geographies—is available to decision-makers who require resolution fine enough to guide licensing, sourcing, and investment commitments.
Final Perspective
The ESP market entering 2026 is defined by sustained demand growth, a moderately concentrated competitive field, and a regulatory and operational environment that rewards integrated, high-efficiency, and service-supported solutions. Our research translates these conditions into a forward-looking, decision-oriented framework that supports compliance planning, capital allocation, supplier evaluation, and long-range technology strategy. For leaders who need more than headline growth figures—who require supplier-level insight, structural driver analysis, and a forecast architecture aligned with real procurement and investment cycles—this report offers the depth and commercial relevance necessary to act with confidence. Access to the complete segmentation detail and full competitive intelligence is available through the full study, where the complete dataset and methodology can be reviewed in context.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com