

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cotton Yarn Market to Hit $117.79 Billion by 2032, Growing at 3.97% CAGR

Navigating the Cotton Yarn Market: Strategic Intelligence for 2026 Decision-Making
The global cotton yarn industry stands at a critical inflection point as we move through the mid-2020s. Shifting trade architectures, volatile raw material pricing, and aggressive capacity adjustments by key producers are redefining competitive dynamics across apparel, home textiles, and technical fabric supply chains. For executives responsible for sourcing strategy, margin optimization, and geographic expansion, relying on fragmented market signals is no longer sufficient. The Cotton Yarn Market Research report from PW Consulting delivers a rigorous, data-grounded lens into the forces shaping the sector, with a forecast horizon that extends through 2032.
This article provides a strategic preview of the study's core findings and analytical framework. It is designed to demonstrate why this intelligence matters for enterprise planning in 2026, while preserving the detailed breakdowns that justify a full review of the complete document.
A Trajectory of Measured Expansion
Over the past five years, the cotton yarn market has demonstrated resilient growth against a backdrop of supply chain disruptions and evolving consumer demand. Historical valuations show the market expanding from approximately $62.01 billion in 2020 to $89.54 billion by 2025, reflecting a compound trajectory fueled by sustained textile consumption and industrial spin capacity additions. Looking ahead, the forecast period through 2032 projects the market reaching $117.79 billion, underpinned by a steady CAGR of 3.97 percent.
These figures tell a story of incremental but consistent growth rather than hyper-expansion. For strategic planners, this trajectory signals a market where share capture, operational efficiency, and vertical integration matter more than chasing volume for its own sake. The mid-single-digit growth rate suggests that value will increasingly accrue to participants who can navigate input cost volatility, optimize blend formulations, and align production with demand pockets in high-growth geographies.
Where Value Concentrates: Yarn Types and End-Use Applications
The market's internal architecture reveals clear patterns in how revenue is distributed across product categories and final applications. Carded yarn commands the largest share of the type segmentation, followed by combed yarn, with a smaller remainder allocated to specialty and other variants. This distribution reflects the enduring demand for cost-effective, versatile yarns in mass-market garment manufacturing, while combed variants retain premium positioning for higher-count and finer textile applications.
On the application side, apparel remains the dominant end-use driver, absorbing more than half of total market value. Broader textile applications, including home textiles and industrial fabrics, represent the next significant demand pool. These structural allocations matter for procurement and product development teams because they illuminate where pricing pressure is most intense, where custom specifications command premiums, and where forward purchasing contracts can lock in favorable input costs. The full report unpacks these splits with granular segmentation that connects each category to regional production footprints and demand cycles, but the headline takeaway is clear: apparel-led consumption continues to anchor the market, while textile diversification offers incremental growth opportunities.
Geographic Concentration and the Asia-Pacific Anchor
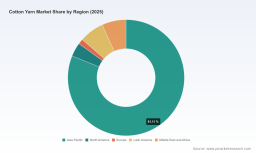
Regional dynamics in the cotton yarn market are heavily shaped by production clustering and trade flow patterns. Asia Pacific dominates the regional revenue landscape, reflecting the concentration of spinning infrastructure, deep-integrated textile ecosystems, and proximity to major apparel manufacturing hubs. Other regions, including North America, Europe, Latin America, and the Middle East and Africa, collectively account for a smaller but strategically significant portion of market value, each influenced by distinct regulatory frameworks, import dependencies, and local manufacturing competitiveness.
For sourcing managers and market entry strategists, the geographic breakdown is not merely a revenue map. It is a lens into trade policy exposure, logistics cost structures, and the relative bargaining power of regional suppliers. The complete analysis maps these dynamics against tariff regimes, local incentive programs, and shifting buyer preferences, providing the kind of regional intelligence that supports scenario planning rather than static sourcing assumptions.
Competitive Intensity and the CR5 Reality
Market concentration data underscores a landscape that is fragmented at the base but meaningfully consolidated among top-tier players. The top three competitors hold approximately 32.5 percent of total market revenue, while the top five expand that share to 42.0 percent. This structure indicates that a handful of large, integrated producers exert disproportionate influence over pricing benchmarks, capacity cycles, and export flow patterns, even as a broad base of regional manufacturers competes on cost, specialization, and localized service.
The competitive set spans well-established names across India, China, Vietnam, and Pakistan, each pursuing distinct strategic postures. In India, major players such as Vardhman Textiles Ltd., Nahar Spinning Mills Limited, Ambika Cotton Mills Limited, Sutlej Textiles and Industries Limited, KPR Mill Limited, Arvind Limited, and Grasim Industries Ltd. continue to anchor domestic spinning capacity and export supply. Fiotex Cotspin Pvt. Ltd. has drawn particular attention in 2026 for ramping production and achieving full capacity utilization while booking export orders up 40 percent through June, largely driven by demand from China. Across the broader competitive field, manufacturers are balancing volume growth with product differentiation, particularly in compact, Siro-spun, core-spun, and blended yarns that appeal to value-added textile programs.
In Vietnam, producers such as HengBang Textile Vietnam Co., Ltd. and BLUETEX VIETNAM are active in 100 percent cotton and polyester-cotton blends, supporting the country's export-oriented textile expansion. In China, large-scale operators including Weiqiao Textile Company Limited and several Shandong-based manufacturers like Weifang Jinyi Yarn Co., Ltd., Shandong Henghua Textile Co., Ltd., and Shandong Hongyan Textile Co., Ltd. maintain significant pure cotton yarn output, often leveraging automated lines to improve consistency and throughput. Nishat Mills Limited in Pakistan rounds out the competitive picture as an active regional producer navigating its own input and trade dynamics.
The strategic implication is that competitive benchmarking cannot be reduced to a single market share number. Instead, it requires understanding how each major player positions itself across count ranges, blend types, quality tiers, and destination markets. The report's competitive analysis goes beyond company snapshots to examine capacity trajectories, product Launches, and the ways in which recent operational milestones may shift regional bargaining power.
Regulation, Tariffs, and the New Cost Calculus
One of the most consequential layers of 2026 planning is the evolving regulatory and cost environment. Trade policy and input pricing are no longer peripheral concerns; they are central variables in supply chain modeling. Recent developments illustrate how quickly the operating context can change. In Vietnam, cotton yarn classified under HS codes 5204, 5205, and 5207 faces a 5 percent tariff alongside an 8 percent value-added tax, shaping the cost competitiveness of Vietnamese exports in certain destination markets.
In the United States, the Buying American Act of 2025 introduces a $0.85 per pound tariff on U.S. cotton fiber exported to non-FTA countries, while U.S.-manufactured cotton yarn is subject to a $0.15 per pound tariff. These asymmetric levies influence where sourcing teams prioritize domestic versus imported inputs and how yarn exporters evaluate destination-country incentives. Meanwhile, India's RoDTEP scheme for cotton yarn exports was reduced from 3.4 percent FOB to 1.7 percent effective February 2026, compressing a previously meaningful export incentive and prompting producers to reassess price positioning in competitive overseas markets.
Raw material pricing adds another layer of volatility. In April 2026, the Producer Price Index for raw cotton rose to 118.299 from 101.319 in December 2025, while the spun cotton yarn PPI stood at 149.159, down from 153.620 in January 2026. This divergence between upstream cotton costs and downstream yarn pricing highlights the margin sensitivity of spinners and the importance of forward hedging, blend optimization, and contract structuring. In India, cotton prices climbed to a four-year high of ₹300 per kg in May 2026, driven by strong demand from China and Bangladesh, which in turn pushed yarn prices toward the same ₹300 per kg threshold. These movements reinforce the need for market intelligence that connects commodity indices to commercial decision points rather than treating them as abstract economic indicators.
What the Full Report Delivers
The Cotton Yarn Market Research study is built to support practical, forward-looking decisions rather than simply summarizing market size. It integrates historical performance analysis, forecast modeling through 2032, segmentation-by-type and application, regional evaluation, competitive benchmarking, and regulatory context into a cohesive intelligence framework. For executives, this means the report can be used to:
- Evaluate long-term demand trajectories for different yarn categories and end-use segments
- Assess where production capacity additions are likely to alter supply balances and pricing leverage
- Understand the impact of tariff structures, export incentive changes, and value-added tax regimes on sourcing cost models
- Compare major competitors' strategic moves, including capacity expansion, product launches, and export order momentum
- Align procurement and inventory planning with commodity price signals and PPI trends
- Identify regional market opportunities and risks through a structured lens rather than anecdotal market chatter
Each section is designed to feed directly into commercial planning, whether that involves renegotiating supplier contracts, prioritizing investment in certain yarn grades, evaluating entry into new export corridors, or stress-testing margin assumptions under different input-cost scenarios.
Why 2026 Decision-Makers Need This Intelligence Now
The mid-2020s are defining a more complex operating environment for cotton yarn stakeholders. Growth is steady but not explosive, competition is intensifying among both integrated giants and specialized regional producers, and policy-driven cost shifts can quickly reorder sourcing economics. In this setting, the difference between reactive and proactive strategy often comes down to the quality of market intelligence available at the point of decision-making.
Cotton Yarn Market
A market expanding toward $117.79 billion by 2032 at a 3.97 percent CAGR may appear straightforward at the aggregate level. Yet the real strategic question is not whether the market is growing, but who will capture value within that growth and under what cost, regulatory, and competitive conditions. The answers depend on segmentation detail, regional nuance, and a clear-eyed view of how leading producers are repositioning themselves.
The complete Cotton Yarn Market Research report from PW Consulting is structured to provide that level of clarity. It offers the analytical depth required to move beyond high-level trends and into the operational and commercial specifics that guide investment, sourcing, and competitive positioning decisions. For teams preparing for the remainder of 2026 and beyond, this is the kind of intelligence that converts uncertainty into a structured basis for action.
To access the full segmentation analysis, regional breakouts, competitive profiles, and forecast detail, download the complete report from the PW Consulting site. This preview has been designed to show the strategic relevance of the study while preserving the granular data and scenario-ready analysis that buyers rely on for critical planning decisions.
Worldwide Cotton Bedsheets Market
For detailed analysis of this topic, please visit the official page: Cotton Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com