

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LPG Market Hits $162M in 2025, Poised for 5.5% CAGR Through 2032

Strategic Intelligence in the Liquefied Petroleum Gas Market Navigating Growth and Volatility Through 2032
The global Liquefied Petroleum Gas (LPG) market stands at a critical inflection point, shaped by shifting geopolitical dynamics, evolving energy security priorities, and accelerating adoption of cleaner cooking and transportation fuels. As enterprises navigate an increasingly complex macroeconomic environment, access to granular, forward-looking intelligence is no longer optionalit is a strategic imperative. Our latest market research on the LPG sector delivers precisely that: a comprehensive, data-rich blueprint designed to inform investment allocation, supply chain optimization, competitive positioning, and regulatory risk mitigation through 2032.
LPG Cylinder Market
Market Trajectory and Structural Growth Drivers
Between 2020 and 2025, the LPG market demonstrated consistent expansion, with revenue climbing from approximately 136.55 million in 2020 to 162.0 million by 2025. The momentum carries firmly into the forecast horizon, projecting sustained growth that peaks at 235.43 million by 2032. This trajectory reflects a compound annual growth rate of 5.5 percent over the 2026-2032 window, underscoring the commodity's resilience and its expanding role in the global energy mix.
Several structural forces are propelling this expansion. First, LPG continues to serve as a vital bridge fuel in regions undergoing rapid energy transition, particularly where grid reliability remains inconsistent or where governments are phasing out traditional biomass for household cooking. Second, industrial demand is being reinforced by petrochemical feedstocks and manufacturing processes that require stable, high-energy-density inputs. Third, regulatory frameworks in multiple jurisdictions are increasingly favoring lower-emission alternatives to diesel and coal, indirectly accelerating LPG adoption in both stationary and mobile applications. Finally, supply chain adaptations, including strategic inventory positioning and route optimization, are helping market participants navigate freight volatility and tariff adjustments that emerged in recent years.
It is important to recognize that this growth is neither uniform nor automatic. Regional policy shifts, fluctuating crude and natural gas pricing, infrastructure investment cycles, and evolving trade tariffs all introduce variability that can compress margins or alter demand timelines. Understanding where these variables intersect with your specific operational footprint requires more than high-level market sizing. It demands a disciplined, scenario-aware analytical framework, which our research is built to provide.
Comprehensive Analytical Coverage: What the Research Delivers
Our LPG market study is structured to translate macroeconomic trends into actionable strategic guidance. Rather than offering static snapshots, the report integrates historical performance tracking with forward-looking modeling, allowing decision-makers to stress-test assumptions across multiple time horizons. The methodology combines top-down market sizing with bottom-up segment validation, ensuring that aggregate figures are consistently anchored to real-world operational dynamics.
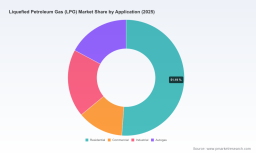
The research delves deeply into the market's compositional architecture, breaking down the universe into type, application, and geographic dimensions. On the product side, the analysis distinguishes between propane-dominant flows and butane-heavy segments, highlighting how their respective utilization patterns differ across heating, industrial processing, and blending applications. In terms of end-use, the report examines residential consumption patterns, commercial deployment trends, industrial feedstock requirements, and autogas integration in transportation fleets. Each of these segments carries distinct demand elasticities, pricing sensitivities, and substitution risks, and our analysis maps those differences explicitly rather than treating the market as a monolith.
Geographic coverage extends across major production and consumption corridors, capturing how regional supply-demand balances interact with trade flows, port infrastructure status, and localized regulatory environments. The research also addresses the competitive architecture of the market, evaluating concentration metrics, market share distribution among leading operators, and the strategic maneuvers that are reshaping value capture along the supply chain.
Beyond structural analysis, the report integrates operational intelligence that matters directly to corporate planning. This includes an assessment of raw material dependencies, particularly the role of steel in traditional tank and cylinder manufacturing, alongside emerging shifts toward composite vessel technologies. It also examines labor market constraints, as ongoing skilled workforce shortages in the broader oil and gas sector continue to influence project timelines and operational productivity. Regulatory developments are tracked with precision, including tariff carve-outs for specific LPG carriers under long-term charter arrangements, which can materially affect shipping economics and route planning.
The research further captures recent strategic moves and industry events that signal changing competitive dynamics. Divestiture activity in European distribution networks, quarterly financial disclosures from major shipping operators, and active participation in key regional trade exhibitions collectively reveal how incumbents are adjusting asset portfolios, focusing on core competencies, and exploring new geographic or product adjacencies. These developments serve as leading indicators of where capital is flowing and which capabilities are increasingly valued.
Competitive Landscape and Strategic Positioning
The LPG value chain is characterized by a concentrated yet highly differentiated competitive environment. Market structure reflects a mix of integrated energy majors, specialized shipping operators, state-backed producers, and regional distribution leaders, each pursuing distinct strategic logic. At the top of the competitive hierarchy, market concentration remains significant, with the three largest players collectively commanding a substantial share of industry revenue and the top five extending that influence further. This concentration has implications for pricing power, contract negotiation leverage, and the pace at which new entrants can achieve scale.
Leading international energy companies continue to anchor production, trading, and downstream distribution activities, leveraging diversified portfolios that span upstream extraction, midstream logistics, and retail or commercial supply networks. Their scale allows them to absorb short-term volatility, hedge across multiple commodities, and invest in infrastructure that secures supply continuity for key markets. At the same time, these integrated players are increasingly scrutinized on operational efficiency, emissions-related commitments, and capital discipline, which shapes how they prioritize LPG within broader energy portfolios.
Complementing the integrated majors is a cohort of specialized operators whose competitive advantage lies in logistical excellence and asset specialization. Global shipping companies operating modern very large gas carriers play an essential role in connecting production hubs with consumption centers, and their fleet deployment strategies, charter economics, and waiting-time management directly influence regional supply reliability. In parallel, engineering and manufacturing specialists are advancing storage and containment solutions, from conventional steel-based vessels to composite cylinder innovations that emphasize safety, weight reduction, and production scalability. These technology and logistics players may not command headline market share, but they exert outsized influence on total cost structures and service quality across the value chain.
Regional dynamics further complicate the competitive picture. In markets where state-owned enterprises or national conglomerates dominate refining, production, and retail distribution, commercial strategy often intertwines with broader industrial policy objectives, such as energy access, employment, or import substitution. Meanwhile, private distributors and marketers operating across multiple countries must continuously balance regulatory compliance, cross-border logistics, and localized customer relationships. Understanding which competitors hold structural advantages in which contexts, and how those advantages may erode or strengthen over the forecast period, is central to any credible market entry, partnership, or expansion plan.
Time-sensitive developments reinforce the need for continuous competitive monitoring. Recent divestiture activity in parts of Europe highlights how some operators are streamlining portfolios and reallocating capital toward higher-return or more strategically aligned territories. Separately, major shipping and infrastructure players are actively showcasing products and services at prominent industry gatherings, signaling product roadmap directions and partnership ambitions. Financial disclosures from key shipping operators and ongoing trade event participation collectively illustrate a market where asset optimization, regional presence, and technology differentiation are increasingly interlocking strategic priorities.
Macroeconomic and Regulatory Dynamics Shaping the Horizon
LPG market performance does not occur in isolation. Trade policy adjustments have introduced new considerations for long-term charter economics, particularly where tariff modifications have created carve-outs for specific carrier configurations. These changes can alter the cost base for certain shipping routes and influence how traders structure contract portfolios to preserve margin stability. At the same time, feedstock and production patterns in major exporting regions continue to shape global supply availability. Gulf producers have maintained substantial LPG export volumes, reinforcing the region's position as a critical supply node and reinforcing the importance of freight logistics in determining final landed economics.
Labor and skills availability remain a persistent operational variable. Industry-wide constraints on specialized talent can affect everything from vessel maintenance to terminal operations and cylinder manufacturing throughput. Companies that proactively address workforce planning, automation adoption, and process modernization are better positioned to sustain productivity even as broader sector labor conditions remain tight. On the materials side, the industry continues to navigate the balance between conventional steel-based containment infrastructure and newer composite technologies that offer production scale and design flexibility. Advances in automated manufacturing lines are expanding output capacity for certain vessel types, potentially reshaping cost curves and product availability over time.
These dynamics do not simply influence operating costs; they interact with strategic planning assumptions about capacity expansion, supplier selection, geographic prioritization, and risk hedging. A market study that treats these variables as peripheral noise misses the point. Our research embeds them directly into the analytical narrative so that strategic decisions are grounded in how the market actually behaves, not how it appears in simplified models.
Why This Research Matters for 2026 Decision-Making
As organizations finalize capital plans, evaluate partnership opportunities, and recalibrate supply chain strategies for the 2026-2032 period, the LPG market presents both meaningful opportunity and material complexity. Sustained top-line growth is supported by structural demand drivers, yet realized performance will vary sharply across segments, geographies, and operator profiles. Companies that rely on generic market narratives risk misallocating resources, underestimating regional nuances, or overlooking competitive threats that are already reshaping the landscape.
Our research is designed to close that gap. It provides the analytical depth needed to distinguish between headline growth and actionable opportunity, between apparent market strength and strategically relevant advantage. Decision-makers can use the report to refine investment theses, benchmark competitive exposure, identify segments where differentiation is achievable, and anticipate regulatory or logistics developments that may alter operational economics. By integrating historical performance, forward-looking projections, segment-level structural analysis, and current industry movements into a single cohesive framework, the study supports more confident and evidence-based strategy formulation.
Liquefied Petroleum Gas (LPG) Market
The LPG market is evolving at the intersection of energy transition, trade policy adaptation, logistics optimization, and technology modernization. Navigating that environment successfully requires more than awareness of aggregate growth figures. It requires clarity on where value is being created, which capabilities are becoming more or less valuable, and how external shocks and policy shifts will propagate through specific parts of the value chain. Our report delivers that clarity, giving enterprises the strategic intelligence they need to act decisively in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Liquefied Petroleum Gas (LPG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com