

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VNA Market Projected to Reach $0.56 Billion by 2032; CAGR 3.38%

Navigating the Vector Network Analyzer Landscape: Strategic Intelligence for 2026 Decision-Makers
Executive Perspective
In the rapidly evolving ecosystem of radio frequency testing and measurement, the Vector Network Analyzer (VNA) Market stands as a critical barometer for technological advancement and industrial capability. As organizations prepare their capital allocation strategies for the forecast period extending to 2032, understanding the nuances of this market is not merely an technical necessity but a strategic imperative. This comprehensive market research report serves as a foundational tool for executives, procurement leaders, and R&D directors who must navigate a landscape defined by consolidation, technological specificity, and shifting regional demand patterns.
The current valuation of the sector reflects a mature yet steadily growing environment. With a historical trajectory from 2020 through 2025 showing resilience despite global supply chain fluctuations, the market has established a solid baseline. Looking forward, the projected compound annual growth rate indicates a moderate but consistent expansion path. This growth is not uniform across all segments; rather, it is driven by specific high-value applications and regional hubs of innovation. For enterprise decision-makers, the value of this research lies in its ability to translate raw numerical data into actionable intelligence regarding where capital should be deployed and which technologies warrant investment.
Market Trajectory and Scale
The financial architecture of the Vector Network Analyzer Market reveals a steady climb in revenue over the past half-decade. Historical data from 2020 to 2025 demonstrates a market that has maintained stability while incrementally increasing in value. Starting from a baseline in the early 2020s, the sector has progressed to a significant valuation by 2025. This stability suggests a robust underlying demand that is less susceptible to short-term economic volatility, likely anchored by long-term infrastructure projects and defense procurement cycles.
Vector Network Analyzer (VNA) Market
Forecasting into the future, the revenue projections indicate a continued upward trend. The market is expected to surpass previous ceilings as the forecast period progresses toward 2032. This growth trajectory is underpinned by a compound annual growth rate that suggests steady accumulation of value rather than explosive, unsustainable spikes. For stakeholders, this implies a market environment where long-term planning yields better returns than speculative short-term positioning. The consistency in revenue units, measured in billions of USD, underscores the significance of this sector within the broader electronic test and measurement industry.
It is crucial for leaders to recognize that these aggregate figures mask underlying complexities. The reported total market size is the sum of diverse segments, each with its own cost structures, adoption rates, and competitive pressures. Understanding the macro numbers is the first step, but the strategic advantage comes from dissecting how these figures are composed without necessarily exposing every granular detail publicly. This report provides the framework to understand that composition.
Worldwide Vector Network Test Instrument Market
Segmentation Dynamics and Demand Drivers
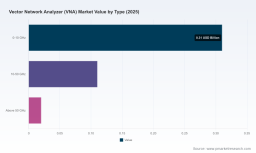
The demand for vector network analyzers is not monolithic. It is distributed across various frequency ranges and application verticals, each presenting unique opportunities and challenges. The market is segmented by type, reflecting the specific frequency capabilities required by different end-users. Lower frequency ranges continue to hold a substantial share, catering to general communication and manufacturing needs, while higher frequency segments command premium positioning due to their specialized use in advanced research and defense applications. The distribution across these frequency types indicates where the technical focus of the industry currently lies and where it is heading.
Similarly, the application landscape is diverse. Communications remain a dominant driver, fueled by the ongoing deployment of next-generation networks and the proliferation of connected devices. However, other sectors contribute significantly to the demand profile. Automotive applications are gaining traction as vehicle electronics become more complex, requiring rigorous testing protocols. Electronic manufacturing and aerospace and defense sectors also represent substantial pillars of demand, each necessitating specific instrument capabilities and compliance standards. The balance between these applications dictates the product roadmap for suppliers and the procurement strategy for buyers.
Regionally, the market exhibits a concentrated distribution of value. North America maintains a leading position, reflecting its strong presence in technology development and defense spending. Europe follows as a significant contributor, driven by its robust industrial base and regulatory standards. Asia Pacific represents a growing zone of interest, though its current share indicates room for expansion relative to the established hubs. Latin America and the Middle East and Africa constitute smaller portions of the global revenue mix, suggesting niche opportunities or emerging markets that may evolve over the forecast period. Understanding these regional weights helps organizations prioritize geographic expansion or supply chain localization efforts.
Competitive Landscape and Strategic Positioning
The competitive environment within the Vector Network Analyzer Market is characterized by high concentration and established player dominance. The industry structure suggests a barrier to entry that favors large, well-capitalized firms with extensive R&D capabilities. The concentration ratios indicate that a small number of key companies control a significant majority of the market revenue. This oligopolistic structure implies that pricing power, technological standardization, and customer loyalty are heavily influenced by the strategic moves of these top-tier entities.
Keysight Technologies, headquartered in Santa Rosa, California, remains a pivotal force in this arena. Their product portfolio, including the NA520xA PNA-X and VectorStar/Streamline families, exemplifies the high-end capabilities required to serve top-tier research and defense clients. Recent developments, such as the introduction of the NA520xA PNA-X Vector Network Analyzer with four RF sources and advanced receiver configurations, highlight their focus on enhancing measurement capability and complexity. Such product launches signal a market trend toward multifunctional instruments that can reduce overall system footprint while increasing testing throughput.
Rohde & Schwarz, based in Munich, Germany, competes with a strong emphasis on high-frequency performance. Their offerings, such as the ZNBT and ZVA series including multiport VNAs capable of operating up to 1.1 THz, target applications requiring extreme precision and frequency range. This focus aligns with the growing demand for millimeter-wave testing and advanced communication research. Their presence reinforces the necessity for buyers to evaluate frequency requirements carefully when selecting vendors, as the upper limits of operation often dictate the choice of equipment.
On the other end of the spectrum, Copper Mountain Technologies, located in Indianapolis, offers a different value proposition focused on accessibility and portability. Their 1-port and 2-port USB-powered VNAs with calibration modules cater to field applications and smaller scale operations where full-sized benchtop instruments may be impractical. This segmentation shows that the market supports both high-performance laboratory solutions and compact, cost-effective field solutions, allowing different tiers of users to access necessary testing capabilities.
Anritsu, headquartered in Morgan Hill, California, continues to expand its footprint through versatility. Their VNA Master series and VectorStar/ShockLine families provide a range of options for various testing scenarios. Recent developments, such as adding Vector Network Analyzer and Vector Voltmeter measurements to Site Master field portable instruments, demonstrate a strategy of integrating VNA capabilities into existing field tools. This convergence reduces the need for multiple devices in the field, enhancing efficiency for service providers and maintenance teams.
Industry Dynamics and Operational Realities
Navigating this market requires an understanding of the underlying dynamics that influence cost, compliance, and capability. One significant factor is the regulatory and accreditation environment. For instance, certain calibration laboratories associated with major players are accredited in accordance with the ISO/IEC 17025 international standard. This accreditation is critical for ensuring measurement traceability and compliance, particularly for industries like aerospace and defense where certification is mandatory. Buyers must consider the certification status of their suppliers and calibration services as part of their vendor qualification process.
Cost structures within the industry are influenced by technical complexity. High development and calibration costs associated with vector network analyzers require substantial investment in research and development, especially for high-frequency operation above 15 GHz. This technical barrier contributes to the market concentration observed among top players. Additionally, premium components and high-speed data acquisition systems further increase production expenses. These cost drivers affect pricing strategies and may influence the total cost of ownership for end-users, making lease-versus-buy decisions and service contract negotiations important strategic considerations.
Macro trends are also reshaping demand. Vector network analyzers are essential for precise RF testing compliance in 5G, IoT, and Industry 4.0 applications driving demand. As these technologies mature, the requirement for accurate impedance matching, signal integrity testing, and component characterization becomes more stringent. This technological dependency ensures that the VNA market remains tied to the broader growth of digital infrastructure and smart manufacturing initiatives. Organizations involved in these sectors must anticipate their testing equipment needs in alignment with their technology roadmaps.
Strategic Value of the Research Report
This market research report is designed to go beyond surface-level statistics. It provides a detailed examination of the factors that will define market success over the next several years. For executives, the report offers a structured analysis of market size, growth rates, and segmentation that supports financial modeling and budget forecasting. For technical leaders, it contextualizes product capabilities within the broader competitive landscape, helping to identify gaps in current tooling or opportunities for technology upgrades.
The report includes in-depth profiles of key companies, analyzing their recent developments and strategic focus areas. By understanding the product launches and capability additions of competitors, organizations can benchmark their own requirements and anticipate shifts in market availability. The inclusion of regulatory and cost dynamics provides a realistic view of the operational environment, helping to mitigate risks associated with compliance and procurement costs.
Furthermore, the segmentation analysis allows for targeted strategy development. Whether an organization is looking to enter a new geographic region or expand into a specific application vertical, the detailed breakdown of market splits provides the necessary context to evaluate potential returns. The report avoids generic assertions, instead offering specific insights derived from comprehensive data collection and analysis.
Ultimately, the goal of this research is to empower decision-makers with the confidence to act. In a market where concentration is high and technical barriers are significant, information asymmetry can lead to suboptimal choices. By consolidating data on market size, competitive moves, and industry dynamics into a single coherent narrative, this report reduces that asymmetry. It enables stakeholders to align their procurement strategies with market realities, ensuring that investments in vector network analysis capabilities support broader organizational goals.
Conclusion
The Vector Network Analyzer Market is poised for steady evolution through the forecast period ending in 2032. While the aggregate growth rates suggest a stable environment, the underlying segmentation and competitive dynamics offer rich opportunities for those who look deeper. The dominance of key players, the specific needs of high-frequency applications, and the regional distribution of demand all contribute to a complex landscape that requires careful navigation.
For organizations aiming to optimize their testing infrastructure or expand their market presence, access to granular data and expert analysis is indispensable. This report serves as a comprehensive guide to that intelligence. To fully unlock the strategic potential of these findings and access the detailed segmentation data, regional breakdowns, and company-specific revenue estimates, stakeholders are encouraged to consult the full report. The complete intelligence contained within provides the precision required for high-stakes decision-making in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com