

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AES Resin Market to Hit $289M by 2032, Driven by 6% CAGR

Navigating the AES Resin Market: Strategic Imperatives for 2026 and Beyond
The global landscape for Acrylonitrile Ethylene Styrene (AES) resin is undergoing a period of meaningful evolution. As manufacturers grapple with shifting feedstock costs, evolving end-use requirements, and intensifying regional demand patterns, the ability to make informed, forward-looking decisions has never been more critical. Our latest AES Resin Market research offers a comprehensive, data-driven examination of the industry, providing executives, procurement leaders, and strategic planners with the clarity needed to navigate both near-term volatility and long-term growth trajectories.
This report is not merely a retrospective compilation of figures. It is a strategic instrument designed to surface the underlying mechanics of market behavior, dissect competitive positioning, and illuminate the drivers that will shape industry outcomes from 2026 through 2032. By combining rigorous quantitative modeling with qualitative assessment of supply chain dynamics, technological developments, and application-specific demand shifts, the analysis equips decision-makers with actionable intelligence that can be immediately integrated into corporate planning cycles.
Market Trajectory and Structural Growth Dynamics
Over the past half-decade, the AES resin industry has demonstrated consistent expansion, reflecting steady adoption across multiple industrial and consumer sectors. Historical data indicates that the global market has grown from approximately 125 million USD in 2020 to an estimated 185 million USD by 2025, underscoring a resilient upward trend despite periodic supply chain disruptions and macroeconomic uncertainty. This growth has been supported by expanding production capacities, rising consumption in key application verticals, and sustained demand for weather-resistant and high-impact material grades.
Looking ahead, the forecast horizon extending to 2032 suggests continued momentum. The market is projected to reach 195.68 million USD in 2026, with steady year-over-year progression that culminates in an estimated 289 million USD by the end of the forecast window. This trajectory reflects a compound annual growth rate of 6.0 percent, a figure that signals sustained, albeit measured, expansion rather than speculative hype. For corporate planners, this level of predictability is invaluable: it enables more accurate capacity forecasting, informs investment timing, and provides a reliable baseline for scenario modeling.
The consistency of this growth path also highlights the structural attractiveness of AES resin as a material class. Its balance of impact resistance, weather durability, and processability makes it a preferred choice across diverse manufacturing contexts. As downstream industries continue to prioritize material performance and longevity, demand is expected to remain anchored by both replacement cycles and new product introductions, ensuring that the market retains a stable growth foundation.
Segmentation Intelligence: Type, Application, and Regional Architecture
Understanding where growth concentrates—and where it lags—is essential for allocating resources efficiently. The analysis segments the market across multiple dimensions, revealing how product types, end-use applications, and geographic regions interact to shape overall market behavior. While specific percentage splits and exact revenue allocations are detailed within the full report, the broader structural patterns are already evident and carry direct strategic implications.
MABS Resin Market
From a product-type perspective, the market encompasses general purpose, high impact, and weather-resistant AES resin grades. Each variant serves distinct performance requirements, and their relative demand profiles are influenced by downstream application needs, regional climate conditions, and manufacturing specifications. The balance between these categories affects pricing dynamics, production scheduling, and inventory strategies, making it critical for suppliers and buyers alike to understand how shifts in one segment ripple across the broader value chain.
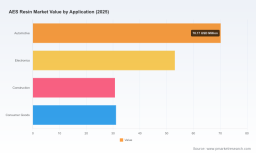
Application-level demand further illustrates the material's versatility. Automotive, electronics, construction, and consumer goods sectors each contribute meaningfully to overall consumption, but their growth rates, formulation requirements, and procurement cycles differ substantially. For example, automotive-grade resins must meet stringent durability and regulatory standards, while construction applications prioritize weather resistance and long-term outdoor performance. Electronics and consumer goods, meanwhile, often emphasize process efficiency and aesthetic consistency. Recognizing these application-specific nuances allows manufacturers to tailor production portfolios and enables buyers to align specification decisions with total cost of ownership rather than unit price alone.
Geographically, the market exhibits pronounced regional variation. Asia Pacific represents a substantial share of global consumption, driven by robust industrial activity, expanding manufacturing bases, and growing infrastructure investment. Europe and North America also maintain significant demand, though their growth trajectories are shaped by distinct regulatory environments, raw material availability, and end-market maturity. Latin America and the Middle East and Africa regions present emerging opportunities, where evolving industrial capacity and shifting procurement patterns are gradually reshaping regional demand profiles. The full report provides detailed regional breakdowns, but even at this level, it is clear that geographic strategy must be tailored rather than standardized.
Competitive Landscape: Differentiated Capabilities and Market Concentration
The AES resin sector is characterized by a moderately concentrated competitive environment, with a small group of established manufacturers holding a meaningful share of total market revenue. The analysis indicates that the top three players account for approximately 55 percent of market value, while the top five collectively represent around 65 percent. This concentration level suggests that incumbents possess substantial production scale, technical expertise, and customer relationships, but it also leaves room for specialized players to compete on grade differentiation, regional service, and application-specific solutions.
Several key companies define the current competitive architecture. Techno-UMG Co., Ltd., based in Tokyo, specializes in AES resin of the ethylene propylene rubber type, with particular emphasis on weather-resistant grades designed for automotive and outdoor applications. Nagase America LLC, operating from New York, offers multiple AES terpolymer grades that deliver strong weather resistance for industrial and automotive use, positioning itself as a reliable supplier for performance-critical specifications. INEOS Styrolution Group GmbH, headquartered in Frankfurt, produces weather-resistant and high-performance AES resins under recognized brand portfolios, serving construction, automotive, and electronics markets with a focus on consistency and material reliability.
Nippon A&L Inc., also based in Tokyo, manufactures weather-resistant AES resin grades tailored for outdoor and construction applications, addressing the need for long-term durability in exposed environments. Kumho Petrochemical Co., Ltd., a large-scale producer in Seoul, maintains integrated capacity spanning general purpose and high-impact grades, enabling it to serve broad demand profiles with operational flexibility. JSR Corporation, another Tokyo-based supplier, provides AES resin for styrenic polymer alloys and specialty applications, supporting customers who require customized material behavior. Chi Mei Corporation, located in Tainan, Taiwan, stands as a leading producer with a focus on high-impact and general-purpose variants for automotive and consumer goods, reinforcing the region's importance as both a production hub and a demand center.
These companies illustrate the diverse strategic pathways within the market. Some compete on scale and integrated production, others on grade specialization and regional service, and still others on brand reputation and application-specific technical support. For buyers, this diversity creates options but also requires careful evaluation of supplier capabilities, quality consistency, and long-term reliability. For competitors, it underscores the importance of clear positioning, whether through cost leadership, product differentiation, or customer intimacy.
Raw Material Dynamics and Supply Chain Volatility
No analysis of the AES resin market would be complete without addressing the raw material environment that underpins production economics. Feedstock pricing, supply availability, and regional cost structures directly influence manufacturing margins, pricing strategies, and ultimately, market competitiveness. Recent industry observations highlight the dynamic nature of this environment and the need for proactive supply chain management.
Global acrylonitrile prices have shown notable movement, with increases of 3 to 5 percent across most regions during the first quarter of 2026, driven primarily by rising propylene feedstock costs. In the United States, the situation intensified further, with acrylonitrile prices surging by over 21 percent in late March 2026 as global inventories declined sharply and upstream feedstock availability tightened. These movements illustrate how quickly cost pressures can materialize and how regional factors can amplify or moderate price trends. In contrast, acrylonitrile pricing in India reached approximately 1038 USD per metric ton in September 2025, reflecting moderate growth supported by relatively steady supply chain conditions. This divergence across regions emphasizes that procurement strategies must be geographically informed rather than uniformly applied.
AES Resin Market
On the ethylene propylene rubber side, price trends have followed a different pattern. In Northeast Asia, EPDM rubber prices declined by 6.5 percent to around 2.88 USD per kilogram by May 2026, reflecting stable supply and moderate downstream demand. Meanwhile, in South America, EPDM rubber prices fell even more sharply, dropping 15.8 percent to approximately 2.93 USD per kilogram during the same period, as reduced industrial demand exerted downward pressure. These contrasting movements highlight the importance of monitoring regional feedstock markets in parallel, as cost advantages in one area can be offset by disadvantages in another, and as production location decisions increasingly depend on total input cost profiles rather than isolated commodity prices.
For manufacturers, these dynamics create both risk and opportunity. Effective hedging strategies, flexible sourcing arrangements, and proactive inventory management can mitigate exposure to sudden price swings. At the same time, companies that anticipate feedstock trends and align production planning accordingly can protect margins and maintain competitive pricing even in volatile periods. The report's detailed analysis of raw material dynamics provides the context needed to develop such strategies with confidence.
Report Architecture: How the Analysis Supports Execution
The AES Resin Market research is structured to translate complex industry data into practical decision support. It begins with a comprehensive market overview that establishes historical context, defines the scope of analysis, and outlines the methodological framework used to generate forecasts. From there, the report progresses into detailed segmentation analysis, examining type, application, and regional dimensions with sufficient granularity to support targeted strategic planning.
Competitive profiling forms another central pillar of the study. Each key company is evaluated not only on scale and product portfolio, but also on strategic positioning, regional presence, and likely response patterns to market shifts. This approach helps readers understand not just who the players are, but how they compete and where vulnerabilities or opportunities may emerge. The report also incorporates supply chain and raw material analysis, linking feedstock trends to production economics and pricing behavior, so that procurement and operations teams can align their strategies with realistic cost expectations.
Beyond descriptive analysis, the study includes forward-looking scenario considerations that account for potential variations in demand growth, raw material availability, regulatory developments, and technological adoption. These scenarios are designed to help organizations stress-test their assumptions and prepare for multiple plausible futures rather than betting on a single trajectory. The full report also provides structured data tables, trend visualizations, and interpretive commentary that together enable both high-level strategic discussion and detailed operational planning.
Strategic Takeaways for 2026 Decision-Making
As organizations finalize their 2026 plans, several strategic priorities emerge from the current market landscape. First, capacity and production planning should be aligned with the steady growth trajectory observed in the forecast period, while remaining flexible enough to accommodate regional demand fluctuations and application-specific shifts. Second, procurement strategies must account for the volatility inherent in raw material markets, particularly for acrylonitrile and related feedstocks, and should incorporate diversified sourcing where feasible. Third, competitive positioning should be sharpened through clear differentiation, whether by grade specialization, regional service capability, or application-focused technical support, since price competition alone is unlikely to sustain advantage in a moderately concentrated market.
Finally, cross-functional coordination between procurement, production, sales, and strategy teams will be essential. The interplay between feedstock costs, regional demand patterns, and product specification requirements means that siloed decision-making can easily lead to suboptimal outcomes. An integrated view, supported by the kind of comprehensive analysis provided in this report, enables organizations to anticipate changes, respond faster, and capture value that less prepared competitors may miss.
The AES resin market is not defined by sudden disruption, but by steady evolution, regional complexity, and the continuous refinement of material performance expectations. Organizations that invest in understanding these dynamics today will be better positioned to make confident decisions tomorrow. The complete market research report offers the depth, structure, and actionable detail needed to turn that understanding into strategy. We invite you to explore the full analysis and access the complete dataset, segmentation breakdowns, competitive profiles, and forward-looking scenarios that can inform your next strategic move.
For detailed analysis of this topic, please visit the official page: AES Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com