

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
TVM Market Poised for 5.75% CAGR, Hitting USD 271.4M by 2032 — PW Consulting Insight
By pmarketresearch, 2026-07-08
Transportation Ticket Vending Machine (TVM) Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused preview of our full Transportation Ticket Vending Machine (TVM) Market study — designed to inform executive decisions in 2026. This “trailer” synthesizes the research’s most actionable themes and signals while intentionally withholding the full granular segmentation data so decision-makers must consult the full report for operational roll‑out level figures. Below you will find a concise, decision‑centric synthesis of market size and trajectory, competition dynamics, regulatory and operational forces shaping buying choices, and the practical tools the full report provides to accelerate procurement and deployment decisions.
Transportation Ticket Vending Machine (TVM) Market
Market snapshot: size, shape and trajectory
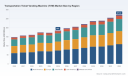
Viewed from our base year, 2025, the TVM market has exhibited consistent expansion through the early 2020s. After recovering from pandemic-era disruption, the global market reached a clear inflection during 2023–2025 and continues to expand into the latter part of the decade. Our model (base year 2025) projects a compound annual growth rate (CAGR) of 5.75% over the 2026–2032 forecast window, driven by sustained investments in public transport modernization, migration from legacy cash systems to card- and account-centric fare collection, and targeted rollouts tied to major infrastructure projects.
Transportation Ticket Vending Machine (TVM) Market
Key anchor points from our market model (USD, Million) illustrate the recovery and growth pattern: the market moved from the low hundreds in 2020 to a stronger baseline in 2025, and the forecast shows steady growth through 2032 as operators accelerate modernization and adopt enhanced payment ecosystems. These topline trends matter for 2026 budgeting cycles: procurement teams should plan for continued healthy demand for durable, interoperable TVMs that support contactless and account-based travel workflows.
Transportation Ticket Vending Machine (TVM) Market
Why this study matters to 2026 corporate decisions
- Procurement timing and CAPEX profiling: The market’s multi‑year growth profile means that delaying major procurements can expose operators to later price inflation, longer lead times, or mismatches with evolving payment standards. The report quantifies the window where replacement cycles and major new-system deployments overlap, helping you prioritize CAPEX in 2026.
- Vendor selection and negotiation leverage: With market concentration metrics indicating a moderate level of supplier consolidation, buyers can use our vendor benchmarking to identify specialization pockets (e.g., outdoor hardened units, account‑based backends, high-capacity ticket encoding) and craft RFPs that extract competitive pricing without sacrificing long‑term service guarantees.
- Total Cost of Ownership (TCO) orientation: Our TCO frameworks go beyond unit price to capture lifecycle costs — maintenance contracts, remote monitoring, cash handling risk, and software upgrades — enabling CFOs to shift budgeting from capital spikes to predictable OPEX where appropriate.
- Compliance and interoperability risk mitigation: The report maps current payment standards adoption and provides checklists to ensure cEMV/contactless compliance and interoperability with mobile wallets and account-based systems — critical inputs for 2026 deployments to avoid stranded assets.
Competitive landscape — what matters to buyers
The TVM supplier landscape combines well-established transport systems integrators, specialist vending manufacturers, and station‑equipment incumbents. Our competitive profiles highlight differences that matter for procurement and operations:
- Scheidt & Bachmann GmbH (Germany) — strength in full‑service stationary TVMs engineered for both account‑based and card‑centric fare systems. Their offerings emphasize multi‑payment support, including cash and cEMV, and robust paper ticket printing. For operators prioritizing maturity and field-proven engineering, they represent a low‑risk option for larger station deployments.
- Flowbird SAS (France) — offers modular, scalable terminals that focus on broad payment compatibility and media encoding capacity. Their product architecture favors operators who need flexible configurations and integration with municipal or regional fare systems, and they are often selected where modularity and rapid integration are procurement priorities.
- AEP Ticketing Solutions (Italy) — positioned around touch‑centric self‑service kiosks with smart‑card and magnetic ticketing capabilities. Their systems appeal to networks moving from manual ticketing to integrated electronic ticketing while preserving legacy media compatibility.
- INIT Innovations in Traffic Systems (Germany) — integrates TVMs as part of a wider station and fleet ecosystem, emphasizing multi-channel sales (pre‑sale/online) and contactless/mobile wallet acceptance. INIT is attractive to operators seeking platform continuity across ticketing, vehicle, and station systems.
- AMCO SA (Greece) and Sigma S.p.A. (Italy) — specialize in outdoor‑capable, ruggedized TVMs and automatic vending for local rail systems. Their product design choices are targeted at operators with high exposure to harsh environments or outdoor stop installations.
- DUCATI Energia and OMRON — bring strengths in integrated station equipment and solution engineering, useful where TVMs must tie into larger station automation or reservation workflows.
From a strategic perspective, buyers should map supplier capabilities to three procurement axes: (1) payment and backend interoperability, (2) physical environment and lifecycle resilience, and (3) service and data‑driven support models. Our CR3 and CR5 metrics show a moderate concentration among top suppliers — enough to create differentiated supply choices but not so consolidated as to eliminate competition. Use the report’s vendor scorecards to align supplier selection to the axes above and to short‑list partners for pilots and scaled rollouts.
Market dynamics shaping 2026 decisions
- Payment standardization is now a procurement must: cEMV and contactless payment standards have moved from “best practice” to operational requirement for the majority of major transit operators. Ensuring TVM suppliers meet these requirements is table stakes.
- Cashless acceleration and operational impacts: Operators are balancing capex for new cashless-capable machines with reduced on‑site staffing: TVM adoption can lower station personnel requirements substantially, creating both cost savings and service-channel shifts that must be managed (e.g., customer‑assistance kiosks, remote helpdesks).
- Maintenance and reimbursement models: Many authorities now offset TVM maintenance via farebox revenues or government subsidies. The report analyzes common contract structures and suggests service KPIs and escalation clauses that protect operators from excessive downtime or cash‑handling exposure.
- Deployment examples and momentum: Recent rollouts and contracts — from municipal launches to agency procurements — exemplify how operators are specifying multi‑language touchscreens, mobile app‑integration, and broad payment acceptance. These practical examples are used in the report as templates for RFP language and acceptance testing.
- Operational risks: Expect persistent pressure around cybersecurity for payment systems, spare‑parts lead times, and warranty/service alignment. The report includes mitigation levers and vendor contract clauses tailored to these risks.
What the full PW Consulting report delivers (practical, operational, ready-to-use)
Our full market study is structured to move you from strategic understanding to procurement and execution. Highlights include:
- Multi‑year market models (historical and forecast) with scenario analysis to stress‑test your procurement windows against alternative demand trajectories.
- Vendor scorecards and feature matrices that map suppliers to functional needs (payment, media support, outdoor rating, accessibility, integration capability).
- TCO and ROI calculators you can adapt with local labor, cash‑handling, and maintenance cost inputs; these models reveal breakeven timing for cashless migration versus hybrid strategies.
- Standardized RFP and contract language, including service levels, warranty terms, cybersecurity obligations, and spare‑parts commitments — ready to incorporate into 2026 tendering processes.
- Deployment playbooks and pilot evaluation frameworks with measurable acceptance criteria, KPIs for uptime and transaction reliability, and escalation paths for integration issues.
- Regulatory compliance checklists for payment standards and accessibility, plus a risk register with mitigation options for supply chain and field support challenges.
Practical next steps for 2026 decision-makers
- Shortlist and pilot this year: Use the vendor scorecards to run a two‑vendor pilot for high‑impact stations and bus interchanges. Measure payment interoperability and customer‑journey metrics over a 6–12 month window.
- Capitalize on funding windows: Align procurements with subsidy and capital planning cycles; the forecasted growth environment favors signing early to lock favorable prices and lead times.
- Shift vendor contracts toward performance: Negotiate outcome‑based SLAs tied to uptime, transaction rates, and remote resolution times rather than purely hardware replacement metrics.
- Embed cyber and payments audits: Include independent cEMV and contactless compliance testing as part of procurement acceptance. Ensure mobile wallet and account‑based integrations are validated end‑to‑end.
Closing: how to use this preview
This preview is a strategic guide — it identifies where the value and risk are concentrated for 2026 TVM decisions and shows how to convert market momentum into measurable procurement advantage. For detailed, line‑by‑line segmentation, granular regional and application roll‑ups, proprietary vendor scoring, and downloadable procurement templates and TCO models, access the full Transportation Ticket Vending Machine Market report on our website. The full dataset and playbooks are designed to be operationally prescriptive for executives and procurement teams preparing for 2026 deployments.
Contact PW Consulting to schedule an executive briefing or a tailored workshop to translate the study’s findings into a prioritized 12–24 month implementation roadmap.
For detailed analysis of this topic, please visit the official page: Transportation Ticket Vending Machine (TVM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Heated Windshields Market to Reach USD 3,118.9 Million by 2032 at 7.35% CAGR | PW Consulting
By pmarketresearch, 2026-07-08
Heated Windshields Market: Strategic Intelligence for 2026 Decision-Making
As vehicle electrification, advanced driver assistance systems (ADAS), and rising expectations for occupant comfort reshape automotive architecture, heated windshields have moved from a comfort accessory to a strategic component of vehicle design. PW Consulting’s new Heated Windshields Market study—anchored on a 2025 base year and forecasting through 2032—translates that transformation into a practical, decision-ready intelligence package for executives planning moves in 2026 and beyond.
Heated Windshields Market
Macro snapshot: scale, trajectory, and concentration
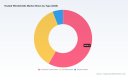
The global heated windshields market has expanded steadily through the early 2020s and enters 2026 from a position of maturity into accelerated adoption. Our topline metrics (all values in USD Million) show the market rising from approximately 1.52k in 2020 to roughly 1.89k in 2025, with a compound annual growth rate of 7.35% projected over the upcoming forecast horizon (2026–2032). Under our base scenario the market passes the 2.0k mark in 2026 and approaches 3.12k by 2032—illustrating a durable, multi-year expansion driven by safety regulations, EV thermal-management requirements, and premiumization of vehicle comfort.
Heated Windshields Market
Market structure is moderately concentrated: the three largest players control a majority share, while the top five account for near seven-tenths of the market. This concentration profile creates both barriers and openings—scale matters for OEM contracts, but technological differentiation and focused niche plays remain viable routes to meaningful revenue.
Heated Windshields Market
Why this report matters for 2026 strategies
- Timing for procurement & integration: 2026 is a pivotal year for series introductions and EV platform rollouts. Our study pinpoints where heated windshield technologies intersect with battery thermal management, HVAC design, and ADAS sensor integration—helping sourcing and engineering leaders prioritize supplier qualification timelines.
- Regulatory and safety-driven adoption: With regionally specific regulations and stringent safety standards pushing visibility technologies, manufacturers and Tier suppliers must align product development roadmaps with compliance timelines. The report translates regulatory signals into commercial impact scenarios, enabling executives to prepare capital and production plans with greater confidence.
- Investment and M&A planning: Investors and corporate development teams use the forecast to size target segments, stress-test valuation assumptions under different adoption curves, and identify acquisition candidates that offer accelerants in film-based heating, low-voltage systems, or ADAS-compatible glazing.
- Cost-to-serve and margin optimization: Raw material dynamics—most notably fluxes in silica and soda ash—drive glass production costs. Our practical cost models help C-suite leaders anticipate margin pressure and evaluate pass-through strategies or vertical integration options.
What the PW Consulting study delivers (practical, executable content)
- Topline market forecast (2020–2032) with scenario analyses calibrated to EV penetration, regulatory adoption, and raw material swings.
- Commercial playbooks for OEMs, Tier glaziers, and aftermarket participants: supplier selection criteria, performance-spec templates, and contract clauses to protect against warranty and delamination risks.
- Technology deep-dive: comparative performance mapping across conductive coatings, film-based heating, laminated integration, and low-voltage architectures—framed against unit energy consumption, defogging speed, and ADAS sensor compatibility.
- Go-to-market tools: distributor and installation channel assessments, pricing ladders, and an ROI calculator for retrofit and OEM programs.
- Regulatory matrix and compliance roadmap: a region-by-region heatmap of safety and equipment mandates, with recommended timing for certification and homologation activities.
- Commercial diligence templates for PE and strategic buyers: supplier scorecards, customer-concentration risk metrics, and post-acquisition integration checklists.
Note: in line with our “trailer” approach, the above describes the actionable components without reproducing the report’s granular segment tables and pricing schedules, which are available in full in the source study.
Competitive landscape — who’s shaping the market
The heated windshield value chain is dominated by established global glass-makers and specialist integrators. Leading firms combine scale manufacturing, global OEM relationships, and continuous product innovation. Our report profiles each of the major incumbents and synthesizes strategic implications for 2026:
- AGC Inc. (Tokyo, Japan) — AGC’s emphasis on transparent film-based systems and energy-efficient thermal control is directly targeted at EV manufacturers seeking minimized parasitic loads. Their 2025 launch of a next-generation transparent-film heated windshield signals a push to be the preferred partner on low-energy platforms.
- Saint-Gobain Sekurit (Courbevoie, France) — With a portfolio focusing on electrically conductive glass that supports rapid defogging and safety-centric performance, Saint-Gobain’s 2025 product optimized for autonomous sensor performance exemplifies the integration of glazing with ADAS validation needs.
- Nippon Sheet Glass / Pilkington (NSG Group, Tokyo/St Helens) — NSG Group has doubled down on smart solutions and solar-control technologies, positioning heated windshields as part of a broader thermal-comfort strategy—important for OEMs balancing cabin cooling and heating loads in EVs.
- Fuyao Glass & Xinyi Glass (China) — These groups emphasize cost-efficient, durable heated windshields and low-voltage options, respectively—critical in high-volume programs where unit cost and supply proximity are decisive.
- Guardian Glass (Auburn Hills, US) & Omni Glass & Paint (Oshkosh, US) — Guardian contributes to mainstream automotive portfolios, while Omni Glass & Paint captures niche OEM and commercial vehicle opportunities with custom solutions for heavy-duty and specialized equipment.
Market dynamics are active: in 2025 several incumbents introduced next-generation offerings—AGC’s transparent film-based product (Mar 2025), Saint-Gobain’s ADAS-optimized system (May 2025), and NSG’s solar-control windshield innovation (Jun 2025)—indicating a competitive tempo in both materials science and systems integration. For 2026, the strategic question for suppliers is not merely product performance, but demonstration of system-level value to OEM battery and ADAS teams.
Industry dynamics, risks and levers
- Regulatory tailwinds: Safety rules and fleet regulations are practical levers. Some jurisdictions already mandate electrically heated windshields for heavier trucks, and EU safety frameworks continue to favor visibility-enhancing technologies. These forces create a predictable base demand for commercial vehicles and fleet replacements.
- Raw materials and cost volatility: Glass production relies on silica, soda ash and other inputs whose price swings affect gross margins. Our sensitivity analysis shows that even modest raw material inflation can compress supplier margins unless offset by efficiency gains or contractual hedges.
- Technology and integration risk: The rising importance of ADAS requires heated windshield solutions that do not degrade sensor performance. Solutions that combine defogging, deicing, solar control, and sensor transparency will command premium positioning—but failing to certify early can exclude suppliers from program-level awards.
- Channel and aftermarket considerations: While OEM programs drive scale, aftermarket and retrofit channels remain attractive for specialized applications (commercial, heavy equipment, and regional climates). Our go-to-market scenarios quantify the tradeoffs for 2026 market-entry plays.
How to use this intelligence in 2026
- OEMs: Use the report’s integration checklists to validate supplier R&D roadmaps against vehicle architecture and ADAS validation timelines. Prioritize partnerships with glazing suppliers that can demonstrate low-energy heating and sensor transparency under lab and field conditions.
- Tier suppliers: If you manufacture conductive coatings, films, or laminated assemblies, deploy the supplier scorecard in the report to benchmark where to invest (capacity, automated assembly, or certification) to win 2026 platform awards.
- Investors: Leverage the forecast and sensitivity scenarios to stress-test deal models; focus on targets with demonstrable cost structures and defensible technology IP, as market concentration favors scale but niches remain for differentiated players.
- Policy makers & fleet operators: Use the regulatory impact mappings to align procurement cycles and retrofit programs that maximize safety gains while controlling lifecycle costs.
Methodology & credibility
The study synthesizes primary supplier interviews, OEM procurement data, material cost indices, and bottom-up unit modeling. Base year data is anchored to 2025 and the forecast window extends to 2032 under multiple scenarios. For readers who require granular regional, type, and application breakdowns—including the full tables, supplier scorecards, and detailed pricing models—these are deliberately reserved to the full report to preserve the integrity of proprietary inputs and to ensure actionable uptake by commercial teams.
Next steps
For executives drafting 2026 budgets, negotiating supplier contracts, or evaluating strategic investments in glazing and thermal solutions, the PW Consulting Heated Windshields Market study provides both the strategic framing and the operational tools to move from analysis to execution. Access the full report to retrieve the detailed segment tables, supplier maps, and downloadable decision-support tools that convert this high-level intelligence into winning commercial actions.
For detailed analysis of this topic, please visit the official page: Heated Windshields Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Vibrator Market to Expand at 4.8% CAGR Through 2032
By pmarketresearch, 2026-07-08
Concrete Vibrator Market: Strategic Brief for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concentrated strategic preview of our Concrete Vibrator Market research — designed to equip executives, product leaders, and corporate development teams with the insights required to make confident 2026 investment and operational decisions. The market has evolved beyond a simple equipment play; product architecture, ergonomic design, electrification, regulatory compliance and channel economics now determine winners. This brief synthesizes the research’s macro view, competitive dynamics, regulatory and innovation vectors, and the practical, executable intelligence contained in the full report — while preserving the granular segment tables and company-level revenue breakdowns for subscribers.
Concrete Vibrator Market
Why this market matters in 2026
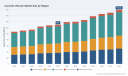
The global concrete vibrator market reached USD 130.0 Million in 2025 (base year) after steady growth through the 2020–2025 period, and our forecast model projects expansion at a compound annual growth rate (CAGR) of 4.8% through 2032, reaching roughly USD 180 Million by the end of the forecast window. That trajectory reflects a combination of infrastructure refresh cycles, increased construction activity in selected markets, and a technology shift toward electrified, ergonomic and modular solutions that reduce labour intensity and improve quality control on site. For 2026 decision-makers, the implications are simple: product and channel strategies that align with these underlying drivers can convert moderate market growth into outsized returns.
Concrete Vibrator Market
Macro dynamics shaping opportunity
- Electrification and cordless mobility: Battery-powered and cordless backpack units have moved from niche to mainstream in innovation roadmaps, driven by site cable management concerns and a preference among contractors for cordless tooling systems. This change elevates battery-pack supply chains and creates cross-sell potential with power-system OEMs.
- Performance differentiation through frequency and control: High-frequency platforms with variable-speed control enable better consolidation performance across diverse concrete mixes. Variable-speed control also supports energy efficiency and operator safety compliance, making it a fast-emerging feature premium buyers will pay for.
- Ergonomics and modularity: Reduced weight, improved ergonomics and interchangeable shaft/head systems are changing replacement cycles and aftermarket revenue dynamics. Modular systems expand addressable use-cases and simplify rental/dealer stocking strategies.
- Regulatory and certification thresholds: Market access increasingly depends on international certifications and safety approvals. CE marking and similar approvals are gating factors for growth in developed markets, affecting product development timelines and go-to-market sequencing.
- Market structure and concentration: The market exhibits moderate concentration. The top three and top five incumbent groups provide meaningful competitive anchors, but a long tail of regional and specialist manufacturers keeps pricing pressure and innovation incentives high.
Competitive snapshot — strategic positions to watch
Our analysis covers global OEMs, specialist manufacturers and adjacent-tool incumbents that have recently expanded into concrete consolidation. Several strategic patterns stand out across the competitor set:
Concrete Vibrator Market
- Systems incumbents pursuing electrified mobility: Established manufacturers are launching high-frequency internal vibrators and cordless backpack models to capture demand among contractors who prefer reduced cable clutter and higher mobility on site. These offerings target a higher-margin segment of the market and align with broader electrification trends across construction equipment.
- Ergonomics and operator-first design: New platform iterations emphasize lighter weight, better handling and reduced vibration transfer to operators. Ergonomics has emerged as a purchase driver for mid-to-large contractors that quantify safety and productivity gains.
- Modular and interchangeable architectures: Suppliers emphasizing interchangeable shafts and multiple head options reduce the number of SKUs dealers must carry, supporting rental strategies and enabling faster fleet customization.
- Compliance-driven market entry: Recent certifications and market-specific launches demonstrate a strategic focus on regulatory-compliant entries into high-value regions; this is a necessary investment for suppliers serious about scale.
Representative entrants and their strategic plays (high-level):
- A group of legacy construction-equipment OEMs has moved to high-frequency internal platforms and battery-backed backpack units to defend share and pursue higher ASPs through technology bundling.
- Specialist manufacturers continue to compete on SKU breadth, flexible shaft offerings and OEM supply partnerships, maintaining relevance in regional markets and the rental channel.
- New and adjacent-tool entrants are leveraging cordless tool ecosystems to cross-promote battery systems and accessories, creating potential channel conflict but also cross-market synergies.
Recent moves and what they signal
- Multiple product launches in 2025–2026 show suppliers racing to commercialize electrified, high-cycle and ergonomically refined platforms. These are not incremental updates; they change procurement economics on job sites with constrained labour and strict timeline penalties.
- Certification wins in late 2025 and early 2026 underline the transactional importance of regulatory compliance for EU market access — a requirement that changes product release sequencing and distribution strategy.
- Platform launches at major trade shows mark a shift to system-level selling: tool + powerpack + service contracts — increasing lifetime revenue per customer if suppliers can unlock aftermarket service economics.
Practical implications for corporate strategy in 2026
- Product roadmap prioritization: If your business competes in internal vibrators or portable consolidation tools, prioritize investments in high-frequency motors, variable-speed control, battery-integration and ergonomic design. Time-to-market for certified variants will be a competitive differentiator in key buyer geographies.
- Channel & go-to-market alignment: Reposition channel incentives to support rental houses and dealer service capabilities. Rental penetration materially alters replacement cycles and increases the value of durable, serviceable designs.
- Aftermarket and service strategy: Build warranty and service propositions tied to preventive maintenance and quick-change modular components. Aftermarket margins can offset initial price competition in new product launch phases.
- M&A and partner criteria: Look for targets that add capabilities in battery systems, ergonomics engineering, certification track record, or dealer footprint in high-growth local markets. Smaller specialist OEMs with strong rental or dealer relationships are attractive tuck-in candidates.
- Supply chain resilience: Secure alternate sourcing for key subsystems (motors, battery packs, flexible shafts) and de-risk logistics for components subject to trade-policy or tariff exposure.
Risk factors and mitigants
- Price competition from low-cost manufacturers: Maintain a clear product differentiation and service play to protect margins; compete on total cost of ownership rather than unit price.
- Certification and regulatory delays: Proactively map certification timelines into product development and pre-market investments to avoid lost selling seasons in regulated markets.
- Channel fragmentation: Simplify SKUs where possible and invest in dealer training and digital ordering to reduce friction and inventory costs.
- Technology substitution: Monitor adjacent consolidation technologies and materials innovation that may change consolidation requirements; retain R&D optionality to pivot motor and shaft designs.
What the full PW Consulting report delivers (practical contents)
- Proprietary market model (2020–2032) with baseline, upside and downside scenarios driven by construction cycles and product-adoption curves.
- Competitive benchmarking by product architecture, channel strategy, certification status and aftermarket model.
- Detailed go-to-market playbooks for launch, dealer enablement, rental partnerships and OEM alliances.
- Pricing and margin matrices, including suggested pricing ladders for electrified vs. legacy platforms and regional go-to-market sensitivity analyses.
- Supply-chain heat map identifying critical component risk and recommended nearshoring/dual-sourcing actions.
- M&A target shortlists and valuation frameworks tailored to strategic buyers.
- Primary interviews with contractors, rental operators and dealers that validate feature willingness-to-pay and procurement preferences.
- Regulatory tracker and certification timelines for major markets, including EU compliance checklists and recommended testing roadmaps.
Note: this preview deliberately omits the granular regional, type and application revenue splits and individual company revenue breakdowns included in the full dataset — those tables, transaction views and downloadable models are available only in the complete report.
Recommended next steps for executives
- Secure the full PW Consulting report and Excel model to access the granular segmentation, dealer maps and company revenue benchmarks needed for actionable planning.
- Convene a cross-functional 90-day “market capture” sprint: product, supply-chain, sales and finance — with charter to define a launch sequence for an electrified/ergonomic variant and an aftermarket monetization plan.
- Initiate targeted diligence on potential acquisition targets that close capability gaps in battery systems, modular shafts, or certification expertise.
- Implement short-term channel pilots with rental partners in two prioritized markets to validate unit economics and refine TCO messaging.
In summary, the concrete vibrator market in 2026 offers predictable growth underpinned by structural product shifts rather than a cyclic boom. Companies that marry product innovation (electrification, high-frequency control, ergonomics) with intelligent channel and service models will extract disproportionate value. PW Consulting’s full report provides the granular data, scenario models and prescriptive playbooks required to convert strategic intent into measurable market share and margin gains. Contact PW Consulting to request the full report, the underlying Excel model, or a tailored advisory engagement to accelerate decision-making.
For detailed analysis of this topic, please visit the official page: Concrete Vibrator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steam Boiler Market to Reach $236.98M by 2032 with 4.12% CAGR
By pmarketresearch, 2026-07-08
Steam Boiler System Market — 2026 Strategic Brief (PW Consulting)
Executive snapshot
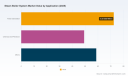
Our Steam Boiler System Market study (base year 2025) synthesizes seven years of historical behaviour and a seven‑year forecast window to provide a clear line of sight for 2026 corporate decision-making. The market expanded from roughly USD 145 million in 2020 to about USD 180 million in 2025 and is projected to grow to roughly USD 237 million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.12% across the forecast period. These headline figures mask important structural shifts — from product modularity and digital services to regulatory-driven retrofit demand — that will determine winners and losers across OEMs, system integrators, financing partners and end‑user segments.
Steam Boiler System Market
Why this study matters for 2026 decisions
-
Capital allocation: The market’s steady mid-single-digit growth invites selective investments rather than broad, high‑risk expansion. Knowing which technology and service bets deliver the highest risk‑adjusted returns in 2026 is essential for CFOs preparing mid‑cycle budgets.
Steam Boiler System Market -
Product roadmap prioritization: A single product bet is no longer sufficient. The balance between compact/modular boilers, utility‑scale systems, and electrified or hybrid designs is now a strategic choice that affects engineering, channel strategy and aftermarket economics.
Steam Boiler System Market -
M&A and partnership choreography: Fragmented supply and intermediate concentration metrics create pockets where bolt‑on acquisitions or strategic alliances generate scale quickly. The market concentration metrics in our study show meaningful room for consolidation and targeted roll‑ups that capture aftermarket value.
-
Regulatory and compliance planning: Safety and inspection codes, plus an accelerating focus on emissions and efficiency, will create near‑term retrofit windows. Companies that map regulatory triggers to commercial offerings can accelerate revenue capture with lower customer acquisition costs.
-
Service and financing models: With CapEx constraints and growing interest in performance contracting, service, financing and outcome‑based commercial models are a practical lever to expand wallet share and margin.
What the report delivers — practical, decision‑grade content
Our research was structured with the buyer and strategist in mind. The full report is modular and built around actionable deliverables that a leadership team can use immediately:
-
Detailed market sizing, with scenario pathways and sensitivity analyses that translate macro forecasts into revenue and EBITDA expectations for adjacent product lines.
-
Competitor profiles and a proprietary competitive strength matrix highlighting product breadth, systems integration capability, geographic reach and aftermarket penetration.
-
Commercial playbooks for OEMs and channel partners: go‑to‑market tactics by customer type, pricing ladders, service bundles, and contract templates for outcome‑based deals.
-
Regulatory and compliance checklist tailored to U.S. federal and state frameworks and major international regimes — a practical set that feeds directly into project risk registers and tender qualification criteria.
-
Investment due diligence kit (financial models, valuation sensitivity tables, and integration checklists) for M&A and JV activity.
-
Digitalization and retrofit ROI calculators that map sensorization, controls upgrades and predictive maintenance investments to payback periods under multiple fuel‑price scenarios.
-
Supplier evaluation framework and shortlists for component, controls and aftermarket partners — enabling procurement teams to expedite vendor selection while retaining negotiation leverage.
Note: the report intentionally withholds granular regional/application breakouts from this brief; these segment tables, revenue waterfalls and downloadable excel models are available in the full deliverable.
Competitive landscape — who matters and why
The market is characterised by a mix of global industrial majors, regional specialists and focused innovators. Measured concentration metrics indicate limited dominance by the very largest firms — enough to keep price discipline but leaving meaningful opportunity for nimble challengers and regional champions. The competitive dynamics unfold across three vectors: product architecture (packaged vs bespoke), systems integration (controls and heat‑recovery integration), and aftermarket services (maintenance, spare parts, and performance contracts).
-
Cleaver‑Brooks (Milwaukee, USA): Known for packaged industrial steam boilers and integrated systems, with a strong footprint in manufacturing and process applications. Their playbook emphasizes turnkey solutions and channel partnerships.
-
Fulton Boiler Works (Pulaski, USA): Focused on energy‑efficient gas, oil and electric boilers and packaged systems. Fulton’s differentiation stems from engineered standardization that targets low installation cost and rapid deployment.
-
Miura Boiler (Japan): A leader in compact, modular, gas‑fired boilers. Miura’s strength is speed‑to‑steam through modular scalability — a clear advantage in retrofit and constrained‑space applications.
-
Hurst Boiler and Welding (Coolidge, USA): Offers a broad fuels portfolio including biomass options. Hurst competes on durability and multi‑fuel flexibility, appealing to customers prioritizing fuel security and transition options.
-
Bosch Industriekessel (Germany): European integrated systems expertise with advanced controls — strong where customers require close automation and integration with facility energy management systems.
-
Alfa Laval (Sweden): Positioned around heat‑transfer and exchanger solutions that complement boilers, Alfa Laval’s systems approach adds incremental efficiency gains in multi‑equipment plants.
-
Thermax (India): A regional systems integrator offering full boiler systems for process industries, with a strong bias toward emerging market project execution and bundled finance models.
-
Babcock & Wilcox (USA): Focused on utility‑scale and large industrial boilers, where plant integration and lifecycle engineering are the primary value drivers.
-
Siemens Energy (Germany): Brings advanced hybrid and steam generation solutions, pairing boilers with broader energy‑system optimization capabilities.
-
Doosan Enerbility (South Korea): Specialist in large‑scale steam boilers and systems for utilities and heavy industry, emphasizing project scale and turnkey delivery.
Strategic takeaway: in 2026, differentiation will come from two combinations — systems integration + aftermarket services, and modular product architectures enabling fast, low‑risk installations. Players that can pair technology differentiation with flexible commercial models will capture disproportionate share of growth.
Market dynamics and regulatory context
Several structural forces are shaping near‑term demand:
-
Regulatory compliance and safety: Longstanding safety codes (for example, federal and state provisions that require safety valves and ASME code adherence) continue to set minimums for capital projects and inspections. Compliance timelines create windows for retrofits and equipment replacement.
-
Efficiency and decarbonization pressure: Customers are prioritizing fuel efficiency, emissions reduction and options for electrification or biomass co‑firing, driving demand for retrofit controls and hybrid system designs.
-
Commercialization of modularity: Compact, modular boilers reduce installation time and total cost of ownership for brownfield projects, increasingly preferred by process plants with constrained downtime windows.
-
Commercial channel evolution: Trade shows and sector events through 2026 — including major expos where multiple OEMs showcased packaged systems, controls and efficiency technologies — demonstrate an industry pivot to systemized, service‑centric offerings.
These dynamics mean that regulatory noise is not merely compliance overhead — it is a commercial signal. Firms that map regulatory cycles to sales and service execution calendars can preempt competitors and invoice for compliance‑driven upgrades.
Strategic implications and recommended 2026 actions
-
Prioritize modular and retrofit offerings: Reconfigure product portfolios to include compact modular solutions that shorten lead times and lower installation disruption — critical for winning retrofit opportunities in 2026.
-
Monetize aftermarket: Create subscription or outcome‑based maintenance offerings, backed by predictive analytics, to convert installed bases into annuity revenue.
-
Invest selectively in controls and digital platforms: Controls integration is the margin battleground. Invest in interoperable control stacks and data services that improve plant efficiency and justify premium pricing.
-
Use M&A to fill capability gaps: Target acquisitions that add systems integration, regional execution capability, or aftermarket reach rather than incremental product lines.
-
Align procurement to risk scenarios: Build fuel‑price and carbon regulation scenarios into procurement and pricing models to protect margins under volatility.
-
Operationalize regulatory intelligence: Convert regulatory timelines into a lead generation and project prioritization engine for sales and service teams.
Next steps — where to get the full playbook
This briefing surfaces the strategic contours for 2026 decision-making while preserving the proprietary segment analytics and supplier scorecards that drive execution. PW Consulting’s full Steam Boiler System Market report includes the complete segmented tables, downloadable financial models, vendor shortlists, and templated commercial agreements that your team can deploy immediately. For executives preparing budgets, M&A teams running screens, or product leaders defining roadmaps, the full report converts the market’s 4.12% CAGR and forecast trajectory into operational targets and measurable KPIs.
To access the complete dataset, scenario models and implementation templates, please consult our full report and client portal where detailed regional and application breakouts, supplier scorecards and ROI calculators are available for licensed users.
For detailed analysis of this topic, please visit the official page: Steam Boiler System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Premix Burners Market — Strategic Imperatives for 2026: A PW Consulting Preview
As energy transition pressures, emissions regulation, and fuel diversification converge, premix burner technology has moved from niche optimization to boardroom-level strategic priority. This PW Consulting preview summarizes the strategic value of our full Premix Burners Market study and outlines the specific decisions executives must make in 2026 to capture value and mitigate risk. The full report contains the granular segmentation, supplier scorecards, and scenario-based financial models that underpin the recommendations below; this preview deliberately highlights insight and recommendations while withholding the proprietary microdata that commercial users rely on.
Premix Burners Market
Executive snapshot — market scale and trajectory
Between 2020 and 2025 the premix burners market expanded meaningfully, reflecting stronger demand for higher-efficiency combustion solutions across industrial, commercial, and residential end uses. In 2025 the market reached a notable base year milestone, and our forecast projects continued expansion through the 2026–2032 horizon at a mid-single-digit compound annual growth rate (CAGR) of 5.2%. Under the base-case scenario embedded in our study the market progresses steadily across the forecast period, reflecting a combination of regulatory-driven retrofits, new-build industrial throughput, and technology-driven upgrades (notably low-NOx, hydrogen-capable, and porous-media burners).
Premix Burners Market
Why this matters for 2026 decision-making
- Regulatory compliance is now a primary growth lever and a cost sink: tightening NOx/CO limits across major jurisdictions force capital spending on advanced premix systems for many industrial heat applications. Companies that pre-emptively retrofit or specify compliant technologies capture both compliance upside and operational cost advantages.
- Fuel flexibility is strategic: hydrogen-capable designs and hybrid fuel strategies are transitioning from experimental to commercially available options. Early mover product launches in 2025–2026 signal an inflection point where hydrogen readiness becomes a differentiator for OEMs and end-users alike.
- Consolidation and supplier concentration alter bargaining dynamics: the market shows high concentration at the top end (the top three players capture a substantial share, with the top five even more so). Strategic sourcing, long-term OEM partnerships, and selective M&A are therefore central to securing supply and capabilities.
- Incremental efficiency gains compound: modest efficiency improvements in burner design translate into meaningful fuel and emissions reductions at scale — a crucial consideration for industrial operators facing decarbonization targets and energy cost volatility.
Market dynamics shaping near-term strategy
Several structural forces interplay to create a dynamic landscape for 2026 strategy:
Premix Burners Market
- Regulatory drivers: The EU’s Industrial Emissions Directive, U.S. EPA hazardous air pollutant standards, China’s Air Pollution Prevention and Control Law, and regional energy codes (e.g., India’s energy efficiency building codes) collectively tighten emissions and efficiency requirements. Compliance timelines are staggered geographically, shaping where retrofit demand will concentrate first.
- Technology diffusion: Metal fiber, ceramic and advanced porous mediums continue to compete on lifetime cost, turn-down ratio, and NOx performance. Manufacturers are also integrating controls and air/gas ratio management to optimize combustion stability and emissions across varying fuel blends.
- Fuel transition and hydrogen readiness: 2025–2026 product introductions show hydrogen-capable premix burners moving to commercialization. This requires re-evaluating materials, safety systems, and supply chains — and creates an opportunity for early adopters to lead in hydrogen-compatible heating solutions.
- Supply chain and manufacturing inputs: Premix burners rely on high-temperature steels, metal fiber elements, and ceramic components. Price volatility or availability shocks in these inputs affect lead times and margins, making supplier diversification and vertical integration levers of value.
Competitive landscape — what the leaders are doing
The competitive field combines global industrial groups, specialty burner manufacturers, and regional engineering houses. Market concentration is high — the top three players collectively command the majority of share, and the top five increase that dominance further — creating asymmetries in pricing power, channel reach, and R&D scale.
- Established incumbents focus on scale and compliance: Firms with broad combustion portfolios are driving uptake through packaged solutions, integration with boiler/OEM systems, and compliance-driven retrofits. Expect continued investment in rule-of-law geographies where regulatory enforcement is strongest.
- Specialists differentiate on technology and niche applications: Companies with depth in metal fiber, porous ceramic, or ultra-low NOx solutions are leveraging performance differentiation into specialty industrial segments and aftermarket services.
- Regional players compete on cost and local relationships: Several manufacturers capitalize on lower-cost production and strong regional distribution to serve retrofit markets and commodity-driven industrial segments.
Notable recent developments illustrate these trends: in early 2026 a major equipment supplier launched a hydrogen-capable premix burner targeted at asphalt production, and in 2025 a regional manufacturer unveiled what it described as a domestic hydrogen burner and a very large-capacity industrial burner. These moves confirm two themes — product innovation toward hydrogen compatibility and ongoing investments in heavy industrial capacity.
What the full PW Consulting report contains (practical, actionable content)
Our full study is designed as a playbook for commercial, engineering, and corporate development teams. Key deliverables include:
- Validated market sizing and a seven-year forecast with scenario pathways (base, conservative, and accelerated hydrogen adoption cases)
- Segmentation across technology, application class, and region with demand drivers and elasticity analysis (note: detailed unit and revenue splits are in the full report)
- Competitor benchmarking and capability maps, including product portfolios, geographic reach, and technology stacks for the leading OEMs and niche specialists
- Technology assessment: comparative performance, lifecycle cost models, hydrogen readiness scorecards, and retrofit versus new-build economics
- Regulatory impact matrix showing compliance timelines, enforced thresholds by jurisdiction, and likely retrofit windows
- Supply chain stress tests: supplier concentration, input price sensitivity, and suggested mitigation strategies (dual sourcing, component stocking, vertical partnerships)
- Commercial playbooks: go-to-market recommendations by segment, channel optimization (OEM, direct, distributor, aftermarket), and pricing tactics
- M&A target shortlists and integration considerations for acquiring combustion capabilities or complementary controls expertise
- Risk register and monitoring dashboard for 2026–2028 decision cycles
Strategic playbook for 2026 — prioritized actions
Leaders must act on three time horizons: immediate (0–12 months), tactical (12–24 months), and strategic (24–60 months). Our analysis yields a prioritized set of actions:
- Immediate (0–12 months)
- Map your exposure to tightening emissions limits and identify assets requiring urgent retrofit. Prioritize high-operating-hour assets where ROI is fastest.
- Engage top-tier burner OEMs to secure supply windows and lock-in performance guarantees tied to emissions and fuel-flexibility specs.
- Begin pilot evaluations of hydrogen-capable burners in controlled applications where safety and operational risk can be contained.
- Tactical (12–24 months)
- Standardize technical specifications across projects to reduce engineering customization and accelerate procurement.
- Negotiate bundled maintenance and aftermarket service contracts to capture lifecycle efficiency gains and reduce total cost of ownership.
- Implement supplier risk mitigation: multi-sourcing critical components (metal fiber elements, high-temp ceramics) and exploring local fabrication partnerships.
- Strategic (24–60 months)
- Pursue M&A or JV activity to acquire combustion controls, hydrogen-handling expertise, or specialized porous-media manufacturing where market presence is weak.
- Invest in digital-first combustion controls and monitoring systems to enable predictive maintenance, emissions reporting, and remote optimization.
- Define a hydrogen transition roadmap tied to regional fuel availability and regulatory incentives; structure capital projects to be retrofit-ready for blended fuels.
Risk scenarios and hedges
We model three core scenarios that materially affect market outcomes and strategic choices:
- Regulatory acceleration: faster tightening of emission limits increases retrofit demand and benefits incumbents with certified low-NOx solutions.
- Hydrogen adoption: subsidy-driven adoption of hydrogen in select industries creates premium markets for hydrogen-capable burners but raises safety and materials requirements.
- Supply-chain disruption: shortages or price spikes in metal fiber and high-temp ceramics raise lead times and margins, favoring vertically integrated players.
Recommended hedges include staged CapEx with retrofit triggers, investment in controls that reduce fuel use (thereby lowering exposure to fuel price swings), and contractual mechanisms with OEMs to share retrofit risk under evolving fuel mixes.
How PW Consulting’s study creates value for your 2026 planning
Our report translates market trajectory, technology diffusion, and regulatory momentum into concrete actions: prioritized retrofit lists, supplier scorecards, investment sizing templates, and an M&A watchlist that aligns with corporate decarbonization and operational resilience goals. The study’s base-year calibration and multi-scenario forward view provide finance, operations, and strategy teams with a defensible framework to allocate capital and organize cross-functional execution in 2026.
Next steps — where to get the full intelligence
This preview highlights the strategic contours of the premix burners market; however, the full competitive scorecards, regional demand matrices, and financial models are deliberately withheld here to protect the proprietary work that drives our clients’ decisions. PW Consulting clients and subscribers can access the complete report, downloadable datasets, and bespoke briefing sessions through our market research portal. For teams evaluating specific acquisition targets, sourcing strategies, or regulatory compliance programs, we offer tailored workshops that translate the report’s findings into executable project plans.
Contact PW Consulting to schedule a briefing and receive the full Premix Burners Market study — including the detailed segmentation, vendor comparisons, and scenario-tailored investment cases that are essential for confident 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Premix Burners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Programmable Stage Lighting Market to Reach USD 259.78M by 2032 at 7.25% CAGR
By pmarketresearch, 2026-07-08
Programmable Stage Lighting Market — Strategic Primer for 2026 Decision-Makers
Executive snapshot
At PW Consulting, we treat the Programmable Stage Lighting market as a systems play — where optics, power electronics, control architectures and software converge to shape audience experiences and operational economics. Our new study (base year 2025, historical series 2020–2025, forecast 2026–2032) synthesizes commercial, regulatory and technology forces into an actionable roadmap for leaders preparing strategic moves in 2026.
Programmable Stage Lighting Market
Key macro takeaways: the market has expanded from roughly USD 120 million in 2020 to about USD 159 million in 2025 and is projected to grow at a mid-single-digit compound annual growth rate (CAGR) through 2032, reaching approximately USD 260 million at the end of the forecast period. That trajectory represents steady, demand-led expansion driven by energy-efficient LED adoption, greater programmability across event categories, and the emergence of control-layer interoperability standards.
Programmable Stage Lighting Market
Why this matters for 2026 strategy
- Investment horizon alignment — The revenue runway through 2032 allows companies to rationalize multi-year R&D and productization efforts that prioritize digital control and energy efficiency without overreaching on short-term returns.
- Regulatory and standards timing — Compliance investments (energy efficiency mandates, RoHS/CE requirements) and DALI‑2 certification cycles are now hard gating market access in major markets; timing product launches around certification milestones will materially affect adoption.
- Competitive posture — The market exhibits moderate concentration (top-three and top-five shares indicative of meaningful incumbency but open pockets for innovation-led entrants). This creates balanced conditions for consolidation, niche specialization, and platform plays.
What the report delivers (practical deliverables)
We designed the study to be a playbook for executives, product leaders, M&A teams, and commercial strategists. Highlights include:
Programmable Stage Lighting Market
- Market architecture and value-chain mapping that ties fixture hardware, control protocols (DMX, sACN, DALI‑2), power electronics, and software platforms to buyer personas (rental houses, venues, broadcasters, touring productions).
- A robust market-sizing and scenario model (baseline, conservative, upside) covering 2026–2032 with sensitivity levers for energy regulation, supply constraints, and demand shocks.
- Supplier benchmarking: technology scorecards, go-to-market profiles, channel economics, and aftermarket/service positioning for the leading manufacturers and controls specialists.
- Commercial playbooks: product portfolio prioritization, pricing strategy templates based on total cost of ownership (TCO) calculus, and rental vs. ownership decision matrices for customers.
- M&A and partnership guidance: target screening criteria, valuation multiples observed in adjacent segments, and integration checklists focused on software and control interoperability.
- Implementation roadmaps for compliance (DALI‑2, RoHS, CE) and energy-efficiency retrofits that minimize revenue disruption while unlocking lifecycle savings.
Competitive landscape — dynamics and strategic postures
The competitive map blends heritage theatrical suppliers, entertainment-focused innovators, lighting-component OEMs, and specialty control-software houses. Incumbents maintain strengths in reliability, service networks and channel relationships; challengers win on feature velocity and software-enabled differentiation.
- Electronic Theatre Controls (ETC) — A legacy theatrical control and fixture player emphasizing integrated theatrical consoles, fixture families and gateways that bridge DMX and DALI ecosystems. Recent product development on DALI‑2 gateways reflects a clear play to simplify integrator workflows where DALI integration is a procurement requirement.
- Signify (Vari‑Lite) and Martin Professional (HARMAN) — These players lean into automated fixtures and touring-grade robustness. Their scale and distribution enable them to defend premium touring and large-venue segments.
- Robe, Clay Paky, Ayrton — European innovators that push optical quality and precise motion control; they tend to lead on fixture performance and bespoke feature sets for high-end productions.
- Chauvet, ADJ, Elation — Cost-efficient producers that extend programmability to broader install and mid-tier rental markets with aggressive price-performance propositions.
- Component and lighting‑engine suppliers (Osram, LumenPulse) — These firms are critical upstream partners. Their LED engine and driver innovations directly affect fixture efficiency, color rendering and lifecycle economics.
- Controls and laser specialists (Pangolin, Chromateq) — Providers of laser fixtures and control systems are doubling down on software functionality and trade-show visibility, signaling continued demand for high-impact visual effects that require precise synchronisation with control ecosystems.
Notable recent moves underscore two themes: deepening interoperability and show-oriented innovation. Examples include new DALI‑2 gateway launches and control-software upgrades showcased at major industry events. These are harbingers of a market where product success increasingly rests on ecosystem compatibility and software update pathways.
Regulatory and standards environment — operational impacts
Regulatory forces are no longer background noise. Energy efficiency mandates, CE/RoHS compliance obligations and the rise of DALI‑2 as the interoperability standard create both cost and strategic opportunity:
- Compliance increases upfront engineering and certification spend, but reduces operating costs for end users — a point that can be monetized through TCO-based sales motions.
- DALI‑2 certification lowers integration friction in installed systems; suppliers that offer certified gateways and clear migration paths for legacy DMX infrastructures will capture preference in retrofit and specification-driven projects.
- LED dominance in fixture designs reduces energy consumption and maintenance but shifts competitive focus to optics, thermal management and control latency.
Where the pockets of opportunity are in 2026
- Software-first differentiation: invest in cloud-enabled content management, fixture emulation libraries and remote firmware delivery to create recurring revenue streams and lock-in.
- Control-layer convergence: develop certified DALI‑2 gateways and tested sACN/Art-Net bridges to be the integrator’s preferred choice for mixed-protocol deployments.
- Service and financing: offer lifecycle service agreements and asset-financing programs targeting rental houses and venues to accelerate adoption without depressing realized prices.
- Product modularity: create scalable fixture platforms with pluggable optics and control modules to address both touring and fixed-install requirements with lower SKUs and faster market fits.
- Sustainability and circularity: position refurbishment and component-replacement programs to capitalize on regulatory-driven retrofit cycles and to address large installed bases seeking emissions reductions.
Risks and mitigants
- Supply-chain concentration: diversify sourcing for critical LEDs and driver ICs; adopt multi-sourcing strategies with strategic buffer inventories tied to forecast risk triggers.
- Certification lead times: begin compliance and testing processes early (DALI‑2, CE/RoHS) to avoid launch delays and lost specification lists.
- Channel conflict: if pursuing direct SaaS-enabled control platforms, implement clear partner economics and co-sell models to avoid undermining distributor/rental relationships.
How to use the full report in your 2026 planning cycle
Use the study as the backbone for three 90-day sprints:
- Sprint 1 — Compliance and product roadmap: map certification timelines into product development milestones and prioritize gateway/fixture pairings for early-market programs.
- Sprint 2 — Commercial model test: pilot TCO-based pricing and bundled service agreements with a subset of rental and venue partners; track uptake and margin elasticity.
- Sprint 3 — M&A and partnerships: apply our target-screen framework to shortlist capability buys (controls software, optics startups) and structure earn-out mechanisms tied to integration KPIs.
Closing — what we recommend you do next
The programmable stage lighting market in 2026 is a landscape of incremental hardware gain and exponential software opportunity. Firms that treat fixtures and controls as a combined product-service system — and that manage certification timelines as strategic levers — will secure outsized returns as the market grows toward the end of the decade.
PW Consulting’s full report contains the underlying forecast model, supplier scorecards, pricing frameworks and proprietary interviews that substantiate these conclusions. We intentionally reserve the detailed segmentation tables and transaction-level data for subscribers. For a tailored briefing and to access the complete dataset and executable playbooks, please visit our research page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Programmable Stage Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Meter Market to Hit USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-08
Water Meter Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, high-fidelity lens into our forthcoming Water Meter Market study — a practical guide tailored for executive teams, product strategists, procurement leaders, and investors preparing to make consequential decisions in 2026. This preview demonstrates the analytical depth and actionable frameworks contained in the full report while intentionally withholding granular segment-level data to preserve the value of the complete research.
Water Meter Market
Why this research matters in 2026
- Market trajectory: The global water meter market, measured in USD million, expanded substantially during the 2020–2025 base period and is forecast to continue a steady expansion through 2032. Our base-year anchoring (2025) and the modeled outlook to 2032 embody a compound annual growth rate (CAGR) of 6.98%, reflecting robust demand drivers across metering technologies and service models.
- Strategic inflection points: 2026 is a pivotal year — a mix of regulatory shifts, standard updates, and new product disclosures is altering procurement timelines, supplier selection criteria, and investment horizons for utilities and large industrial water users.
- Decision focus: Leaders need concise, risk-weighted intelligence to prioritize R&D, M&A, supply-chain resilience, and field-deployment pilots. Our study is built explicitly for that purpose.
High-level market picture (what the numbers imply)
From the pandemic recovery window through the present, the sector has moved from modest replacement cycles toward accelerated smart-metering and bulk-meter modernization programs. The market’s compound annual growth rate near 7% signals more than cyclical replacement spending — it underscores structural shifts: digital metering, data-driven network management, and cross-sector demand for leakage control and non-revenue water reduction. By 2032 the market is projected to be materially larger than the 2025 base, creating meaningful opportunities for established vendors, fast followers, and specialized system integrators.
Water Meter Market
Dynamics reshaping strategy
- Regulatory and procurement levers: Recent policy adjustments — including a temporary general applicability waiver for Advanced Metering Infrastructure (AMI) under a major domestic procurement statute — are compressing procurement windows and changing vendor compliance timelines. Procurement teams must redesign supplier evaluation roadmaps to reflect phased domestic content requirements and waiver transitions.
- Standards and testing: The publishing of updated industry guidance and active field-testing programs at major conferences has raised the bar for performance validation and interoperability. Utilities and buyers now demand test-evidenced performance for ultrasonic and smart metering solutions as part of contract award criteria.
- Technology modularity: Electronics, communication stacks, and sensing elements are decoupling from meter housings. This modularity creates new aftermarket opportunities (retrofit communications modules, analytics subscriptions) but also raises compatibility and lifecycle-management issues for utilities.
- Consolidation and concentration: Market concentration is moderate; the top-three and top-five vendor groups do not dominate the ecosystem to the extent seen in other infrastructure markets. This opens space for regional champions, specialized innovators, and service-driven business models.
Competitive landscape — players to watch
Our competitive analysis profiles incumbent OEMs, regional manufacturers, and cross-disciplinary entrants. Below are strategic snapshots of the core firms we examined and the recent moves that matter for 2026 strategy.
Water Meter Market
- Badger Meter (Milwaukee, Wisconsin) — A diversified provider across ultrasonic, mechanical, and AMI-compatible solutions focused on systems integration and data products. Recent Q1 2026 disclosures highlighted both steady financial performance and an inorganic acceleration into sewer monitoring through the acquisition of a sector-specific technology firm, underscoring their push to capture adjacent metering and monitoring markets.
- ZENNER International GmbH & Co. KG (Germany) — A longstanding manufacturer with capabilities spanning mechanical, ultrasonic, and smart meters. With consistent emphasis on product breadth across residential and bulk applications, Zenner’s engineering depth positions it to participate in both municipal modernization and industrial metering projects.
- Ningbo Aimei Meter Manufacturing / Ningbo Yongzhou / Wenling Younio (China-based manufacturers) — These manufacturers combine high-volume mechanical metering competence with increasing investments in electronic and IoT-enabled products. Their cost-competitiveness and manufacturing scale make them significant players in price-sensitive tender corridors and retrofit programs.
- Diehl Metering (Germany) — Focused on utility-grade solutions and bulk metering, Diehl continues to leverage trade-show platforms to showcase next-generation bulk metering products aimed at large utilities and industrial water users; their recent product exhibits at leading conferences indicate continued emphasis on accuracy, serviceability, and system-level value propositions.
Taken together, vendor strategy choices fall into a few repeatable archetypes: integrated platform builders (hardware + software + services), manufacturing-focused players enabling low-cost volume deployments, and niche specialists delivering high-accuracy or bulk-meter solutions. The competitive field is dynamic: product announcements and targeted acquisitions in early 2026 highlight a race to expand functional footprints beyond pure device sales.
Operational and go-to-market implications
- Procurement strategy refinement: Implement staged RFPs that explicitly accommodate waiver-driven purchasing timelines and phased domestic-content milestones; include modular acceptance criteria for retrofit or hybrid AMI rollouts.
- R&D and product roadmaps: Prioritize modular electronic platforms, OTA (over-the-air) upgradability, and API-first data architectures to enable interoperability with utility analytics platforms and third-party service providers.
- Service & subscription models: Monetize analytics and leakage-detection services alongside hardware sales. A blended revenue model reduces dependency on replacement cycles and increases lifetime customer value.
- M&A and partnerships: Look for tuck-in acquisitions that add sewer and network-sensing competencies, or partner with communications specialists to de-risk connectivity and ongoing firmware maintenance obligations.
What the full PW Consulting report delivers (practical, executable content)
Our complete study is structured to move leadership from insight to action. Highlights of the deliverables include:
- Executive decision frameworks: capital allocation templates, investment prioritization matrices, and ROI breakeven models tailored to metering upgrades and AMI/AMI-adjacent investments.
- Procurement playbook: sample RFx language, compliance checklists addressing domestic-content phase-ins, acceptance-test protocols that map to updated standards, and vendor scorecards for risk-weighted selection.
- Technology adoption maps: maturity curves for ultrasonic, electromagnetic, ultrasonic bulk meters, volumetric technologies, and retrofit communication modules, plus recommended pilot designs by use case.
- Competitive battle cards: strategic profiles, capability comparisons, and scenario-based win-loss hypotheses for the principal suppliers and regional challengers.
- Supply chain risk register: component sourcing heatmaps, single-source exposures, and mitigation playbooks that include dual-sourcing and consignment strategies for critical electronic components.
- Go-to-market blueprints: channel segmentation, pricing strategy experiments, and service-bundling options for city-scale deployments, private utilities, and industrial clients.
- Granular appendices: primary interview synopses, methodology notes, and data tables that drill into unit shipments, ASP trends, and installed-base replacement cycles — accessible in the full report to subscribers.
How to use this intelligence in 2026 (three priority actions)
- Align procurement with policy timing: If your projects are tied to public funding or are subject to domestic-content rules, modify contract clauses and supplier milestones now to avoid rework when waiver transitions end.
- Shift product bets toward modularity: Invest in field-upgradable electronics and open data platforms to reduce churn and capture long-term service revenues. Proof-of-concept deployments that validate interoperability will open procurement pathways.
- Execute targeted inorganic growth: Pursue bolt-ons that add sensing capabilities (e.g., sewer monitoring, pressure/flow analytics) or expand analytics capabilities, improving stickiness with utility customers and enabling premium service tiers.
Why executives should trust this preview
PW Consulting’s assessment synthesizes primary utility interviews, vendor financial disclosures, trade-show validation, standards-track developments, and a proprietary forecasting engine. We triangulate shipment trends with price realization models and account for regulatory permutations — including the recent AMI waiver and updated industry manuals — to produce scenario-ready guidance for 2026 decision-making.
Next steps — where to get the full intelligence
This preview intentionally surfaces the strategic contours and executive playbooks while withholding the underlying granular segmentation and proprietary tables that drive procurement and product decisions. The full report contains the detailed, validated datasets, regional deployment models, and downloadable templates you need to operationalize the recommendations outlined above. Access the complete Water Meter Market study on our website to obtain the appendices, vendor scorecards, and the full suite of decision-support tools.
For prioritized briefings or to commission a bespoke workshop that maps these insights to your organization’s specific portfolio, contact our PW Consulting Water Meter market practice. Our goal is to convert foresight into action — rapidly, defensibly, and with measurable outcomes.
For detailed analysis of this topic, please visit the official page: Water Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pneumatic Components Market to reach USD 22.6B by 2032 at 6.46% CAGR
By pmarketresearch, 2026-07-08
Pneumatic Components Market — Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our new Pneumatic Components Market study. Anchored on a 2025 base year and a robust forecast through 2032, this study synthesizes supply-side realities, demand dynamics, competitive positioning, and practical playbooks designed to inform capital allocation, product strategy, procurement decisions, and M&A activity in 2026.
Pneumatic Components Market
Macro trajectory you cannot ignore
The pneumatic components market has moved from a mature, industrial staple to a growth market with structural drivers that extend beyond cyclical manufacturing demand. Our topline modeling shows steady expansion from 2020 through 2025 and a continued upward trajectory across the 2026–2032 forecast window, underpinned by a multi-year compound annual growth rate of approximately 6.46%. This growth path reflects a confluence of factors: industrial automation penetration, energy-efficiency retrofits, rising medical device utilization, and tiered regional demand patterns. For executives, the headline is simple — the market is expanding at a pace that sustains returns for focused investors, while also creating pockets of disruption for incumbents and agile new entrants alike.
Pneumatic Components Market
Why this report is strategic for 2026 decisions
- Investment prioritization: Translate market momentum into highest-return R&D and capex bets with our investment-scoring framework that ranks product families by growth potential, margin resilience, and defensibility.
- Procurement and supply resilience: Identify stress points in raw-material exposure and supplier concentration; the report includes tactical levers for rapid supplier diversification and dual-sourcing pilots.
- Go-to-market and aftermarket strategies: Move beyond components to service-led models—our commercial playbook shows how to capture higher lifetime value through predictive maintenance, retrofits, and modular offering bundles.
- M&A and partnership screening: Use our transaction filter to find targets that fill technology gaps (energy-efficient actuators, intelligent valves), geographic blind spots, or aftermarket capabilities.
- Regulatory and product compliance planning: Anticipate and budget for regulatory-driven redesigns in energy and safety standards so product roadmaps remain time-to-market competitive.
What the report delivers — practical, actionable, and ready-to-use
This study is structured for executives who need both strategic context and operational tools. Highlights include:
Pneumatic Components Market
- Topline market sizing and validated forecasts (2020–2032) with scenario variants reflecting material-price shocks and regulatory tightening.
- Concentration and competitive intensity diagnostics — including market-share clustering and an analysis of three- and five-firm concentration dynamics — to help prioritize competitive responses.
- Supplier and component-level risk matrices that quantify exposure to raw material volatility, precision-machining bottlenecks, and logistics disruptions.
- Commercial and pricing playbooks: price-elasticity models, service migration pathways, and margin-capture strategies for OEMs and distributors.
- Technology and product roadmaps: assessment of electrification hybrids, modular pneumatics, intelligent valves, and the intersection with IIoT and factory automation investments.
- Ready-to-use deliverables: a dynamic spreadsheet model, an executive slide deck for board briefings, a supplier-engagement checklist, and scenario scripts for stress-testing business plans.
Competitive landscape — what market leaders are doing and why it matters
The competitive field blends long-established global players with fast-moving regional manufacturers. Leading incumbents are shifting from component suppliers toward systems and services — a move that compresses pure-play margins but expands lifetime value and stickiness with end customers.
- Festo (Germany) is doubling down on automation-integrated pneumatic solutions and energy-efficient actuators. Their product focus signals where premium segments of the market will cluster: performance plus systems integration.
- Parker Hannifin (United States) continues to leverage breadth across motion control to offer comprehensive pneumatics portfolios that appeal to industrial OEMs pursuing consolidated suppliers.
- SMC (Japan) prioritizes compact, intelligent pneumatic modules and has introduced space-saving valve solutions that simplify installation on modern automated lines.
- Bosch Rexroth and Emerson maintain strength in hydraulics-pneumatics hybrids and process-industry automation — their roadmaps indicate sustained demand for ruggedized, high-reliability components.
- Norgren, Camozzi, Airtac and multiple regional players balance cost-competitiveness with localized service footprints; their market tactics increase pricing pressure in standard-product categories but also accelerate adoption in high-volume OEMs.
- China- and Taiwan-based manufacturers are expanding technical capabilities while preserving cost advantages; expect increased competitive intensity in price-sensitive segments and faster adoption cycles in regional markets.
Recent product activity corroborates this divergence. Throughout 2025, the market saw launches of energy-efficient actuators, modular valve platforms, and corrosion-resistant tubing — trends that underline two strategic vectors: feature-led premiumization and cost-led scale. For decision-makers, the implication is clear: either compete on high-value differentiation (systems, energy optimization, digital services) or on operational scale and channel reach.
Dynamics and risks that will shape outcomes in 2026
- Raw-material volatility: Aluminum, steel, and technical plastics remain core cost drivers. Periodic price swings materially impact margins unless mitigated by hedging, long-term contracts, or design-to-cost initiatives.
- Supply-chain fragility: Precision pneumatic components rely on specialized machining and coatings. Geopolitical disruptions and logistics bottlenecks have in recent years produced measurable delivery delays — companies must assess dual-sourcing timelines and domestic production feasibility.
- Regulatory influence: Energy and machinery safety directives in major markets are pressuring suppliers to increase product efficiency and provide compliance documentation. Early engagement with standards planning converts compliance into competitive advantage.
- Material restrictions: Export controls and limitations on certain rare-earth inputs elevate lead-time risk for sealing materials and coatings; procurement and product teams must validate alternate formulations.
- Technological shift: Hybridization (electro-pneumatic systems) and intelligence layers are changing OEM requirements; incumbents who ignore systems integration risk margin erosion.
A practical 90-day plan for executives entering 2026
- Week 1–4: Rapid risk audit. Map top 10 suppliers by spend and criticality, quantify single-source exposure, and initiate contingency agreements with alternate suppliers.
- Week 5–8: Product triage. Classify SKUs into defend, optimize, divest. Fast-track product redesigns that reduce raw-material content or enable modular upgrades tied to higher-margin services.
- Week 9–12: Commercial pilots. Launch two aftermarket service offers (e.g., predictive maintenance, retrofit kits) with pilot OEMs or distributors; measure adoption and margin uplift.
- Parallel: Investor and M&A screening. Use our target-filter to identify acquisition prospects that add digital capabilities, shorten supply chains, or insert aftermarket channels.
How PW Consulting’s study reduces execution risk
We designed this report to convert uncertainty into decision-grade intelligence. It combines bottom-up manufacturing economics, primary interviews with OEMs and distributors, and a scenario-enabled forecast model so that executives can evaluate “what-if” outcomes for investment choices, procurement strategies, and competitive moves. Our concentration diagnostics and supplier-risk frameworks are intentionally operational — meant to be plugged into procurement RFPs, board-level investment memos, and R&D portfolio meetings.
To maintain confidentiality of core proprietary segment-level metrics while still demonstrating analytical depth, this preview highlights strategic direction and tactical priorities without disclosing the full granularity of regional and application splits. The complete report includes the full segmented dataset, regional-application overlays, supplier scorecards, and model spreadsheets necessary to execute the 90-day plan described above.
Next step
For access to the full Pneumatic Components Market report, including the segmented datasets, scenario models, and executable decks, visit PW Consulting’s market research page. If you would like a guided briefing tailored to your company’s footprint, contact our industry desk to schedule a strategic briefing and a hands-on modelling session.
In 2026 the winners will be those who convert the market’s steady growth into sustainable, differentiated value — through resilient supply chains, service-enabled revenue, and targeted product innovation. This report is designed to make that conversion repeatable and measurable.
For detailed analysis of this topic, please visit the official page: Pneumatic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Green Roof Market to Reach USD 6.65M by 2032 at 15.3% CAGR
By pmarketresearch, 2026-07-08
Green Roofs 2026: Strategic Signals from PW Consulting’s Market Preview
As urban sustainability climbs corporate and municipal agendas, green roofs have shifted from niche pilot projects to scalable infrastructure options. PW Consulting’s Green Roof Market Preview synthesizes market dynamics, regulatory drivers, supplier strategies, and actionable scenarios to inform executive decisions through 2026 and beyond. Below we outline the strategic value of the full study, highlight high‑impact findings, and present the question set every executive should be able to answer before allocating capital or launching new offers in this space.
Green Roof (Green-Roof) Market
Why this preview matters for 2026 decision-making
-
A rapidly expanding market: The global green roof market has shown sustained, above‑average growth in the past half‑decade, accelerating further into our forecast horizon. Measured from the 2025 base year, the market trajectory we model implies a compounding growth profile that demands proactive positioning rather than reactive entry.
Green Roof (Green-Roof) Market -
Time-sensitive windows for scale: With a forecast CAGR of 15.3% across the 2026–2032 period, the next 12–18 months represent a critical window for firms to secure channel partners, test modular product concepts, and lock in supply agreements without being squeezed by late‑cycle price pressure.
Green Roof (Green-Roof) Market -
Regulation and reimbursement are amplifiers: Local stormwater rules, municipal incentive programs, and tax abatements have shifted green roofs from voluntary sustainability upgrades to economically defensible solutions in many jurisdictions. These policy levers are heterogeneous—creating both opportunities and execution complexity for firms able to navigate local requirements.
What PW Consulting’s full report delivers (practical, executable content)
-
Market sizing and forward scenarios: A transparent baseline anchored to 2025 with scenario‑based outlooks through 2032. We provide topline revenue curves and sensitivity analyses that help translate market growth into addressable opportunity for product lines, installation services, and maintenance contracts.
-
Commercial playbooks: Go‑to‑market templates for OEMs, installers, and engineering firms—covering spec‑first sales, municipal procurement, public‑private partnership (PPP) structures, and bundled financing models. Each playbook includes staffing profiles, key KPIs, and a three‑phase implementation roadmap designed for 12–24 month horizons.
-
Operational readiness checklists: Practical guidance on rooftop structural assessment protocols, lightweight media sourcing, irrigation integration, and maintenance contracts that preserve warranty and performance certification. These checklists are designed for quick deployment by project managers and sustainability leads.
-
Competitive benchmarks and acquisition targets: A curated universe of vendors, component specialists, and materials providers profiled against capability matrices—useful for M&A screening and partnership diligence.
-
Regulatory intelligence and incentives map: A synthesis of current regulatory drivers, stormwater credit frameworks, and tax incentive archetypes to support site-level business case modeling without having to reinvent municipal research for each opportunity.
Market structure and strategic implications
The green roof market remains fragmented, creating room for consolidation and specialization. Our concentration metrics point to low market share for top players relative to total market size, signaling buyer fragmentation and a strong role for differentiated product and service models. For corporations considering entry or expansion, this fragmentation creates three adjacent strategic plays: scale through modular systems, specialize in engineered growing media and O&M, or compete on integrated offerings that combine waterproofing, stormwater management, and vegetation warranties.
Competitive landscape — who’s shaping the ecosystem
The supplier ecosystem combines established waterproofing and roofing integrators, modular system suppliers, and specialist inputs such as engineered growing media. Notable firms include long‑established waterproofing and assembly manufacturers, modular tray suppliers, media specialists with significant square‑footage experience, and manufacturers of moisture protection and accessory components. These players are advancing product portfolios and digital tools to capture higher-margin downstream services.
Recent market activity underscores a few industry‑level themes:
-
Product modularization and integration: Several firms have launched new modular systems and built‑in‑place layered assemblies, enabling faster installation cycles and improved stormwater performance characteristics.
-
Convergence with other urban infrastructure: Hybrid solutions that integrate photovoltaic systems with vegetated platforms are moving from concept to commercial product, opening a new product category—bio‑solar roof systems—that combines energy generation and green infrastructure benefits.
-
Digital enablement: Suppliers are digitizing catalogs, presenting specification tools to design partners, and participating in industry forums to accelerate specification uptake among architects and landscape professionals.
Selected vendor dynamics (illustrative, non‑exhaustive)
-
Long‑standing waterproofing and roofing integrators are packaging certified garden roof assemblies that pair monolithic membranes with vegetated layers—strengthening value propositions for performance guarantees and insurance acceptance.
-
Modular tray and tray‑plus‑paver system providers are emphasizing rapid deployment, reduced rooftop dead load, and compatibility with rooftop access and amenity use—targeting urban retrofit projects.
-
Soil and media specialists are focusing on engineered substrates and specification tools for landscape architects, consolidating influence over plant performance and long‑term O&M economics.
Recent product launches and industry activity in early 2026 validate these trends: modular and layered systems were introduced alongside a push to integrate green roofs with solar technologies and digital product catalogs. Industry conferences continue to be a primary channel for specification education and market adoption among design professionals.
Key risks and mitigation strategies for 2026
-
Execution risk: Skilled installers and certified maintenance providers are a scarce resource in many markets. Mitigation: invest in installer training programs, certify partners, and lock in installation capacity through distribution agreements.
-
Supply chain risk: Engineered media and specialty components have concentrated manufacturing footprints. Mitigation: dual‑source critical inputs and localize media blends where possible to reduce freight and seasonal variability.
-
Policy volatility: Incentives and stormwater credit regimes change at the municipal level. Mitigation: maintain a local regulatory monitoring capability and include incentive sensitivity in every project financial model.
-
Lifecycle performance risk: Warranty exposure tied to vegetation health and irrigation. Mitigation: offer bundled service contracts and remote monitoring to manage risks and create recurring revenue streams.
Five targeted plays for executives in 2026
-
Spec‑first partnerships: Build early relationships with architecture and landscape design firms, offering specification‑grade tools and case studies to make your product the default choice when projects enter permitting.
-
Productize hybrid solutions: Pilot integrated solar + green roof systems in one or two high‑visibility municipal or commercial projects to create repeatable templates and measurable ROI stories.
-
Monetize O&M: Convert installation wins into multi‑year maintenance contracts with performance clauses tied to stormwater credits and vegetation health KPIs.
-
Localized supply strategies: Develop regional media blends and logistics playbooks to reduce cost and carbon intensity—an increasingly important selling point for sustainability procurement teams.
-
M&A and partnership scouting: Target specialist media producers, tray manufacturers, or digital specification tool startups to accelerate capability building while maintaining capital discipline.
What we intentionally do not disclose here (and why)
In keeping with the “trailer” approach of this preview, we present clear strategic signals while withholding proprietary granular segmentation tables and line‑by‑line regional/application shares. The full PW Consulting report contains detailed regional and application splits, vendor revenue benchmarks, and downloadable modeling templates that translate top‑line market growth into product‑level and project‑level profitably scenarios—essential material for bidding, M&A diligence, and board‑level investment decisions.
Next steps
Executives preparing 2026 budgets should prioritize three immediate actions: (1) commission a short site‑level portfolio review to identify near‑term retrofit candidates; (2) pilot a spec engagement with one architecture firm to capture early procurement mindshare; and (3) evaluate supplier options for media and modular systems to secure lead times. For teams requiring the full segmentation data, financial models, and vendor diligence appendices that underpin these recommendations, the complete PW Consulting Green Roof Market report provides the operative intelligence required to move from strategy to execution.
Contact PW Consulting to access the full study, proprietary datasets, and bespoke scenario modeling tailored to your portfolio or product roadmap.
For detailed analysis of this topic, please visit the official page: Green Roof (Green-Roof) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bioreactors & Fermenters Market to Hit USD 42.4B by 2032 at 10.9% CAGR
By pmarketresearch, 2026-07-08
Bioreactors and Fermenters Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive preview
The global bioreactors and fermenters market sits at a strategic inflection point as 2026 begins. PW Consulting's latest study, anchored on a 2025 base year and a comprehensive 2020–2025 historical review, shows the market expanding at a sustained double‑digit tempo (10.9% CAGR) into our 2026–2032 forecast window. From roughly USD 12.3 billion in 2020 the market grew to an estimated USD 20.6 billion by 2025 and is projected to exceed USD 42 billion by 2032. These macro dynamics are signals, not answers — they tell you the market is enlarging rapidly, but they do not remove the hard choices companies must make about platform architecture, capital allocation, and regulatory sequencing in 2026.
Bioreactors and Fermenters Market
Why this study matters for 2026 strategic moves
- Decision timing: The pace of growth means that delaying a deployment or a technology pivot can result in meaningful missed market share within a 24–36 month horizon. Capital plans approved in 2026 will largely determine a player’s competitiveness through 2029–2030.
- Technology and business-model divergence: The market is experiencing parallel trajectories — scalable single‑use solutions, stainless-steel stalwarts for high-volume runs, and newer sterilization and process-intensification approaches. Each implies different CapEx/Opex profiles and supplier ecosystems.
- Regulatory acceleration: New regulatory frameworks and programs (U.S. expedited manufacturing designations and pilot programs, plus European legislative initiatives) are lowering some barriers to faster commercialization for bioreactor-enabled processes. That creates opportunities for companies who preemptively align processes and validation strategies with these pathways.
- Concentration and competition: The market remains relatively fragmented (our concentration measures show the top three and top five vendors capture a modest share of the market), which both opens partnership opportunities and intensifies procurement complexity for large buyers.
Market trajectory and the implications for corporate strategy
Viewed from the 2026 vantage point, the market’s trajectory supports three concurrent strategic playbooks: scale-to-demand, modular flexibility, and cost-per-dose (or per‑unit) optimization. The aggregated market numbers — historical growth through 2025 and our forecast to 2032 — validate investments in expansion, but the optimal route differs by organizational role:
Bioreactors and Fermenters Market
- For established OEMs and integrators: prioritize platform breadth and validated scale-up paths that shorten time‑to‑revenue for customers moving from pilot to commercial runs.
- For biopharma and vaccine manufacturers: prioritize flexible assets that reduce time-to-market and enable multi-product utilization, while stress-testing supply-chain and single-use consumable dependencies.
- For new entrants and niche technology providers: target demonstrated unit‑economics improvements (e.g., lower capital intensity, reduced sterilization cycle time) and secure early strategic partnerships with CDMOs or system integrators.
Regulatory and policy tailwinds — what to factor into 2026 plans
Recent regulatory developments alter execution risk and speed for projects started in 2026. Finalized guidance that enables advanced manufacturing designation pathways in the U.S., the launch of facility pilot programs designed to streamline review of novel manufacturing lines, and European policy initiatives aimed at strengthening industrial biotech infrastructure all serve to reduce time‑to‑market for eligible programs. Practically, this accelerates the payoff period for investments in modern bioreactor capabilities but places a premium on compliance readiness and early regulator engagement.
Bioreactors and Fermenters Market
Competitive landscape — who matters and what they signal
Our competitive analysis synthesizes supplier portfolios, strategic positioning, and near‑term moves that matter to buyers and investors. Core players profiled in the study include:
- Sartorius AG (Göttingen, Germany): A leading supplier of both single‑use and stainless‑steel platforms covering a wide working‑volume spectrum, with integrated automation that supports scalability from lab to production.
- Danaher Corporation / Cytiva (Washington, DC, USA): Offers the Xcellerex family of single‑use systems with expanded large‑scale options for clinical and commercial vaccine and cell-culture manufacturing — a clear signal that demand for bigger single‑use reactors is maturing.
- Thermo Fisher Scientific (Waltham, MA, USA): Focuses on single‑use systems optimized for perfusion and fed‑batch processes, including small‑scale options that bridge academic GMP and commercial R&D needs.
- Merck KGaA (Darmstadt, Germany): Provides both single‑use and stainless solutions with specialized variants for high‑density and high‑complexity biologic processes.
- Eppendorf AG (Hamburg, Germany): Competes strongly in lab‑to‑pilot systems and multi‑reactor platforms that are attractive to R&D groups and translational-scale manufacturing.
- Solaris Biotech Solutions (Mantua, Italy): Positions on benchtop to industrial fermenters with strong service and CIP/SIP capabilities for microbial and cell-culture customers.
- Biosphere (Oakland, CA, USA): Exemplifies a capital‑light disruption narrative with UV‑sterilized reactors targeting industrial fermentation and claims of materially lower capital intensity.
Recent vendor actions — larger single‑use capacity introductions, small‑scale GMP devices for academia, and product launches claiming reduced capital intensity — are converging on two themes: enabling faster scale‑up, and lowering the cost and lead time of facility deployment. The market rewards suppliers that can demonstrate validated scale-up, supply security of consumables, and integrated automation that reduces operator burden.
Recent developments that change the playbook
- Biosphere’s 2025 launch of a UV‑sterilized platform — backed by seed funding and government contracts — spotlights low‑capex pathways to industrial fermentation and is attracting attention from contract manufacturers and commodity producers seeking rapid facility builds.
- Cytiva’s expansion of the Xcellerex single‑use platform to larger working volumes in 2025 signals supplier confidence in single‑use for commercial‑scale vaccine and cell‑culture processes.
- Thermo Fisher’s introduction of a small‑scale DynaDrive unit in 2025 highlights continued demand for GMP‑compliant devices tailored to academic and early clinical workflows, underscoring a market bifurcation between bench‑scale agility and commercial intensity.
- European regulatory proposals released late in 2025 create new incentives and funding pathways for industrial biotech projects — a development that should be factored into European capex prioritization.
What the full PW Consulting report delivers (practical and actionable)
This study is structured for executives and technical leaders who need to translate market opportunity into executable plans. Key deliverables include:
- Market sizing and validated growth scenarios (historical 2020–2025 and a 2026–2032 forecast) that drive portfolio prioritization and M&A screening;
- Vendor benchmarking and vendor‑selection frameworks that evaluate technology fit, scale-up provenance, consumable supply risk, and total cost of ownership over 5–10 year horizons;
- CapEx/Opex models and ROI templates tailored to biologics, vaccine, and industrial fermentation use cases — enabling rapid sensitivity testing under alternative throughput and utilization assumptions;
- Scale‑up and scale‑out roadmaps, including qualification and validation checklists aligned to newly emerging regulatory fast‑track programs;
- Procurement playbooks and contracting guardrails for single‑use consumables and service SLAs, addressing continuity risks and lock‑in scenarios;
- Technology maturity maps and a short list of pragmatic pilot projects (three–nine month pilots) to derisk adoption of novel sterilization and process‑intensification technologies;
- Strategic M&A and partnership theses informed by market fragmentation metrics and identified white spaces where consolidation or capability buys will materially shorten time‑to‑market.
Practical recommendations for 2026 decision cycles
- Front‑load regulatory alignment: Integrate regulatory engagement into project inception. Facilities and processes designed with the new expedited pathways in mind will have materially shorter commissioning timelines.
- Adopt a dual‑track capacity strategy: Combine modular single‑use lines for product diversity and stainless systems where per‑unit economics at scale favor fixed infrastructure; prioritize interoperability and shared automation frameworks.
- Stress test supply chains: Evaluate consumable single‑source exposure and qualify alternate suppliers or hybridized systems to avoid production disruptions during scale‑up peaks.
- Invest in digital process controls: Automation, PAT, and remote monitoring accelerate scale‑up and reduce validation cycles — a high impact, relatively moderate investment with quick operational payback.
- Run focused pilots: Validate sterile UV or other novel sterilization technologies at pilot scale tied to clear economic gates before committing to plant conversions.
Conclusion — what to do next
The bioreactors and fermenters market in 2026 is a high‑growth field with clear structural shifts driven by technology, regulation, and evolving business models. Our analysis shows that the aggregate opportunity is substantial and accelerating, but the pathway to capturing value is nuanced: it demands tight integration of product strategy, regulatory planning, and sourcing discipline.
PW Consulting’s full report provides the granular, actionable intelligence you need to convert the market’s growth into a defensible competitive position — including regional and application splits, supplier scorecards, financial models, and procurement templates. For teams making capital or strategic choices in 2026, the right data and frameworks now will determine whether you lead or follow as the market scales.
Access the full analysis
To obtain the detailed datasets, interactive financial models, and procurement playbooks referenced in this preview — including region- and application‑level breakdowns and vendor benchmarking — please visit our report page or contact your PW Consulting advisor. The preview above deliberately omits the granular segmentation and proprietary scenario outputs reserved for the full study to ensure actionable exclusivity for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Bioreactors and Fermenters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com