

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Programmable Stage Lighting Market to Reach USD 259.78M by 2032 at 7.25% CAGR

Programmable Stage Lighting Market — Strategic Primer for 2026 Decision-Makers
Executive snapshot
At PW Consulting, we treat the Programmable Stage Lighting market as a systems play — where optics, power electronics, control architectures and software converge to shape audience experiences and operational economics. Our new study (base year 2025, historical series 2020–2025, forecast 2026–2032) synthesizes commercial, regulatory and technology forces into an actionable roadmap for leaders preparing strategic moves in 2026.
Programmable Stage Lighting Market
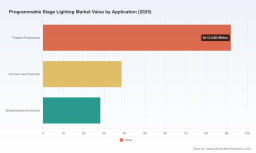
Key macro takeaways: the market has expanded from roughly USD 120 million in 2020 to about USD 159 million in 2025 and is projected to grow at a mid-single-digit compound annual growth rate (CAGR) through 2032, reaching approximately USD 260 million at the end of the forecast period. That trajectory represents steady, demand-led expansion driven by energy-efficient LED adoption, greater programmability across event categories, and the emergence of control-layer interoperability standards.
Programmable Stage Lighting Market
Why this matters for 2026 strategy
- Investment horizon alignment — The revenue runway through 2032 allows companies to rationalize multi-year R&D and productization efforts that prioritize digital control and energy efficiency without overreaching on short-term returns.
- Regulatory and standards timing — Compliance investments (energy efficiency mandates, RoHS/CE requirements) and DALI‑2 certification cycles are now hard gating market access in major markets; timing product launches around certification milestones will materially affect adoption.
- Competitive posture — The market exhibits moderate concentration (top-three and top-five shares indicative of meaningful incumbency but open pockets for innovation-led entrants). This creates balanced conditions for consolidation, niche specialization, and platform plays.
What the report delivers (practical deliverables)
We designed the study to be a playbook for executives, product leaders, M&A teams, and commercial strategists. Highlights include:
Programmable Stage Lighting Market
- Market architecture and value-chain mapping that ties fixture hardware, control protocols (DMX, sACN, DALI‑2), power electronics, and software platforms to buyer personas (rental houses, venues, broadcasters, touring productions).
- A robust market-sizing and scenario model (baseline, conservative, upside) covering 2026–2032 with sensitivity levers for energy regulation, supply constraints, and demand shocks.
- Supplier benchmarking: technology scorecards, go-to-market profiles, channel economics, and aftermarket/service positioning for the leading manufacturers and controls specialists.
- Commercial playbooks: product portfolio prioritization, pricing strategy templates based on total cost of ownership (TCO) calculus, and rental vs. ownership decision matrices for customers.
- M&A and partnership guidance: target screening criteria, valuation multiples observed in adjacent segments, and integration checklists focused on software and control interoperability.
- Implementation roadmaps for compliance (DALI‑2, RoHS, CE) and energy-efficiency retrofits that minimize revenue disruption while unlocking lifecycle savings.
Competitive landscape — dynamics and strategic postures
The competitive map blends heritage theatrical suppliers, entertainment-focused innovators, lighting-component OEMs, and specialty control-software houses. Incumbents maintain strengths in reliability, service networks and channel relationships; challengers win on feature velocity and software-enabled differentiation.
- Electronic Theatre Controls (ETC) — A legacy theatrical control and fixture player emphasizing integrated theatrical consoles, fixture families and gateways that bridge DMX and DALI ecosystems. Recent product development on DALI‑2 gateways reflects a clear play to simplify integrator workflows where DALI integration is a procurement requirement.
- Signify (Vari‑Lite) and Martin Professional (HARMAN) — These players lean into automated fixtures and touring-grade robustness. Their scale and distribution enable them to defend premium touring and large-venue segments.
- Robe, Clay Paky, Ayrton — European innovators that push optical quality and precise motion control; they tend to lead on fixture performance and bespoke feature sets for high-end productions.
- Chauvet, ADJ, Elation — Cost-efficient producers that extend programmability to broader install and mid-tier rental markets with aggressive price-performance propositions.
- Component and lighting‑engine suppliers (Osram, LumenPulse) — These firms are critical upstream partners. Their LED engine and driver innovations directly affect fixture efficiency, color rendering and lifecycle economics.
- Controls and laser specialists (Pangolin, Chromateq) — Providers of laser fixtures and control systems are doubling down on software functionality and trade-show visibility, signaling continued demand for high-impact visual effects that require precise synchronisation with control ecosystems.
Notable recent moves underscore two themes: deepening interoperability and show-oriented innovation. Examples include new DALI‑2 gateway launches and control-software upgrades showcased at major industry events. These are harbingers of a market where product success increasingly rests on ecosystem compatibility and software update pathways.
Regulatory and standards environment — operational impacts
Regulatory forces are no longer background noise. Energy efficiency mandates, CE/RoHS compliance obligations and the rise of DALI‑2 as the interoperability standard create both cost and strategic opportunity:
- Compliance increases upfront engineering and certification spend, but reduces operating costs for end users — a point that can be monetized through TCO-based sales motions.
- DALI‑2 certification lowers integration friction in installed systems; suppliers that offer certified gateways and clear migration paths for legacy DMX infrastructures will capture preference in retrofit and specification-driven projects.
- LED dominance in fixture designs reduces energy consumption and maintenance but shifts competitive focus to optics, thermal management and control latency.
Where the pockets of opportunity are in 2026
- Software-first differentiation: invest in cloud-enabled content management, fixture emulation libraries and remote firmware delivery to create recurring revenue streams and lock-in.
- Control-layer convergence: develop certified DALI‑2 gateways and tested sACN/Art-Net bridges to be the integrator’s preferred choice for mixed-protocol deployments.
- Service and financing: offer lifecycle service agreements and asset-financing programs targeting rental houses and venues to accelerate adoption without depressing realized prices.
- Product modularity: create scalable fixture platforms with pluggable optics and control modules to address both touring and fixed-install requirements with lower SKUs and faster market fits.
- Sustainability and circularity: position refurbishment and component-replacement programs to capitalize on regulatory-driven retrofit cycles and to address large installed bases seeking emissions reductions.
Risks and mitigants
- Supply-chain concentration: diversify sourcing for critical LEDs and driver ICs; adopt multi-sourcing strategies with strategic buffer inventories tied to forecast risk triggers.
- Certification lead times: begin compliance and testing processes early (DALI‑2, CE/RoHS) to avoid launch delays and lost specification lists.
- Channel conflict: if pursuing direct SaaS-enabled control platforms, implement clear partner economics and co-sell models to avoid undermining distributor/rental relationships.
How to use the full report in your 2026 planning cycle
Use the study as the backbone for three 90-day sprints:
- Sprint 1 — Compliance and product roadmap: map certification timelines into product development milestones and prioritize gateway/fixture pairings for early-market programs.
- Sprint 2 — Commercial model test: pilot TCO-based pricing and bundled service agreements with a subset of rental and venue partners; track uptake and margin elasticity.
- Sprint 3 — M&A and partnerships: apply our target-screen framework to shortlist capability buys (controls software, optics startups) and structure earn-out mechanisms tied to integration KPIs.
Closing — what we recommend you do next
The programmable stage lighting market in 2026 is a landscape of incremental hardware gain and exponential software opportunity. Firms that treat fixtures and controls as a combined product-service system — and that manage certification timelines as strategic levers — will secure outsized returns as the market grows toward the end of the decade.
PW Consulting’s full report contains the underlying forecast model, supplier scorecards, pricing frameworks and proprietary interviews that substantiate these conclusions. We intentionally reserve the detailed segmentation tables and transaction-level data for subscribers. For a tailored briefing and to access the complete dataset and executable playbooks, please visit our research page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Programmable Stage Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com