

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Premix Burners Market Poised for 5.2% CAGR

Premix Burners Market — Strategic Imperatives for 2026: A PW Consulting Preview
As energy transition pressures, emissions regulation, and fuel diversification converge, premix burner technology has moved from niche optimization to boardroom-level strategic priority. This PW Consulting preview summarizes the strategic value of our full Premix Burners Market study and outlines the specific decisions executives must make in 2026 to capture value and mitigate risk. The full report contains the granular segmentation, supplier scorecards, and scenario-based financial models that underpin the recommendations below; this preview deliberately highlights insight and recommendations while withholding the proprietary microdata that commercial users rely on.
Premix Burners Market
Executive snapshot — market scale and trajectory
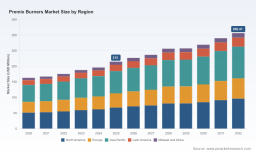
Between 2020 and 2025 the premix burners market expanded meaningfully, reflecting stronger demand for higher-efficiency combustion solutions across industrial, commercial, and residential end uses. In 2025 the market reached a notable base year milestone, and our forecast projects continued expansion through the 2026–2032 horizon at a mid-single-digit compound annual growth rate (CAGR) of 5.2%. Under the base-case scenario embedded in our study the market progresses steadily across the forecast period, reflecting a combination of regulatory-driven retrofits, new-build industrial throughput, and technology-driven upgrades (notably low-NOx, hydrogen-capable, and porous-media burners).
Premix Burners Market
Why this matters for 2026 decision-making
- Regulatory compliance is now a primary growth lever and a cost sink: tightening NOx/CO limits across major jurisdictions force capital spending on advanced premix systems for many industrial heat applications. Companies that pre-emptively retrofit or specify compliant technologies capture both compliance upside and operational cost advantages.
- Fuel flexibility is strategic: hydrogen-capable designs and hybrid fuel strategies are transitioning from experimental to commercially available options. Early mover product launches in 2025–2026 signal an inflection point where hydrogen readiness becomes a differentiator for OEMs and end-users alike.
- Consolidation and supplier concentration alter bargaining dynamics: the market shows high concentration at the top end (the top three players capture a substantial share, with the top five even more so). Strategic sourcing, long-term OEM partnerships, and selective M&A are therefore central to securing supply and capabilities.
- Incremental efficiency gains compound: modest efficiency improvements in burner design translate into meaningful fuel and emissions reductions at scale — a crucial consideration for industrial operators facing decarbonization targets and energy cost volatility.
Market dynamics shaping near-term strategy
Several structural forces interplay to create a dynamic landscape for 2026 strategy:
Premix Burners Market
- Regulatory drivers: The EU’s Industrial Emissions Directive, U.S. EPA hazardous air pollutant standards, China’s Air Pollution Prevention and Control Law, and regional energy codes (e.g., India’s energy efficiency building codes) collectively tighten emissions and efficiency requirements. Compliance timelines are staggered geographically, shaping where retrofit demand will concentrate first.
- Technology diffusion: Metal fiber, ceramic and advanced porous mediums continue to compete on lifetime cost, turn-down ratio, and NOx performance. Manufacturers are also integrating controls and air/gas ratio management to optimize combustion stability and emissions across varying fuel blends.
- Fuel transition and hydrogen readiness: 2025–2026 product introductions show hydrogen-capable premix burners moving to commercialization. This requires re-evaluating materials, safety systems, and supply chains — and creates an opportunity for early adopters to lead in hydrogen-compatible heating solutions.
- Supply chain and manufacturing inputs: Premix burners rely on high-temperature steels, metal fiber elements, and ceramic components. Price volatility or availability shocks in these inputs affect lead times and margins, making supplier diversification and vertical integration levers of value.
Competitive landscape — what the leaders are doing
The competitive field combines global industrial groups, specialty burner manufacturers, and regional engineering houses. Market concentration is high — the top three players collectively command the majority of share, and the top five increase that dominance further — creating asymmetries in pricing power, channel reach, and R&D scale.
- Established incumbents focus on scale and compliance: Firms with broad combustion portfolios are driving uptake through packaged solutions, integration with boiler/OEM systems, and compliance-driven retrofits. Expect continued investment in rule-of-law geographies where regulatory enforcement is strongest.
- Specialists differentiate on technology and niche applications: Companies with depth in metal fiber, porous ceramic, or ultra-low NOx solutions are leveraging performance differentiation into specialty industrial segments and aftermarket services.
- Regional players compete on cost and local relationships: Several manufacturers capitalize on lower-cost production and strong regional distribution to serve retrofit markets and commodity-driven industrial segments.
Notable recent developments illustrate these trends: in early 2026 a major equipment supplier launched a hydrogen-capable premix burner targeted at asphalt production, and in 2025 a regional manufacturer unveiled what it described as a domestic hydrogen burner and a very large-capacity industrial burner. These moves confirm two themes — product innovation toward hydrogen compatibility and ongoing investments in heavy industrial capacity.
What the full PW Consulting report contains (practical, actionable content)
Our full study is designed as a playbook for commercial, engineering, and corporate development teams. Key deliverables include:
- Validated market sizing and a seven-year forecast with scenario pathways (base, conservative, and accelerated hydrogen adoption cases)
- Segmentation across technology, application class, and region with demand drivers and elasticity analysis (note: detailed unit and revenue splits are in the full report)
- Competitor benchmarking and capability maps, including product portfolios, geographic reach, and technology stacks for the leading OEMs and niche specialists
- Technology assessment: comparative performance, lifecycle cost models, hydrogen readiness scorecards, and retrofit versus new-build economics
- Regulatory impact matrix showing compliance timelines, enforced thresholds by jurisdiction, and likely retrofit windows
- Supply chain stress tests: supplier concentration, input price sensitivity, and suggested mitigation strategies (dual sourcing, component stocking, vertical partnerships)
- Commercial playbooks: go-to-market recommendations by segment, channel optimization (OEM, direct, distributor, aftermarket), and pricing tactics
- M&A target shortlists and integration considerations for acquiring combustion capabilities or complementary controls expertise
- Risk register and monitoring dashboard for 2026–2028 decision cycles
Strategic playbook for 2026 — prioritized actions
Leaders must act on three time horizons: immediate (0–12 months), tactical (12–24 months), and strategic (24–60 months). Our analysis yields a prioritized set of actions:
- Immediate (0–12 months)
- Map your exposure to tightening emissions limits and identify assets requiring urgent retrofit. Prioritize high-operating-hour assets where ROI is fastest.
- Engage top-tier burner OEMs to secure supply windows and lock-in performance guarantees tied to emissions and fuel-flexibility specs.
- Begin pilot evaluations of hydrogen-capable burners in controlled applications where safety and operational risk can be contained.
- Tactical (12–24 months)
- Standardize technical specifications across projects to reduce engineering customization and accelerate procurement.
- Negotiate bundled maintenance and aftermarket service contracts to capture lifecycle efficiency gains and reduce total cost of ownership.
- Implement supplier risk mitigation: multi-sourcing critical components (metal fiber elements, high-temp ceramics) and exploring local fabrication partnerships.
- Strategic (24–60 months)
- Pursue M&A or JV activity to acquire combustion controls, hydrogen-handling expertise, or specialized porous-media manufacturing where market presence is weak.
- Invest in digital-first combustion controls and monitoring systems to enable predictive maintenance, emissions reporting, and remote optimization.
- Define a hydrogen transition roadmap tied to regional fuel availability and regulatory incentives; structure capital projects to be retrofit-ready for blended fuels.
Risk scenarios and hedges
We model three core scenarios that materially affect market outcomes and strategic choices:
- Regulatory acceleration: faster tightening of emission limits increases retrofit demand and benefits incumbents with certified low-NOx solutions.
- Hydrogen adoption: subsidy-driven adoption of hydrogen in select industries creates premium markets for hydrogen-capable burners but raises safety and materials requirements.
- Supply-chain disruption: shortages or price spikes in metal fiber and high-temp ceramics raise lead times and margins, favoring vertically integrated players.
Recommended hedges include staged CapEx with retrofit triggers, investment in controls that reduce fuel use (thereby lowering exposure to fuel price swings), and contractual mechanisms with OEMs to share retrofit risk under evolving fuel mixes.
How PW Consulting’s study creates value for your 2026 planning
Our report translates market trajectory, technology diffusion, and regulatory momentum into concrete actions: prioritized retrofit lists, supplier scorecards, investment sizing templates, and an M&A watchlist that aligns with corporate decarbonization and operational resilience goals. The study’s base-year calibration and multi-scenario forward view provide finance, operations, and strategy teams with a defensible framework to allocate capital and organize cross-functional execution in 2026.
Next steps — where to get the full intelligence
This preview highlights the strategic contours of the premix burners market; however, the full competitive scorecards, regional demand matrices, and financial models are deliberately withheld here to protect the proprietary work that drives our clients’ decisions. PW Consulting clients and subscribers can access the complete report, downloadable datasets, and bespoke briefing sessions through our market research portal. For teams evaluating specific acquisition targets, sourcing strategies, or regulatory compliance programs, we offer tailored workshops that translate the report’s findings into executable project plans.
Contact PW Consulting to schedule a briefing and receive the full Premix Burners Market study — including the detailed segmentation, vendor comparisons, and scenario-tailored investment cases that are essential for confident 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Premix Burners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com