

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steam Boiler Market to Reach $236.98M by 2032 with 4.12% CAGR

Steam Boiler System Market — 2026 Strategic Brief (PW Consulting)
Executive snapshot
Our Steam Boiler System Market study (base year 2025) synthesizes seven years of historical behaviour and a seven‑year forecast window to provide a clear line of sight for 2026 corporate decision-making. The market expanded from roughly USD 145 million in 2020 to about USD 180 million in 2025 and is projected to grow to roughly USD 237 million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.12% across the forecast period. These headline figures mask important structural shifts — from product modularity and digital services to regulatory-driven retrofit demand — that will determine winners and losers across OEMs, system integrators, financing partners and end‑user segments.
Steam Boiler System Market
Why this study matters for 2026 decisions
-
Capital allocation: The market’s steady mid-single-digit growth invites selective investments rather than broad, high‑risk expansion. Knowing which technology and service bets deliver the highest risk‑adjusted returns in 2026 is essential for CFOs preparing mid‑cycle budgets.
Steam Boiler System Market -
Product roadmap prioritization: A single product bet is no longer sufficient. The balance between compact/modular boilers, utility‑scale systems, and electrified or hybrid designs is now a strategic choice that affects engineering, channel strategy and aftermarket economics.
Steam Boiler System Market -
M&A and partnership choreography: Fragmented supply and intermediate concentration metrics create pockets where bolt‑on acquisitions or strategic alliances generate scale quickly. The market concentration metrics in our study show meaningful room for consolidation and targeted roll‑ups that capture aftermarket value.
-
Regulatory and compliance planning: Safety and inspection codes, plus an accelerating focus on emissions and efficiency, will create near‑term retrofit windows. Companies that map regulatory triggers to commercial offerings can accelerate revenue capture with lower customer acquisition costs.
-
Service and financing models: With CapEx constraints and growing interest in performance contracting, service, financing and outcome‑based commercial models are a practical lever to expand wallet share and margin.
What the report delivers — practical, decision‑grade content
Our research was structured with the buyer and strategist in mind. The full report is modular and built around actionable deliverables that a leadership team can use immediately:
-
Detailed market sizing, with scenario pathways and sensitivity analyses that translate macro forecasts into revenue and EBITDA expectations for adjacent product lines.
-
Competitor profiles and a proprietary competitive strength matrix highlighting product breadth, systems integration capability, geographic reach and aftermarket penetration.
-
Commercial playbooks for OEMs and channel partners: go‑to‑market tactics by customer type, pricing ladders, service bundles, and contract templates for outcome‑based deals.
-
Regulatory and compliance checklist tailored to U.S. federal and state frameworks and major international regimes — a practical set that feeds directly into project risk registers and tender qualification criteria.
-
Investment due diligence kit (financial models, valuation sensitivity tables, and integration checklists) for M&A and JV activity.
-
Digitalization and retrofit ROI calculators that map sensorization, controls upgrades and predictive maintenance investments to payback periods under multiple fuel‑price scenarios.
-
Supplier evaluation framework and shortlists for component, controls and aftermarket partners — enabling procurement teams to expedite vendor selection while retaining negotiation leverage.
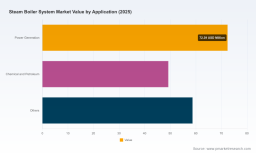
Note: the report intentionally withholds granular regional/application breakouts from this brief; these segment tables, revenue waterfalls and downloadable excel models are available in the full deliverable.
Competitive landscape — who matters and why
The market is characterised by a mix of global industrial majors, regional specialists and focused innovators. Measured concentration metrics indicate limited dominance by the very largest firms — enough to keep price discipline but leaving meaningful opportunity for nimble challengers and regional champions. The competitive dynamics unfold across three vectors: product architecture (packaged vs bespoke), systems integration (controls and heat‑recovery integration), and aftermarket services (maintenance, spare parts, and performance contracts).
-
Cleaver‑Brooks (Milwaukee, USA): Known for packaged industrial steam boilers and integrated systems, with a strong footprint in manufacturing and process applications. Their playbook emphasizes turnkey solutions and channel partnerships.
-
Fulton Boiler Works (Pulaski, USA): Focused on energy‑efficient gas, oil and electric boilers and packaged systems. Fulton’s differentiation stems from engineered standardization that targets low installation cost and rapid deployment.
-
Miura Boiler (Japan): A leader in compact, modular, gas‑fired boilers. Miura’s strength is speed‑to‑steam through modular scalability — a clear advantage in retrofit and constrained‑space applications.
-
Hurst Boiler and Welding (Coolidge, USA): Offers a broad fuels portfolio including biomass options. Hurst competes on durability and multi‑fuel flexibility, appealing to customers prioritizing fuel security and transition options.
-
Bosch Industriekessel (Germany): European integrated systems expertise with advanced controls — strong where customers require close automation and integration with facility energy management systems.
-
Alfa Laval (Sweden): Positioned around heat‑transfer and exchanger solutions that complement boilers, Alfa Laval’s systems approach adds incremental efficiency gains in multi‑equipment plants.
-
Thermax (India): A regional systems integrator offering full boiler systems for process industries, with a strong bias toward emerging market project execution and bundled finance models.
-
Babcock & Wilcox (USA): Focused on utility‑scale and large industrial boilers, where plant integration and lifecycle engineering are the primary value drivers.
-
Siemens Energy (Germany): Brings advanced hybrid and steam generation solutions, pairing boilers with broader energy‑system optimization capabilities.
-
Doosan Enerbility (South Korea): Specialist in large‑scale steam boilers and systems for utilities and heavy industry, emphasizing project scale and turnkey delivery.
Strategic takeaway: in 2026, differentiation will come from two combinations — systems integration + aftermarket services, and modular product architectures enabling fast, low‑risk installations. Players that can pair technology differentiation with flexible commercial models will capture disproportionate share of growth.
Market dynamics and regulatory context
Several structural forces are shaping near‑term demand:
-
Regulatory compliance and safety: Longstanding safety codes (for example, federal and state provisions that require safety valves and ASME code adherence) continue to set minimums for capital projects and inspections. Compliance timelines create windows for retrofits and equipment replacement.
-
Efficiency and decarbonization pressure: Customers are prioritizing fuel efficiency, emissions reduction and options for electrification or biomass co‑firing, driving demand for retrofit controls and hybrid system designs.
-
Commercialization of modularity: Compact, modular boilers reduce installation time and total cost of ownership for brownfield projects, increasingly preferred by process plants with constrained downtime windows.
-
Commercial channel evolution: Trade shows and sector events through 2026 — including major expos where multiple OEMs showcased packaged systems, controls and efficiency technologies — demonstrate an industry pivot to systemized, service‑centric offerings.
These dynamics mean that regulatory noise is not merely compliance overhead — it is a commercial signal. Firms that map regulatory cycles to sales and service execution calendars can preempt competitors and invoice for compliance‑driven upgrades.
Strategic implications and recommended 2026 actions
-
Prioritize modular and retrofit offerings: Reconfigure product portfolios to include compact modular solutions that shorten lead times and lower installation disruption — critical for winning retrofit opportunities in 2026.
-
Monetize aftermarket: Create subscription or outcome‑based maintenance offerings, backed by predictive analytics, to convert installed bases into annuity revenue.
-
Invest selectively in controls and digital platforms: Controls integration is the margin battleground. Invest in interoperable control stacks and data services that improve plant efficiency and justify premium pricing.
-
Use M&A to fill capability gaps: Target acquisitions that add systems integration, regional execution capability, or aftermarket reach rather than incremental product lines.
-
Align procurement to risk scenarios: Build fuel‑price and carbon regulation scenarios into procurement and pricing models to protect margins under volatility.
-
Operationalize regulatory intelligence: Convert regulatory timelines into a lead generation and project prioritization engine for sales and service teams.
Next steps — where to get the full playbook
This briefing surfaces the strategic contours for 2026 decision-making while preserving the proprietary segment analytics and supplier scorecards that drive execution. PW Consulting’s full Steam Boiler System Market report includes the complete segmented tables, downloadable financial models, vendor shortlists, and templated commercial agreements that your team can deploy immediately. For executives preparing budgets, M&A teams running screens, or product leaders defining roadmaps, the full report converts the market’s 4.12% CAGR and forecast trajectory into operational targets and measurable KPIs.
To access the complete dataset, scenario models and implementation templates, please consult our full report and client portal where detailed regional and application breakouts, supplier scorecards and ROI calculators are available for licensed users.
For detailed analysis of this topic, please visit the official page: Steam Boiler System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com