

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Green Roof Market to Reach USD 6.65M by 2032 at 15.3% CAGR

Green Roofs 2026: Strategic Signals from PW Consulting’s Market Preview
As urban sustainability climbs corporate and municipal agendas, green roofs have shifted from niche pilot projects to scalable infrastructure options. PW Consulting’s Green Roof Market Preview synthesizes market dynamics, regulatory drivers, supplier strategies, and actionable scenarios to inform executive decisions through 2026 and beyond. Below we outline the strategic value of the full study, highlight high‑impact findings, and present the question set every executive should be able to answer before allocating capital or launching new offers in this space.
Green Roof (Green-Roof) Market
Why this preview matters for 2026 decision-making
-
A rapidly expanding market: The global green roof market has shown sustained, above‑average growth in the past half‑decade, accelerating further into our forecast horizon. Measured from the 2025 base year, the market trajectory we model implies a compounding growth profile that demands proactive positioning rather than reactive entry.
Green Roof (Green-Roof) Market -
Time-sensitive windows for scale: With a forecast CAGR of 15.3% across the 2026–2032 period, the next 12–18 months represent a critical window for firms to secure channel partners, test modular product concepts, and lock in supply agreements without being squeezed by late‑cycle price pressure.
Green Roof (Green-Roof) Market -
Regulation and reimbursement are amplifiers: Local stormwater rules, municipal incentive programs, and tax abatements have shifted green roofs from voluntary sustainability upgrades to economically defensible solutions in many jurisdictions. These policy levers are heterogeneous—creating both opportunities and execution complexity for firms able to navigate local requirements.
What PW Consulting’s full report delivers (practical, executable content)
-
Market sizing and forward scenarios: A transparent baseline anchored to 2025 with scenario‑based outlooks through 2032. We provide topline revenue curves and sensitivity analyses that help translate market growth into addressable opportunity for product lines, installation services, and maintenance contracts.
-
Commercial playbooks: Go‑to‑market templates for OEMs, installers, and engineering firms—covering spec‑first sales, municipal procurement, public‑private partnership (PPP) structures, and bundled financing models. Each playbook includes staffing profiles, key KPIs, and a three‑phase implementation roadmap designed for 12–24 month horizons.
-
Operational readiness checklists: Practical guidance on rooftop structural assessment protocols, lightweight media sourcing, irrigation integration, and maintenance contracts that preserve warranty and performance certification. These checklists are designed for quick deployment by project managers and sustainability leads.
-
Competitive benchmarks and acquisition targets: A curated universe of vendors, component specialists, and materials providers profiled against capability matrices—useful for M&A screening and partnership diligence.
-
Regulatory intelligence and incentives map: A synthesis of current regulatory drivers, stormwater credit frameworks, and tax incentive archetypes to support site-level business case modeling without having to reinvent municipal research for each opportunity.
Market structure and strategic implications
The green roof market remains fragmented, creating room for consolidation and specialization. Our concentration metrics point to low market share for top players relative to total market size, signaling buyer fragmentation and a strong role for differentiated product and service models. For corporations considering entry or expansion, this fragmentation creates three adjacent strategic plays: scale through modular systems, specialize in engineered growing media and O&M, or compete on integrated offerings that combine waterproofing, stormwater management, and vegetation warranties.
Competitive landscape — who’s shaping the ecosystem
The supplier ecosystem combines established waterproofing and roofing integrators, modular system suppliers, and specialist inputs such as engineered growing media. Notable firms include long‑established waterproofing and assembly manufacturers, modular tray suppliers, media specialists with significant square‑footage experience, and manufacturers of moisture protection and accessory components. These players are advancing product portfolios and digital tools to capture higher-margin downstream services.
Recent market activity underscores a few industry‑level themes:
-
Product modularization and integration: Several firms have launched new modular systems and built‑in‑place layered assemblies, enabling faster installation cycles and improved stormwater performance characteristics.
-
Convergence with other urban infrastructure: Hybrid solutions that integrate photovoltaic systems with vegetated platforms are moving from concept to commercial product, opening a new product category—bio‑solar roof systems—that combines energy generation and green infrastructure benefits.
-
Digital enablement: Suppliers are digitizing catalogs, presenting specification tools to design partners, and participating in industry forums to accelerate specification uptake among architects and landscape professionals.
Selected vendor dynamics (illustrative, non‑exhaustive)
-
Long‑standing waterproofing and roofing integrators are packaging certified garden roof assemblies that pair monolithic membranes with vegetated layers—strengthening value propositions for performance guarantees and insurance acceptance.
-
Modular tray and tray‑plus‑paver system providers are emphasizing rapid deployment, reduced rooftop dead load, and compatibility with rooftop access and amenity use—targeting urban retrofit projects.
-
Soil and media specialists are focusing on engineered substrates and specification tools for landscape architects, consolidating influence over plant performance and long‑term O&M economics.
Recent product launches and industry activity in early 2026 validate these trends: modular and layered systems were introduced alongside a push to integrate green roofs with solar technologies and digital product catalogs. Industry conferences continue to be a primary channel for specification education and market adoption among design professionals.
Key risks and mitigation strategies for 2026
-
Execution risk: Skilled installers and certified maintenance providers are a scarce resource in many markets. Mitigation: invest in installer training programs, certify partners, and lock in installation capacity through distribution agreements.
-
Supply chain risk: Engineered media and specialty components have concentrated manufacturing footprints. Mitigation: dual‑source critical inputs and localize media blends where possible to reduce freight and seasonal variability.
-
Policy volatility: Incentives and stormwater credit regimes change at the municipal level. Mitigation: maintain a local regulatory monitoring capability and include incentive sensitivity in every project financial model.
-
Lifecycle performance risk: Warranty exposure tied to vegetation health and irrigation. Mitigation: offer bundled service contracts and remote monitoring to manage risks and create recurring revenue streams.
Five targeted plays for executives in 2026
-
Spec‑first partnerships: Build early relationships with architecture and landscape design firms, offering specification‑grade tools and case studies to make your product the default choice when projects enter permitting.
-
Productize hybrid solutions: Pilot integrated solar + green roof systems in one or two high‑visibility municipal or commercial projects to create repeatable templates and measurable ROI stories.
-
Monetize O&M: Convert installation wins into multi‑year maintenance contracts with performance clauses tied to stormwater credits and vegetation health KPIs.
-
Localized supply strategies: Develop regional media blends and logistics playbooks to reduce cost and carbon intensity—an increasingly important selling point for sustainability procurement teams.
-
M&A and partnership scouting: Target specialist media producers, tray manufacturers, or digital specification tool startups to accelerate capability building while maintaining capital discipline.
What we intentionally do not disclose here (and why)
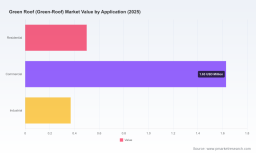
In keeping with the “trailer” approach of this preview, we present clear strategic signals while withholding proprietary granular segmentation tables and line‑by‑line regional/application shares. The full PW Consulting report contains detailed regional and application splits, vendor revenue benchmarks, and downloadable modeling templates that translate top‑line market growth into product‑level and project‑level profitably scenarios—essential material for bidding, M&A diligence, and board‑level investment decisions.
Next steps
Executives preparing 2026 budgets should prioritize three immediate actions: (1) commission a short site‑level portfolio review to identify near‑term retrofit candidates; (2) pilot a spec engagement with one architecture firm to capture early procurement mindshare; and (3) evaluate supplier options for media and modular systems to secure lead times. For teams requiring the full segmentation data, financial models, and vendor diligence appendices that underpin these recommendations, the complete PW Consulting Green Roof Market report provides the operative intelligence required to move from strategy to execution.
Contact PW Consulting to access the full study, proprietary datasets, and bespoke scenario modeling tailored to your portfolio or product roadmap.
For detailed analysis of this topic, please visit the official page: Green Roof (Green-Roof) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com