

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Concrete Vibrator Market to Expand at 4.8% CAGR Through 2032

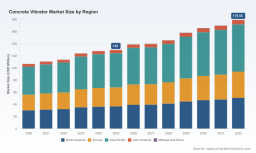
Concrete Vibrator Market: Strategic Brief for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concentrated strategic preview of our Concrete Vibrator Market research — designed to equip executives, product leaders, and corporate development teams with the insights required to make confident 2026 investment and operational decisions. The market has evolved beyond a simple equipment play; product architecture, ergonomic design, electrification, regulatory compliance and channel economics now determine winners. This brief synthesizes the research’s macro view, competitive dynamics, regulatory and innovation vectors, and the practical, executable intelligence contained in the full report — while preserving the granular segment tables and company-level revenue breakdowns for subscribers.
Concrete Vibrator Market
Why this market matters in 2026
The global concrete vibrator market reached USD 130.0 Million in 2025 (base year) after steady growth through the 2020–2025 period, and our forecast model projects expansion at a compound annual growth rate (CAGR) of 4.8% through 2032, reaching roughly USD 180 Million by the end of the forecast window. That trajectory reflects a combination of infrastructure refresh cycles, increased construction activity in selected markets, and a technology shift toward electrified, ergonomic and modular solutions that reduce labour intensity and improve quality control on site. For 2026 decision-makers, the implications are simple: product and channel strategies that align with these underlying drivers can convert moderate market growth into outsized returns.
Concrete Vibrator Market
Macro dynamics shaping opportunity
- Electrification and cordless mobility: Battery-powered and cordless backpack units have moved from niche to mainstream in innovation roadmaps, driven by site cable management concerns and a preference among contractors for cordless tooling systems. This change elevates battery-pack supply chains and creates cross-sell potential with power-system OEMs.
- Performance differentiation through frequency and control: High-frequency platforms with variable-speed control enable better consolidation performance across diverse concrete mixes. Variable-speed control also supports energy efficiency and operator safety compliance, making it a fast-emerging feature premium buyers will pay for.
- Ergonomics and modularity: Reduced weight, improved ergonomics and interchangeable shaft/head systems are changing replacement cycles and aftermarket revenue dynamics. Modular systems expand addressable use-cases and simplify rental/dealer stocking strategies.
- Regulatory and certification thresholds: Market access increasingly depends on international certifications and safety approvals. CE marking and similar approvals are gating factors for growth in developed markets, affecting product development timelines and go-to-market sequencing.
- Market structure and concentration: The market exhibits moderate concentration. The top three and top five incumbent groups provide meaningful competitive anchors, but a long tail of regional and specialist manufacturers keeps pricing pressure and innovation incentives high.
Competitive snapshot — strategic positions to watch
Our analysis covers global OEMs, specialist manufacturers and adjacent-tool incumbents that have recently expanded into concrete consolidation. Several strategic patterns stand out across the competitor set:
Concrete Vibrator Market
- Systems incumbents pursuing electrified mobility: Established manufacturers are launching high-frequency internal vibrators and cordless backpack models to capture demand among contractors who prefer reduced cable clutter and higher mobility on site. These offerings target a higher-margin segment of the market and align with broader electrification trends across construction equipment.
- Ergonomics and operator-first design: New platform iterations emphasize lighter weight, better handling and reduced vibration transfer to operators. Ergonomics has emerged as a purchase driver for mid-to-large contractors that quantify safety and productivity gains.
- Modular and interchangeable architectures: Suppliers emphasizing interchangeable shafts and multiple head options reduce the number of SKUs dealers must carry, supporting rental strategies and enabling faster fleet customization.
- Compliance-driven market entry: Recent certifications and market-specific launches demonstrate a strategic focus on regulatory-compliant entries into high-value regions; this is a necessary investment for suppliers serious about scale.
Representative entrants and their strategic plays (high-level):
- A group of legacy construction-equipment OEMs has moved to high-frequency internal platforms and battery-backed backpack units to defend share and pursue higher ASPs through technology bundling.
- Specialist manufacturers continue to compete on SKU breadth, flexible shaft offerings and OEM supply partnerships, maintaining relevance in regional markets and the rental channel.
- New and adjacent-tool entrants are leveraging cordless tool ecosystems to cross-promote battery systems and accessories, creating potential channel conflict but also cross-market synergies.
Recent moves and what they signal
- Multiple product launches in 2025–2026 show suppliers racing to commercialize electrified, high-cycle and ergonomically refined platforms. These are not incremental updates; they change procurement economics on job sites with constrained labour and strict timeline penalties.
- Certification wins in late 2025 and early 2026 underline the transactional importance of regulatory compliance for EU market access — a requirement that changes product release sequencing and distribution strategy.
- Platform launches at major trade shows mark a shift to system-level selling: tool + powerpack + service contracts — increasing lifetime revenue per customer if suppliers can unlock aftermarket service economics.
Practical implications for corporate strategy in 2026
- Product roadmap prioritization: If your business competes in internal vibrators or portable consolidation tools, prioritize investments in high-frequency motors, variable-speed control, battery-integration and ergonomic design. Time-to-market for certified variants will be a competitive differentiator in key buyer geographies.
- Channel & go-to-market alignment: Reposition channel incentives to support rental houses and dealer service capabilities. Rental penetration materially alters replacement cycles and increases the value of durable, serviceable designs.
- Aftermarket and service strategy: Build warranty and service propositions tied to preventive maintenance and quick-change modular components. Aftermarket margins can offset initial price competition in new product launch phases.
- M&A and partner criteria: Look for targets that add capabilities in battery systems, ergonomics engineering, certification track record, or dealer footprint in high-growth local markets. Smaller specialist OEMs with strong rental or dealer relationships are attractive tuck-in candidates.
- Supply chain resilience: Secure alternate sourcing for key subsystems (motors, battery packs, flexible shafts) and de-risk logistics for components subject to trade-policy or tariff exposure.
Risk factors and mitigants
- Price competition from low-cost manufacturers: Maintain a clear product differentiation and service play to protect margins; compete on total cost of ownership rather than unit price.
- Certification and regulatory delays: Proactively map certification timelines into product development and pre-market investments to avoid lost selling seasons in regulated markets.
- Channel fragmentation: Simplify SKUs where possible and invest in dealer training and digital ordering to reduce friction and inventory costs.
- Technology substitution: Monitor adjacent consolidation technologies and materials innovation that may change consolidation requirements; retain R&D optionality to pivot motor and shaft designs.
What the full PW Consulting report delivers (practical contents)
- Proprietary market model (2020–2032) with baseline, upside and downside scenarios driven by construction cycles and product-adoption curves.
- Competitive benchmarking by product architecture, channel strategy, certification status and aftermarket model.
- Detailed go-to-market playbooks for launch, dealer enablement, rental partnerships and OEM alliances.
- Pricing and margin matrices, including suggested pricing ladders for electrified vs. legacy platforms and regional go-to-market sensitivity analyses.
- Supply-chain heat map identifying critical component risk and recommended nearshoring/dual-sourcing actions.
- M&A target shortlists and valuation frameworks tailored to strategic buyers.
- Primary interviews with contractors, rental operators and dealers that validate feature willingness-to-pay and procurement preferences.
- Regulatory tracker and certification timelines for major markets, including EU compliance checklists and recommended testing roadmaps.
Note: this preview deliberately omits the granular regional, type and application revenue splits and individual company revenue breakdowns included in the full dataset — those tables, transaction views and downloadable models are available only in the complete report.
Recommended next steps for executives
- Secure the full PW Consulting report and Excel model to access the granular segmentation, dealer maps and company revenue benchmarks needed for actionable planning.
- Convene a cross-functional 90-day “market capture” sprint: product, supply-chain, sales and finance — with charter to define a launch sequence for an electrified/ergonomic variant and an aftermarket monetization plan.
- Initiate targeted diligence on potential acquisition targets that close capability gaps in battery systems, modular shafts, or certification expertise.
- Implement short-term channel pilots with rental partners in two prioritized markets to validate unit economics and refine TCO messaging.
In summary, the concrete vibrator market in 2026 offers predictable growth underpinned by structural product shifts rather than a cyclic boom. Companies that marry product innovation (electrification, high-frequency control, ergonomics) with intelligent channel and service models will extract disproportionate value. PW Consulting’s full report provides the granular data, scenario models and prescriptive playbooks required to convert strategic intent into measurable market share and margin gains. Contact PW Consulting to request the full report, the underlying Excel model, or a tailored advisory engagement to accelerate decision-making.
For detailed analysis of this topic, please visit the official page: Concrete Vibrator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com