

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pneumatic Components Market to reach USD 22.6B by 2032 at 6.46% CAGR

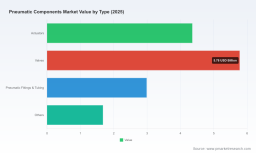
Pneumatic Components Market — Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our new Pneumatic Components Market study. Anchored on a 2025 base year and a robust forecast through 2032, this study synthesizes supply-side realities, demand dynamics, competitive positioning, and practical playbooks designed to inform capital allocation, product strategy, procurement decisions, and M&A activity in 2026.
Pneumatic Components Market
Macro trajectory you cannot ignore
The pneumatic components market has moved from a mature, industrial staple to a growth market with structural drivers that extend beyond cyclical manufacturing demand. Our topline modeling shows steady expansion from 2020 through 2025 and a continued upward trajectory across the 2026–2032 forecast window, underpinned by a multi-year compound annual growth rate of approximately 6.46%. This growth path reflects a confluence of factors: industrial automation penetration, energy-efficiency retrofits, rising medical device utilization, and tiered regional demand patterns. For executives, the headline is simple — the market is expanding at a pace that sustains returns for focused investors, while also creating pockets of disruption for incumbents and agile new entrants alike.
Pneumatic Components Market
Why this report is strategic for 2026 decisions
- Investment prioritization: Translate market momentum into highest-return R&D and capex bets with our investment-scoring framework that ranks product families by growth potential, margin resilience, and defensibility.
- Procurement and supply resilience: Identify stress points in raw-material exposure and supplier concentration; the report includes tactical levers for rapid supplier diversification and dual-sourcing pilots.
- Go-to-market and aftermarket strategies: Move beyond components to service-led models—our commercial playbook shows how to capture higher lifetime value through predictive maintenance, retrofits, and modular offering bundles.
- M&A and partnership screening: Use our transaction filter to find targets that fill technology gaps (energy-efficient actuators, intelligent valves), geographic blind spots, or aftermarket capabilities.
- Regulatory and product compliance planning: Anticipate and budget for regulatory-driven redesigns in energy and safety standards so product roadmaps remain time-to-market competitive.
What the report delivers — practical, actionable, and ready-to-use
This study is structured for executives who need both strategic context and operational tools. Highlights include:
Pneumatic Components Market
- Topline market sizing and validated forecasts (2020–2032) with scenario variants reflecting material-price shocks and regulatory tightening.
- Concentration and competitive intensity diagnostics — including market-share clustering and an analysis of three- and five-firm concentration dynamics — to help prioritize competitive responses.
- Supplier and component-level risk matrices that quantify exposure to raw material volatility, precision-machining bottlenecks, and logistics disruptions.
- Commercial and pricing playbooks: price-elasticity models, service migration pathways, and margin-capture strategies for OEMs and distributors.
- Technology and product roadmaps: assessment of electrification hybrids, modular pneumatics, intelligent valves, and the intersection with IIoT and factory automation investments.
- Ready-to-use deliverables: a dynamic spreadsheet model, an executive slide deck for board briefings, a supplier-engagement checklist, and scenario scripts for stress-testing business plans.
Competitive landscape — what market leaders are doing and why it matters
The competitive field blends long-established global players with fast-moving regional manufacturers. Leading incumbents are shifting from component suppliers toward systems and services — a move that compresses pure-play margins but expands lifetime value and stickiness with end customers.
- Festo (Germany) is doubling down on automation-integrated pneumatic solutions and energy-efficient actuators. Their product focus signals where premium segments of the market will cluster: performance plus systems integration.
- Parker Hannifin (United States) continues to leverage breadth across motion control to offer comprehensive pneumatics portfolios that appeal to industrial OEMs pursuing consolidated suppliers.
- SMC (Japan) prioritizes compact, intelligent pneumatic modules and has introduced space-saving valve solutions that simplify installation on modern automated lines.
- Bosch Rexroth and Emerson maintain strength in hydraulics-pneumatics hybrids and process-industry automation — their roadmaps indicate sustained demand for ruggedized, high-reliability components.
- Norgren, Camozzi, Airtac and multiple regional players balance cost-competitiveness with localized service footprints; their market tactics increase pricing pressure in standard-product categories but also accelerate adoption in high-volume OEMs.
- China- and Taiwan-based manufacturers are expanding technical capabilities while preserving cost advantages; expect increased competitive intensity in price-sensitive segments and faster adoption cycles in regional markets.
Recent product activity corroborates this divergence. Throughout 2025, the market saw launches of energy-efficient actuators, modular valve platforms, and corrosion-resistant tubing — trends that underline two strategic vectors: feature-led premiumization and cost-led scale. For decision-makers, the implication is clear: either compete on high-value differentiation (systems, energy optimization, digital services) or on operational scale and channel reach.
Dynamics and risks that will shape outcomes in 2026
- Raw-material volatility: Aluminum, steel, and technical plastics remain core cost drivers. Periodic price swings materially impact margins unless mitigated by hedging, long-term contracts, or design-to-cost initiatives.
- Supply-chain fragility: Precision pneumatic components rely on specialized machining and coatings. Geopolitical disruptions and logistics bottlenecks have in recent years produced measurable delivery delays — companies must assess dual-sourcing timelines and domestic production feasibility.
- Regulatory influence: Energy and machinery safety directives in major markets are pressuring suppliers to increase product efficiency and provide compliance documentation. Early engagement with standards planning converts compliance into competitive advantage.
- Material restrictions: Export controls and limitations on certain rare-earth inputs elevate lead-time risk for sealing materials and coatings; procurement and product teams must validate alternate formulations.
- Technological shift: Hybridization (electro-pneumatic systems) and intelligence layers are changing OEM requirements; incumbents who ignore systems integration risk margin erosion.
A practical 90-day plan for executives entering 2026
- Week 1–4: Rapid risk audit. Map top 10 suppliers by spend and criticality, quantify single-source exposure, and initiate contingency agreements with alternate suppliers.
- Week 5–8: Product triage. Classify SKUs into defend, optimize, divest. Fast-track product redesigns that reduce raw-material content or enable modular upgrades tied to higher-margin services.
- Week 9–12: Commercial pilots. Launch two aftermarket service offers (e.g., predictive maintenance, retrofit kits) with pilot OEMs or distributors; measure adoption and margin uplift.
- Parallel: Investor and M&A screening. Use our target-filter to identify acquisition prospects that add digital capabilities, shorten supply chains, or insert aftermarket channels.
How PW Consulting’s study reduces execution risk
We designed this report to convert uncertainty into decision-grade intelligence. It combines bottom-up manufacturing economics, primary interviews with OEMs and distributors, and a scenario-enabled forecast model so that executives can evaluate “what-if” outcomes for investment choices, procurement strategies, and competitive moves. Our concentration diagnostics and supplier-risk frameworks are intentionally operational — meant to be plugged into procurement RFPs, board-level investment memos, and R&D portfolio meetings.
To maintain confidentiality of core proprietary segment-level metrics while still demonstrating analytical depth, this preview highlights strategic direction and tactical priorities without disclosing the full granularity of regional and application splits. The complete report includes the full segmented dataset, regional-application overlays, supplier scorecards, and model spreadsheets necessary to execute the 90-day plan described above.
Next step
For access to the full Pneumatic Components Market report, including the segmented datasets, scenario models, and executable decks, visit PW Consulting’s market research page. If you would like a guided briefing tailored to your company’s footprint, contact our industry desk to schedule a strategic briefing and a hands-on modelling session.
In 2026 the winners will be those who convert the market’s steady growth into sustainable, differentiated value — through resilient supply chains, service-enabled revenue, and targeted product innovation. This report is designed to make that conversion repeatable and measurable.
For detailed analysis of this topic, please visit the official page: Pneumatic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com