

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Meter Market to Hit USD 344.8M by 2032 at 6.98% CAGR

Water Meter Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, high-fidelity lens into our forthcoming Water Meter Market study — a practical guide tailored for executive teams, product strategists, procurement leaders, and investors preparing to make consequential decisions in 2026. This preview demonstrates the analytical depth and actionable frameworks contained in the full report while intentionally withholding granular segment-level data to preserve the value of the complete research.
Water Meter Market
Why this research matters in 2026
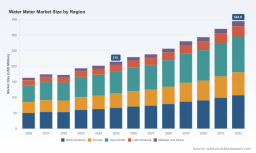
- Market trajectory: The global water meter market, measured in USD million, expanded substantially during the 2020–2025 base period and is forecast to continue a steady expansion through 2032. Our base-year anchoring (2025) and the modeled outlook to 2032 embody a compound annual growth rate (CAGR) of 6.98%, reflecting robust demand drivers across metering technologies and service models.
- Strategic inflection points: 2026 is a pivotal year — a mix of regulatory shifts, standard updates, and new product disclosures is altering procurement timelines, supplier selection criteria, and investment horizons for utilities and large industrial water users.
- Decision focus: Leaders need concise, risk-weighted intelligence to prioritize R&D, M&A, supply-chain resilience, and field-deployment pilots. Our study is built explicitly for that purpose.
High-level market picture (what the numbers imply)
From the pandemic recovery window through the present, the sector has moved from modest replacement cycles toward accelerated smart-metering and bulk-meter modernization programs. The market’s compound annual growth rate near 7% signals more than cyclical replacement spending — it underscores structural shifts: digital metering, data-driven network management, and cross-sector demand for leakage control and non-revenue water reduction. By 2032 the market is projected to be materially larger than the 2025 base, creating meaningful opportunities for established vendors, fast followers, and specialized system integrators.
Water Meter Market
Dynamics reshaping strategy
- Regulatory and procurement levers: Recent policy adjustments — including a temporary general applicability waiver for Advanced Metering Infrastructure (AMI) under a major domestic procurement statute — are compressing procurement windows and changing vendor compliance timelines. Procurement teams must redesign supplier evaluation roadmaps to reflect phased domestic content requirements and waiver transitions.
- Standards and testing: The publishing of updated industry guidance and active field-testing programs at major conferences has raised the bar for performance validation and interoperability. Utilities and buyers now demand test-evidenced performance for ultrasonic and smart metering solutions as part of contract award criteria.
- Technology modularity: Electronics, communication stacks, and sensing elements are decoupling from meter housings. This modularity creates new aftermarket opportunities (retrofit communications modules, analytics subscriptions) but also raises compatibility and lifecycle-management issues for utilities.
- Consolidation and concentration: Market concentration is moderate; the top-three and top-five vendor groups do not dominate the ecosystem to the extent seen in other infrastructure markets. This opens space for regional champions, specialized innovators, and service-driven business models.
Competitive landscape — players to watch
Our competitive analysis profiles incumbent OEMs, regional manufacturers, and cross-disciplinary entrants. Below are strategic snapshots of the core firms we examined and the recent moves that matter for 2026 strategy.
Water Meter Market
- Badger Meter (Milwaukee, Wisconsin) — A diversified provider across ultrasonic, mechanical, and AMI-compatible solutions focused on systems integration and data products. Recent Q1 2026 disclosures highlighted both steady financial performance and an inorganic acceleration into sewer monitoring through the acquisition of a sector-specific technology firm, underscoring their push to capture adjacent metering and monitoring markets.
- ZENNER International GmbH & Co. KG (Germany) — A longstanding manufacturer with capabilities spanning mechanical, ultrasonic, and smart meters. With consistent emphasis on product breadth across residential and bulk applications, Zenner’s engineering depth positions it to participate in both municipal modernization and industrial metering projects.
- Ningbo Aimei Meter Manufacturing / Ningbo Yongzhou / Wenling Younio (China-based manufacturers) — These manufacturers combine high-volume mechanical metering competence with increasing investments in electronic and IoT-enabled products. Their cost-competitiveness and manufacturing scale make them significant players in price-sensitive tender corridors and retrofit programs.
- Diehl Metering (Germany) — Focused on utility-grade solutions and bulk metering, Diehl continues to leverage trade-show platforms to showcase next-generation bulk metering products aimed at large utilities and industrial water users; their recent product exhibits at leading conferences indicate continued emphasis on accuracy, serviceability, and system-level value propositions.
Taken together, vendor strategy choices fall into a few repeatable archetypes: integrated platform builders (hardware + software + services), manufacturing-focused players enabling low-cost volume deployments, and niche specialists delivering high-accuracy or bulk-meter solutions. The competitive field is dynamic: product announcements and targeted acquisitions in early 2026 highlight a race to expand functional footprints beyond pure device sales.
Operational and go-to-market implications
- Procurement strategy refinement: Implement staged RFPs that explicitly accommodate waiver-driven purchasing timelines and phased domestic-content milestones; include modular acceptance criteria for retrofit or hybrid AMI rollouts.
- R&D and product roadmaps: Prioritize modular electronic platforms, OTA (over-the-air) upgradability, and API-first data architectures to enable interoperability with utility analytics platforms and third-party service providers.
- Service & subscription models: Monetize analytics and leakage-detection services alongside hardware sales. A blended revenue model reduces dependency on replacement cycles and increases lifetime customer value.
- M&A and partnerships: Look for tuck-in acquisitions that add sewer and network-sensing competencies, or partner with communications specialists to de-risk connectivity and ongoing firmware maintenance obligations.
What the full PW Consulting report delivers (practical, executable content)
Our complete study is structured to move leadership from insight to action. Highlights of the deliverables include:
- Executive decision frameworks: capital allocation templates, investment prioritization matrices, and ROI breakeven models tailored to metering upgrades and AMI/AMI-adjacent investments.
- Procurement playbook: sample RFx language, compliance checklists addressing domestic-content phase-ins, acceptance-test protocols that map to updated standards, and vendor scorecards for risk-weighted selection.
- Technology adoption maps: maturity curves for ultrasonic, electromagnetic, ultrasonic bulk meters, volumetric technologies, and retrofit communication modules, plus recommended pilot designs by use case.
- Competitive battle cards: strategic profiles, capability comparisons, and scenario-based win-loss hypotheses for the principal suppliers and regional challengers.
- Supply chain risk register: component sourcing heatmaps, single-source exposures, and mitigation playbooks that include dual-sourcing and consignment strategies for critical electronic components.
- Go-to-market blueprints: channel segmentation, pricing strategy experiments, and service-bundling options for city-scale deployments, private utilities, and industrial clients.
- Granular appendices: primary interview synopses, methodology notes, and data tables that drill into unit shipments, ASP trends, and installed-base replacement cycles — accessible in the full report to subscribers.
How to use this intelligence in 2026 (three priority actions)
- Align procurement with policy timing: If your projects are tied to public funding or are subject to domestic-content rules, modify contract clauses and supplier milestones now to avoid rework when waiver transitions end.
- Shift product bets toward modularity: Invest in field-upgradable electronics and open data platforms to reduce churn and capture long-term service revenues. Proof-of-concept deployments that validate interoperability will open procurement pathways.
- Execute targeted inorganic growth: Pursue bolt-ons that add sensing capabilities (e.g., sewer monitoring, pressure/flow analytics) or expand analytics capabilities, improving stickiness with utility customers and enabling premium service tiers.
Why executives should trust this preview
PW Consulting’s assessment synthesizes primary utility interviews, vendor financial disclosures, trade-show validation, standards-track developments, and a proprietary forecasting engine. We triangulate shipment trends with price realization models and account for regulatory permutations — including the recent AMI waiver and updated industry manuals — to produce scenario-ready guidance for 2026 decision-making.
Next steps — where to get the full intelligence
This preview intentionally surfaces the strategic contours and executive playbooks while withholding the underlying granular segmentation and proprietary tables that drive procurement and product decisions. The full report contains the detailed, validated datasets, regional deployment models, and downloadable templates you need to operationalize the recommendations outlined above. Access the complete Water Meter Market study on our website to obtain the appendices, vendor scorecards, and the full suite of decision-support tools.
For prioritized briefings or to commission a bespoke workshop that maps these insights to your organization’s specific portfolio, contact our PW Consulting Water Meter market practice. Our goal is to convert foresight into action — rapidly, defensibly, and with measurable outcomes.
For detailed analysis of this topic, please visit the official page: Water Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com