

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
Electric Bike Market to Reach USD 147.22B by 2032, 10.54% CAGR: PW Consulting
By pmarketresearch, 2026-07-09
Electric Bike Market 2026: Strategic Imperatives from a Rapidly Scaling Industry
As decision-makers prepare budgets, partnerships, and product roadmaps for 2026, the Electric Bike (e‑bike) ecosystem presents a rare intersection of rapid consumer adoption, technological maturation, and shifting regulatory contours. PW Consulting’s latest industry study — anchored on a 2025 base year and projecting through 2032 — shows the market more than doubling from early‑decade levels and sustaining a compound annual growth rate (CAGR) of 10.54% over the forecast horizon. That trajectory creates both tangible upside and operational complexity for OEMs, component suppliers, fleet operators, and institutional buyers. This introductory brief distills the strategic takeaways executives must act on in 2026, while preserving the report’s proprietary, segment‑level detail for subscribers who require the full dataset and scenario models.
Electric Bike Market
Market Snapshot: Momentum and Scale
Between 2020 and 2025 the market expanded briskly, and our 2026 baseline confirms an inflection from niche adoption to mainstream mobility. The projected path through 2032 points to an industry that will be materially larger than today’s baseline, reflecting a convergence of urbanization trends, last‑mile logistics demand, and consumer willingness to trade car trips for e‑assisted cycling. For strategists, the headline metrics matter: the market’s mid‑teens growth profile over the forecast window is not driven by a single catalyst but by the cumulative effect of product diversification, falling unit manufacturing costs in many tiers, and increased institutional purchasing in new use cases such as cargo logistics and shared mobility.
Electric Bike Market
What This Research Delivers — Practical, Decision‑Oriented Outputs
- Quantified market sizing and top‑line forecasts at the global level with scenario sensitivity to commodity shocks, tariff moves, and regulatory shifts.
- Actionable go‑to‑market playbooks segmented by business model (D2C, channel partner, fleet), product archetype (folding, cargo, eMTB, commuter), and aftersales service models.
- Supply‑chain stress maps that prioritize vulnerability points (cells, BMS, controllers, hubs) and suggested mitigation pathways including dual‑sourcing, contractual hedging, and localized assembly levers.
- Commercial benchmarking and pricing ladders for entry, mid, and premium tiers — enabling margin modeling and SKU rationalization exercises.
- A competition database with strategic profiles, capability matrices, and recent product and market moves for leading players across geographies.
- Regulatory and standards playbook with compliance timelines and cost‑impact estimates for new battery and safety rules across key jurisdictions.
The study is deliberately designed to be executable: each chapter concludes with prioritized actions and one‑page executive checklists so leaders can translate insight into 90‑day and 18‑month plans.
Electric Bike Market
Why 2026 Is a Pivotal Year for Strategic Positioning
- From experimentation to scale: Market data indicate that e‑bikes are moving beyond early adopters into broader segments including utility and institutional fleets. This transition changes the economics of product reliability, service networks, and financing.
- Regulatory harmonization and fragmentation are simultaneous forces. New safety and battery standards reduce ambiguity in some markets while introducing compliance cost spikes elsewhere — a dynamic that favors firms with robust engineering and regulatory affairs capabilities.
- Supply‑side volatility: commodity price swings and tariff recalibrations in late 2025 and early 2026 materially affect component cost trajectories. Firms that locked minimum purchase commitments or adopted flexible manufacturing postures are already showing relative margin resilience.
Competitive Landscape — Who Controls the Narrative
The industry today is best described as moderately concentrated: leading incumbents command meaningful commercial scale, but the market remains accessible to focused challengers that can innovate on product, channel, or service economics. Our research profiles key participants across the value chain and assesses their strategic postures.
- Aventon (United States) — Strong in mid‑range and premium urban and adventure models, Aventon’s proprietary control unit and embedded connectivity position it well for value‑added services (fleet telematics, OTA updates). Their recent SKU introductions underscore a play for lifestyle and geographic expansion.
- Rad Power Bikes (United States) — Rad’s broad portfolio and emphasis on torque and range reinforce its position in commuting and utility segments. Their scale and direct‑to‑consumer channel economics remain a core advantage for growth in North America and beyond.
- Lectric E-Bikes (United States) — Competing on affordability, folding convenience, and compliance‑tested electrical systems, Lectric’s model is a case study in cost‑efficient urban penetration where entry price is the primary adoption barrier.
- Velotric (United States) — Velotric’s focus on performance and ergonomics for older adults and recreational riders creates a defensible niche that combines step‑through design with range optimization.
- Riese & Müller and Haibike (Germany) — These premium European players leverage deep integration with established powertrain partners and battery architecture expertise to capture high‑margin eMTB and cargo demand.
- Trek and Giant — Global incumbents with distribution breadth and manufacturing scale; their hybrid strategies (retail network, co‑branded tech integrations) make them formidable in performance and commuter categories.
- Eovolt (Netherlands) — Compact, design‑led folding e‑bikes for last‑mile urban mobility — a reminder that product form factor remains a potent differentiation axis.
Collectively, the competitive set reveals divergent strategic plays: scale plus channel strength, product‑led premiumization, and cost leadership in urban micro‑mobility. Our report includes relative capability maps, partnership fit assessments, and M&A themes that buyers and investors should watch in 2026.
Regulation, Commodities, and the New Operational Risk Map
Three contemporaneous dynamics are shaping near‑term risk and opportunity:
- Standards and safety updates: Regulatory bodies have accelerated battery and electrical safety standards. Firms selling into large regional markets must embed compliance into product development cycles to avoid market access disruptions.
- Tariffs and trade policy: Recent tariff adjustments have reweighted the incentives for localization versus import. The calculus for where to locate final assembly now depends on a more complex interplay of labor cost, lead time, and trade exposure.
- Raw material volatility: Sharp moves in lithium input costs in late 2025 and early 2026 have widened the margin variance between vertically integrated players and those reliant on spot component procurement.
For executives, this means rethinking sourcing strategies (long‑term offtake vs. spot buying), accelerating battery recycling and second‑life programs, and building certification roadmaps into new product development timelines.
Strategic Recommendations for 2026 Planning
- Prioritize modular architectures. Design with interchangeable battery and electronics modules to shorten certification cycles and reduce obsolescence risk, enabling faster market entry as standards evolve.
- Adopt a risk‑weighted sourcing playbook. Create tiered supplier relationships: core contracts for critical components, tactical partners for scale, and vetted single‑source contingency suppliers for rare parts.
- Monetize connectivity. Connectivity is no longer a “nice‑to‑have.” Build subscription services for fleet management, preventative maintenance, and telemetry to diversify revenue beyond unit sales.
- Segment go‑to‑market by use case. Urban commuters, cargo fleets, and recreational riders have divergent service expectations and lifecycle economics. Customize warranty, financing, and service offerings accordingly.
- Embed regulatory foresight. Allocate resources to standards engagement and pre‑certification testing; early compliance planning reduces time‑to‑market and prevents costly redesigns.
Report Access and Next Steps
PW Consulting’s full Electric Bike Market study includes the granular segment breakdowns, region‑by‑region forecasts, SKU‑level cost and margin matrices, and a searchable competitive intelligence database. The public summary here is intended to equip senior leaders with the strategic framing and near‑term imperatives required for 2026 planning. For teams that need the hard numbers — segmentation revenue by type, application, and region, scenario tables with sensitivity to tariff and commodity shifts, and executable playbooks tailored to specific business models — the full report provides those datasets alongside implementation templates.
In a market expanding at a double‑digit CAGR and facing rapid regulatory and supply surprises, the organizations that pair disciplined scenario planning with operational flexibility will capture disproportionate value. PW Consulting’s study is designed to be the playbook for exactly that shift: convert market momentum into durable advantage without exposing your organization to unnecessary compliance or supply risk.
How PW Consulting Can Help
- Custom strategy workshops aligned to your 2026 P&L and product roadmap.
- Tailored supply‑chain stress tests and hedging strategies.
- Partnership and M&A target screening using our proprietary scoring model.
Contact PW Consulting to request the complete Electric Bike Market report and to schedule a briefing with our senior analysts. The headline growth story is clear — the differential will be set by execution. Our work turns that execution into an evidence‑backed, risk‑calibrated plan.
For detailed analysis of this topic, please visit the official page: Electric Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Battery Market 2026–2032 — 3.82% CAGR Fuels Electric Mobility
By pmarketresearch, 2026-07-09
Electric Vehicles Battery Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As the automotive industry accelerates its transition to electrified mobility, the electric vehicle (EV) battery market is entering a phase defined by incremental growth, concentrated supply power, and disruptive technology inflection points. Our base-year analysis (2025) places the global EV battery market at approximately USD 77.0 billion, following a steady climb from the early 2020s. Under our central forecast, the market expands at a compound annual growth rate (CAGR) of roughly 3.8% through the 2026–2032 horizon, crossing the USD 100 billion threshold before the end of the forecast window. These headline figures mask meaningful differentiation beneath the surface — shifts in chemistry, manufacturing location strategy, feedstock volatility, and regulatory constraints that will determine winners and losers in 2026 and beyond.
Electric Vehicles Battery Market
Why 2026 is a pivotal year
-
Transition from volume-led to value-led competition: With headline market growth moderating versus the high-double-digit expansion of earlier years, 2026 will separate companies that compete on cost and scale from those capturing value through differentiated chemistries, fast-charge capability, safety, and integrated systems approaches.
Electric Vehicles Battery Market -
Regulatory and trade regimes are reshaping supply chains: Recent policy moves have created new sourcing and localization imperatives. Procurement teams and investors must evaluate compliance, tariff exposure, and the operational cost of localization when sizing facilities and negotiating offtake agreements.
Electric Vehicles Battery Market -
Material and technology inflection points converge: Surges in key commodity prices alongside rapid commercial rollouts of alternative chemistries force OEMs and suppliers to reassess technology roadmaps and risk exposures in 2026.
Market trajectory and what the headline numbers mean
Viewed as a whole, the EV battery market is continuing to expand but at a pace that rewards operational excellence, strategic positioning, and portfolio flexibility. The market’s progression from the low-60s billion USD level in the early 2020s to roughly USD 77 billion in 2025 — and onward toward a seven-figure growth milestone by the early 2030s — reflects a maturing industry where unit cost reductions, technology substitution, and aftermarket business models matter as much as unit volume.
For corporate strategists this implies three immediate tactical considerations: 1) prioritize investments that improve cost-per-kilowatt-hour on commercially relevant chemistries; 2) model scenarios where commodity spikes and export controls compress margins; and 3) set clear criteria for factory location and partnership choices that internalize regulatory and tariff risk.
Competitive landscape — concentrated and contested
The EV battery landscape in 2026 remains relatively concentrated among a handful of large, vertically integrated suppliers, with the top three players commanding a substantial share of market supply and the top five commanding a clear majority. This structure produces tight negotiation dynamics with OEMs, privileged access to large-scale capacity, and the ability for front-runners to subsidize R&D at scale.
Leading suppliers demonstrate complementary strategic approaches that define current best practices and emergent threats:
-
CATL (Ningde, China): Global market leadership driven by breadth of chemistry offerings — including LFP, NCM, and advanced formulations — coupled with rapid commercialization of sodium-ion and condensed cell formats targeted at range and fast-charge performance. CATL’s move into sodium-ion mass production and its latest Qilin and fast-charge products underscore a playbook that mixes scale, product differentiation, and aggressive commercialization timelines.
-
BYD (Shenzhen, China): Integrates proprietary cell and pack technologies with captive vehicle demand. Its Blade Battery narrative emphasizes safety and charging characteristics and provides a vertically coordinated advantage for both captive fleet deployment and third-party supply opportunities.
-
LG Energy Solution (Seoul, South Korea): Leverages large-scale cylindrical and pouch production with geographic diversification, notably expanded manufacturing in North America. LGES balances long-term OEM contracts with strategic capacity retooling to reflect shifting chemistry demand.
-
Panasonic Energy (Osaka, Japan): Continues to anchor cylindrical-cell leadership with multi-format programs for North American and global OEMs. Panasonic’s deep OEM partnerships and cell-format expertise make it a critical supplier in product architectures optimized around cylindrical formats.
-
SK On and Samsung SDI (Seoul, South Korea): Both firms combine chemistry R&D with regional expansion. Recent multi-year supply agreements from Samsung SDI highlight continued demand for high-performance cells for premium OEM programs.
-
EVE Energy and Northvolt: Represent targeted regional plays — one anchored in domestic prismatic technologies and the other emphasizing clean-energy production and European supply sovereignty — both attractive to OEMs pursuing differentiated sustainability and localization narratives.
Dynamics shaping 2026 decision-making
-
Regulatory tailwinds and headwinds: Policy changes in 2025–2026 have materially affected procurement strategies. For example, trade measures and sourcing conditions in major markets have altered the economics of imported cells and encouraged a reassessment of onshore capacity. Companies must model not just tariff rates but also the administrative and compliance costs associated with evolving incentive programs.
-
Material price volatility: The industry experienced marked swings in critical feedstocks. Cobalt supply constraints and policy actions in key producer nations led to sharp price movements, while lithium markets rebounded significantly in early 2026 compared to 2025 levels. These dynamics increase the value of supply agreements, downstream integration options, and alternative chemistry adoption.
-
Chemistry substitution and manufacturing reallocation: Large-scale retooling toward different chemistries — including reallocations toward LFP in 2025 — demonstrates that manufacturing footprints are now more plastic. Sodium-ion moving into mass production further expands the technology toolkit available to OEMs and fleets seeking cost-performance trade-offs.
-
Technology performance vectors: Range per charge, charge speed, safety characteristics, lifecycle degradation, and total cost of ownership remain the dominant decision criteria for OEMs and fleet operators. Recent product launches underscore a premium on fast-charge and condensed energy-density solutions.
Practical content included in our full report
The comprehensive PW Consulting market study is designed for executives who need to translate macro trends into executable 2026 plans. Key deliverables include:
-
Robust market sizing and scenario forecasts, with transparent methodology and sensitivity testing to alternative demand, commodity, and policy assumptions.
-
Supply-chain heatmaps and bottleneck risk scoring that identify critical nodes and contingency options.
-
Technology roadmaps and deployment timelines for incumbent and emergent chemistries, including commercialization timelines and cost curves.
-
Competitive intelligence dossiers for tier-1 suppliers — coverage includes commercial strategies, capacity expansion roadmaps, partnership matrices, and likely responses to OEM sourcing shifts.
-
Commercial playbooks for OEMs and investors: negotiation checklists, contract structures, offtake calibration tools, and go-to-market templates for captive vs. third-party supply strategies.
-
M&A and JV decision frameworks that prioritize value creation levers under different regulatory and commodity scenarios.
Recommended strategic actions for 2026
-
Lock flexible capacity and secure feedstock optionality: Structure offtake and supply agreements to preserve flexibility across chemistry formats and geographic sources; where possible, negotiate clauses that hedge against extreme commodity swings.
-
Prioritize modular investment in manufacturing: Favor modular, reconfigurable lines that enable chemistry switches without multi-year production gaps.
-
Build regulatory playbooks: Invest in capabilities to rapidly assess incentive eligibility, tariff exposure, and localization requirements; prioritize markets where policy alignment yields outsized total-cost advantages.
-
Differentiate through system-level integration: Suppliers and some OEMs will capture premium value by integrating thermal management, cell-to-pack designs, and differentiated warranties rather than competing solely on cell cost.
-
Stress-test partnerships and M&A with scenario-driven valuation: Use scenario P&L stress tests that incorporate raw material shocks and regulatory permutations — transact where synergies are resilient across these regimes.
Implications for corporate planners and investors
2026 will not be a year for passive portfolio allocations. The combination of moderate headline growth, concentrated supplier power, and disruptive material and chemistry shifts elevates the returns to active strategic management. Boards should expect procurement teams to present multi-scenario sourcing plans, CFOs to demand commodity-hedging strategies, and business development teams to prioritize partnerships that reduce execution risk.
For investors, the concentration metrics in the sector point to asymmetric opportunity: a small number of integrated suppliers will likely preserve margin and market access, while nimble challengers can win share regionally by aligning with local OEMs and sustainability narratives. The winners will be those who couple capital discipline with a clear play for pricing power, differentiation, or structural cost advantage.
Next steps — where to find the full intelligence
This article is a strategic preview intended to communicate the practical value of full, proprietary analysis contained in our Electric Vehicles Battery Market report. The complete study includes granular sensitivity models, a downloadable dataset, and a full competitive matrix that expands on the supplier dossiers summarized here. For procurement leaders, R&D heads, and C-suite decision-makers planning 2026 capital and commercial moves, the full report provides the actionable depth necessary to convert uncertainty into advantage.
Contact PW Consulting or visit our report page to access the full dataset and scenario-builders, and to schedule a bespoke briefing tailored to your portfolio and operational footprint.
For detailed analysis of this topic, please visit the official page: Electric Vehicles Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Road Bikes Market to Reach USD 5.49 Billion by 2032 at 4.85% CAGR — PW Consulting
By pmarketresearch, 2026-07-08
Road Bikes Market 2026: Strategic Preview for Executive Decision‑Makers
As PW Consulting’s senior strategy team, we prepared this market preview to orient executive decisions in 2026. The global road bikes market is returning to a steady, structurally supported growth path: a market that expanded from roughly USD 3.1 billion in 2020 to about USD 3.85 billion in 2025 and is projected to continue rising into the next decade, reaching roughly USD 5.5 billion by 2032 under a mid‑range scenario. Our forecast framework expects a compound annual growth rate of approximately 4.85% through the 2026–2032 period. These headline numbers anchor the tactical and strategic guidance below — but the value for executives is less in the topline and more in the scenarios, risk ladders, and levers that convert that growth into profitable market share.
Road Bikes Market
Why this research matters for 2026 decisions
- Risk‑informed capital allocation: quantify how regulatory actions and raw‑material volatility change the returns on new product investments, plant expansions, and inventory commitments.
- Portfolio prioritization: identify where to concentrate R&D and channel investments between performance, endurance, and volume segments so 2026 product cycles align with demand momentum.
- Supply‑chain resilience: model procurement strategies (hedging, near‑sourcing, supplier consolidation) that protect margins against material price shocks and tariff exposures.
- M&A and partnerships: highlight acquisition targets and co‑development partners whose capabilities accelerate time‑to‑market on high‑value innovations without absorbing fixed cost risk.
- Pricing and channel optimization: translate the macro trend into price elasticity maps and dealer vs direct‑to‑consumer (D2C) scenarios that preserve ASPs while expanding reach.
What the full report delivers (practical, operational content)
- Validated market sizing and forward curves (2020–2032) with transparent assumptions and sensitivity bounds that management teams can plug into their financial models.
- Scenario playbooks that quantify the P&L and balance‑sheet impact of four plausible 2026 shocks — tariff imposition, a sustained raw material price surge, an acceleration in e‑bike substitution, and tightening UCI equipment rules.
- Supply‑chain stress tests: supplier concentration heatmaps, critical‑path lead‑time simulations, and recommended mitigation steps (dual sourcing, pre‑purchases, and regional buffering).
- Competitive diagnostic for the top global brands with capability maps, relative cost positions, and go‑to‑market strengths and weaknesses tailored to premium, mid, and entry tiers.
- Product roadmaps and R&D priorities tied to measured performance returns (e.g., system vs frame gains), regulatory compliance checklists, and testing protocols for 2026 rule changes.
- Commercial playbooks: channel split optimization, promotional cadence recommendations, and customer retention strategies for urban commuters, recreational riders, and competitive racers.
- M&A & partnership scoring model: a repeatable framework to rank targets by strategic fit, integration complexity, and near‑term cash conversion potential.
Macro dynamics shaping 2026 strategy
The industry is navigating a convergence of regulatory, cost, and product‑design forces that materially affect 2026 decisions:
Road Bikes Market
- Trade and tariff risk: stakeholders should plan for policy volatility. In late 2025 the US Department of Commerce opened comments on proposals that would dramatically raise tariffs tied to metal content. Even without a definitive outcome, the mere prospect compresses margins for manufacturers with exposed metal‑intensive supply chains and raises the value of local assembly or non‑metal innovation strategies.
- Regulatory design rules: UCI’s 2026 fork internal width limits require rapid design adaptations for race‑oriented platforms. This has cascading implications for wheel‑tire systems, integration strategies, and sponsor value propositions for pro team partnerships.
- Input cost pressure: steel, aluminum, and carbon fiber experienced multi‑year price escalations through 2025. Companies that rely on single‑source, high‑volume buys or that operate on thin margin models are particularly vulnerable.
- Channel and product blurring: discussions around e‑motor regulation and the misclassification risks of high‑powered e‑motorcycles could reshape how distributors, insurers, and regulators treat powered two‑wheelers, indirectly influencing dealer footprint economics and consumer purchasing behavior.
Competitive landscape — position, momentum, and tactical levers
Concentration in the road bikes market is meaningful but not prohibitive: the top three vendors control a large minority of global revenue, and the top five approach a clear majority, creating both competitive pressure and opportunity for informed challengers. Competitors fall into three strategic archetypes: technology leaders, system integrators with scale, and niche specialists. Understanding where a company sits on that map determines which levers will most improve relative performance.
Road Bikes Market
- Specialized (Morgan Hill, CA) — Technology and brand cachet in both aluminum and carbon. Their broad portfolio from entry to pro race gives them channel reach; maintain advantage through incremental material and cockpit integration innovations.
- Trek (Waterloo, WI) — Strength in aerodynamic and endurance platforms. Trek’s investment strategy should prioritize system‑level aero gains and service bundles to protect premium pricing.
- Cannondale (Bethel, CT) — Known for ride feel and aluminum performance models. Opportunities exist in modular upgrades and premiumizing aluminium lines without eroding core value propositions.
- Giant (Taichung, Taiwan) — Scale and recent product updates (notably an 18‑watt efficiency gain on the Propel through cockpit, wheel, and tire refinements) make Giant a bellwether for system engineering returns versus marginal cost.
- Cervélo, Pinarello, Factor, BMC, Canyon, Scott, Bianchi — These brands represent a mix of aero specialists, direct‑to‑consumer disruptors, and heritage craft makers. Tactical differentiation ranges from carbon material science to distribution models and racing partnerships.
Recent developments underscore strategic vectors for 2026: Giant’s March 2026 Propel update demonstrates the commercial value of system optimization; Canyon’s D2C refreshes tighten price/performance competition; Bianchi’s supply deal with a WorldTour team reinforces the marketing and R&D payoff from pro association; and smaller innovators (e.g., OPEN) indicate fertile ground in gravel and adjacent segments.
Strategic playbook for management teams in 2026
- Move from commodity sourcing to supplier partnership models: secure fixed‑volume options for carbon and critical metal inputs, and pursue joint development agreements to share R&D costs for new layup and integration concepts.
- Invest in system engineering over isolated component gains: measured system‑level watt reductions (cockpit, wheels, tires) can deliver outsized competitive advantages at lower certification and tooling cost than full new‑frame programs.
- Hedge regulatory exposure with product tiering: maintain race‑compliant platforms for pro channels while offering adaptable endurance and urban models that reduce dependence on contested tariff lines or specific material mixes.
- Pursue selective vertical integration and near‑shoring where economics justify — particularly assembly and final finishing — to mitigate tariff risk and improve lead‑time responsiveness to product launches.
- Accelerate margin capture via service and software: performance analytics, personalized fit services, and subscription wheels/maintenance can reduce cyclicality and improve customer lifetime value.
- Use targeted sponsorship and pro team alignment to validate new designs and accelerate market acceptance, but price those investments by measured return metrics tied to sales lift, not solely to brand prestige.
- Calibrate M&A to acquire capability not just volume: look for composite‑layup expertise, proprietary cockpit/wheel systems, or D2C logistics assets that shorten time‑to‑scale for high‑margin offerings.
How PW Consulting’s Road Bikes Market report accelerates action
This study is designed as an executable toolkit for 2026. Beyond the headline forecast and market map, the full report contains executable decision support: configurable financial models, supplier risk matrices, a prioritized R&D investment matrix, and an M&A scorecard populated with targets and valuation ranges. We intentionally keep detailed region‑ and application‑level splits behind the report paywall in order to preserve the actionable competitive granularity clients rely on for bidding, sourcing, and investment decisions.
For leadership teams, the most immediate takeaway is that steady topline growth masks a materially different competitive and regulatory terrain in 2026 than in 2020–2021. Companies that rewire procurement, sharpen system engineering, and align commercial models to service and software will capture disproportionate value as the market evolves. PW Consulting’s full report provides the granular segment tables, supplier lists, and company‑level diagnostics necessary to convert this strategic preview into an operational transformation plan.
Reach out to PW Consulting to obtain the full Road Bikes Market report and the accompanying decision‑support workbook to map the implications to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Road Bikes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Connectors Market USD 7.0B in 2025, to USD 11.17B by 2032 (6.97% CAGR)
By pmarketresearch, 2026-07-08
Automotive Connectors Market: Strategic Imperatives for 2026 — A PW Consulting Preview
The automotive connectors market stands at a strategic inflection point. After a steady recovery through the early 2020s, total industry revenue expanded from USD 4.98 Billion in 2020 to USD 7.00 Billion in our base year of 2025. Our outlook projects continued momentum across 2026–2032, with the market reaching approximately USD 11.17 Billion by 2032 at a compound annual growth rate (CAGR) of 6.97% (USD, revenue unit: Billion). For leaders planning 2026 strategies, this report synthesizes where value will be created, who is positioned to capture it, and which near-term decisions will most materially affect competitive positioning.
Automotive Connectors Market
Why this research matters for 2026 decision cycles
2026 is the first full planning year after several structural shifts converged: accelerated EV adoption, tightening standards for high-voltage charging, rapid embedding of domain controllers and automotive Ethernet, and concentrated supply risks for key raw materials. The 2026 budget and capital allocation decisions you make now will determine product roadmaps, supplier relationships, and M&A appetite through the next business cycle. Our Automotive Connectors Market study translates macro growth into operationally relevant choices—where to allocate R&D, how to configure manufacturing footprints, and which partnerships will produce defensible margins.
Automotive Connectors Market
Core findings you can act on
- Growth trajectory and investment window: With the market expanding at ~6.97% CAGR over the forecast horizon, there is sustained room for investment in higher-value connectors (high-voltage, high-speed data, ruggedized interconnects) and integrated harness systems. This growth is not uniform; it is driven by technology and regulatory catalysts rather than uniform vehicle volume expansion.
- Market structure and concentration: The market exhibits moderate concentration: the top three players control a clear majority of industry revenue while the top five widen that dominance further. This dynamic favors scale players for high-volume, capital-intensive segments, but specialist suppliers and regionally focused companies retain pockets of technical differentiation.
- Standards and regulatory inflection points: The publication of SAE J3400/2 and related adapter guidance, along with technical guidance such as the ZVEI validation guideline for low-voltage connectors, are reshaping product specifications and qualification cycles. Compliance and standards engagement have become competitive levers rather than mere risk controls.
- Supply chain and materials risk: High dependence on limited-source plastic resins and precious metals elevates geopolitical and licensing risk. Contract strategies for 2026 must blend long-term supplier commitments with diversified secondary sources and hedging where feasible.
What the report contains — practical, operational insight
This study is designed for decision-makers who need more than forecasts: it is a playbook for execution. Key deliverables include:
Automotive Connectors Market
- Detailed market sizing and trend analysis (historical 2020–2025; base year 2025; forecast 2026–2032).
- Technology and product roadmaps identifying where technical differentiation (e.g., high-voltage eHV systems, 25A+ power connectors, automotive Ethernet, fiber/RF solutions) will produce margin uplift.
- Commercial playbooks: pricing levers, channel strategies for OE vs. aftermarket, and go-to-market frameworks for tiered supplier models.
- Supply chain risk matrix and mitigation options, including dual-sourcing playbooks, nearshoring scenarios, and inventory strategies tied to materials risk profiles.
- Competitive benchmarking with vendor scorecards (technology, manufacturing footprint, program wins, ADAS/EV alignment) and a prioritized M&A target list based on capability gaps.
- Regulatory and standards tracker with scenario-based impacts on product lifecycles and certification costs.
- Case studies that map design-to-manufacture timelines and cost-to-serve analytics for representative product families.
- Decision-ready dashboards and scenario models to stress-test capital investments, shift in vehicle architectures, and supplier consolidation outcomes.
Competitive landscape — who matters and why
The market combines global systems integrators and specialized regional manufacturers. Large, diversified players command program access and scale advantages; niche players and component specialists provide innovation in electrical contacts, compact high-density connectors, and application-specific certifications.
- TE Connectivity (Schaffhausen): A scale leader with a broad portfolio across low-voltage signal and power connectivity. TE’s public disclosures also highlight exposure to concentrated raw material supply chains—an element buyers and procurement teams must internalize when negotiating long-term programs.
- Amphenol Corporation (Wallingford, CT): Known for ruggedized interconnects and systems for EVs and sensors; strong in environmental and mechanical protection features valued in off-highway and commercial vehicle segments.
- Molex (Koch Industries, Lisle, IL): A primary player in eHV high-voltage systems; its high-current distribution solutions are central to EV platform engineering and auxiliary power management.
- JAE Electronics (Tokyo): Specialist in compact, high-density connectors and emerging high-power/up-to-25A solutions. Recent product launches underscore a push into automotive Ethernet and high-power segments — watch for program qualification wins in 2026 procurement cycles.
- Hirose Electric, Sumitomo Electric, Yazaki: These firms combine product breadth with close OEM relationships in key vehicle markets; they accelerate time-to-vehicle integration for infotainment, wiring harness, and high-voltage subsystems.
- Regional and niche suppliers (e.g., KSTerminals, Greenconn, Sunkye, Rosenberger): Offer specialization in aftermarket, IATF-certified manufacturing, MIL-spec variants, and RF/high-speed communications — essential partners when OEMs require tailored or localized solutions.
- Aptiv: Integrates connectors into broader wiring and electronic architecture platforms, creating higher-value systems solutions that move the value chain upstream.
Recent developments shaping 2026 strategies
- SAE’s publication of J3400/2 (May 2025) and related adapter guidance shifts the technical bar for charging hardware, enabling designs that support higher voltage and faster charge rates. This creates new product qualification requirements and a window for suppliers able to accelerate certification timelines.
- CharIN and SAE alignment on adapter standards reduces interoperability friction but increases the cost and complexity of compliance — suppliers must be prepared for longer validation cycles and upgraded testing suites.
- Product launches from leading connector suppliers — including high-power 25A-class connectors and 1000BASE-T1-capable Ethernet products — signal OEM demand moving from discrete components to integrated, software-aware interconnect solutions.
- Regulatory and procurement actions, such as DOT inquiries into connector performance and national-level trade dynamics, will affect supplier selection and contract structuring for North American programs in 2026.
Strategic implications and recommended actions for 2026
Translate market growth and technical developments into a defensible plan with the following priority moves:
- Prioritize standards-aligned R&D: Allocate a portion of R&D to ensure product families meet J3400-class and automotive Ethernet requirements. Early engagement with standards bodies and conformance testing labs reduces time-to-program approval.
- Build supply resilience: Implement dual-sourcing for critical resins and contact metals, pursue strategic inventory agreements, and qualify geographically diverse secondary suppliers to mitigate geopolitical exposures highlighted by major incumbents’ disclosures.
- Targeted M&A and partnerships: Acquire or partner with firms that add high-voltage capability, in-cabin high-density connectors, or automotive Ethernet expertise to rapidly fill portfolio gaps without long internal development cycles.
- Commercial differentiation: Move beyond price competition; offer systems-level warranties, integrated harness solutions, and digital product passports that shorten OEM validation timelines and capture aftermarket value.
- Operational footprint optimization: Reassess manufacturing placement to balance proximity to OEMs with risk diversification. Nearshoring or regional assembly hubs can be decisive for 2026 program wins.
- Engage in standards and ecosystem coalitions: Participate in SAE, CharIN, and regional bodies to help shape implementation specifics — being in the room influences technical choices and early adopter advantages.
How PW Consulting supports 2026 execution
Our Automotive Connectors Market study combines quantitative forecasts with decision-ready deliverables: vendor scorecards, program qualification timelines, supplier risk heatmaps, and an M&A screening engine calibrated to capture synergies in power and data connector domains. We also provide a regulatory impact simulator that models certification cost, time-to-market delta, and expected margin pressure under alternative compliance scenarios.
For teams preparing procurement plans, product roadmaps, or M&A pipelines for 2026, the research provides the evidence base and playbooks needed to move from analysis to action while preserving upside in a market expected to expand materially through 2032.
Next steps
This preview highlights strategic themes and operational levers. The full PW Consulting report contains the granular segmentation, regional and application breakdowns, modelled scenarios, and vendor-level financial and technical benchmarking that underpin procurement decisions and R&D prioritization for 2026. To access the complete dataset, detailed segment-level forecasts, and the executable playbooks, please refer to our full report.
For detailed analysis of this topic, please visit the official page: Automotive Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sound Level Meters Market — USD 1.3B in 2025; 5.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-08
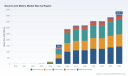
Sound Level Meters Market — Strategic Outlook for 2026 Decisions (PW Consulting)
As regulatory scrutiny, workplace health programs, and environmental monitoring priorities intensify worldwide, the market for sound level meters is moving from a niche instrumentation category into a strategic asset class for instrumentation vendors, occupational health teams, and infrastructure operators. PW Consulting’s latest Sound Level Meters Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical dynamics and a multi-scenario forecast built on a 5.85% compound annual growth rate (CAGR). All monetary figures in this briefing are reported in USD Million. The research is structured to arm executives and investment committees with the precise intelligence they need to make decisive moves in 2026 — while preserving the proprietary, drill‑down datasets that make the full report actionable.
Sound Level Meters Market
Why this research matters for 2026 strategic choices
-
Regulatory alignment is now a board-level issue. Sound level meters are no longer purely technical purchases for EHS teams — they are compliance tools shaped by standards such as IEC 61672-1 and ANSI/ASA S1.4 and referenced by authorities including OSHA and NIOSH. Our study maps how standards timing and reaffirmations will affect capital and operating expenditures across buyer groups in 2026.
Sound Level Meters Market -
Procurement timing and product segmentation decisions will determine margin capture. As the market matures, product attributes (Class 1 vs. Class 2, multi-function analyzers, wireless/cloud connectivity) increasingly differentiate pricing power and aftermarket revenue.
Sound Level Meters Market -
Supply chain and cost structure choices are key. The labor intensity of manufacturing and calibration — which materially affects high-end instrument pricing — makes strategic choices about where to locate manufacturing and calibration essential to competitive positioning.
-
Investment and M&A playbooks need precise TAM/SAM orientation. With a clear historical-to-forecast trajectory, corporate development teams can prioritize bolt-on acquisitions or product investments that accelerate entry into high-opportunity pockets.
Market trajectory and what it means for 2026
The market’s historical evolution through 2020–2025 shows an acceleration in commercial activity that culminates in a significant market size in the report’s base year. Our forecast through 2032 projects continued expansion to a materially larger market, driven by a blend of regulatory enforcement, asset monitoring for urban and transportation projects, and the diffusion of smart, connected measurement solutions. The applied CAGR of 5.85% reflects a balance of continued investment in environmental and occupational monitoring, offset by pockets of commoditization where lower-cost Class 2 instruments and integrated sensing modules are gaining traction.
For decision-makers in 2026, two structural takeaways matter. First, regulatory stability and reaffirmations (for example, the persistence of IEC 61672-1 requirements through 2029 and relative harmonization with ANSI/ASA S1.4) reduce standards risk but increase the importance of certified compliance and documented calibration trails. Second, technological convergence — combining sound level measurement with cloud connectivity, multi-channel analysis, and integrated dosimetry — creates premium product tiers and services that command higher lifetime value.
Competitive landscape — concentration and strategic positioning
The market exhibits moderate concentration: the top three vendors account for a majority share of industry revenue, with the top five accumulating an even larger portion. This concentration crystallizes the competitive dynamics: incumbent precision-instrument manufacturers retain strong brand and standards credentials, while a more diverse group of regional and specialist vendors compete on price, functionality, and service networks.
-
Brüel & Kjær (Denmark) — a long-established leader with professional Class 1 instruments, marketed for precision environmental and laboratory-grade applications. Their product heritage remains a reference point for calibration and measurement accuracy.
-
Larson Davis (USA) — focused on occupational and environmental instruments, with recent product iterations tailored for workplace health professionals. Their Spartan and SoundExpert series reinforce position in regulated occupational markets.
-
HBK (Germany) — combining product engineering with app-enabled workflows, positioning instruments as integrated system components in test-and-measurement portfolios.
-
Quest Technologies/3M, TSI, and others (USA) — differentiated by modular systems and wireless occupational solutions, expanding platforms that integrate into broader industrial hygiene toolkits.
-
European and Asia-Pacific specialists (Norsonic, Rion, Casella, NTI Audio, Svantek, Cirrus Research, and others) — competing on regional service, specialized features (FFT, multi-channel, vibration cross-analysis), and targeted compliance solutions.
Recent product activity underscores market direction: TSI’s 2025 release of a Class 2 module for its OmniTrak™ platform expands wireless workplace noise measurement and reporting capabilities; Larson Davis continues to enhance its Spartan series for occupational health use; and Rion’s introduction of a Class 2 model with FFT support demonstrates demand for advanced analysis features even in lower-tier instruments. These moves reflect a two-track market: precision, certified Class 1 systems for regulatory and research use, and flexible, connected Class 2 modules for field occupational and facility monitoring. Both tracks present differentiated revenue and service expansion opportunities.
Regulatory and cost dynamics shaping 2026 decisions
-
Standards and compliance: The IEC 61672-1 stability window through 2029 and reaffirmations of ANSI/ASA S1.4 reduce near-term standards uncertainty but raise the bar for documented calibration and verification processes in buyer procurement specifications.
-
Workplace enforcement: OSHA’s referencing of ANSI specifications and NIOSH’s emphasis on accessible measurement (including app-based tools) are fueling demand for instruments that can demonstrably support hearing-loss prevention programs.
-
Manufacturing and calibration costs: Labor-intensive manufacturing and calibration for professional Class 1 meters underpin higher price points and longer product life cycles. This creates both margin opportunities for premium vendors and cost-pressure risks for mass-market suppliers.
What the PW Consulting report contains — operationally usable content
PW Consulting’s full report goes beyond high-level narrative. It includes:
-
A decade-plus historical dataset and scenario-modeled forecasts to 2032 with sensitivity analyses by demand drivers and regulatory scenarios.
-
Price and margin ladders across product tiers and use cases, with calibration and service-cost modeling that illuminates aftermarket revenue potential.
-
Provider benchmarking: capability matrices, certification coverage, distribution footprints, and an assessment of product roadmaps for the leading vendors.
-
Regulatory matrix and compliance playbook: practical checklists for procurement, audit preparation, and product certification timing tied to major standards and enforcement pathways.
-
Commercial playbooks and go-to-market options: channel strategies, partnerships with occupational-health service providers, and product bundling templates for SaaS-enabled workflows.
-
Investment heatmaps and M&A playbooks highlighting where scale, tech differentiation, and service networks converge to create acquisition value.
Practical recommendations for executives in 2026
-
Prioritize certified compliance in product lines: ensure key SKUs meet the necessary IEC/ANSI requirements and that calibration processes are auditable for corporate and public-sector buyers.
-
Invest selectively in software and connectivity: cloud data management, automated reporting for compliance, and device fleet monitoring materially increase customer stickiness and recurring revenues.
-
Rebalance product portfolio across precision and modular tiers: maintain premium Class 1 capabilities while accelerating lower-cost, connected modules for occupational customers who prioritize ease-of-use and fleet-level insights.
-
Optimize manufacturing and calibration supply chains: evaluate regional calibration hubs and partnerships to reduce lead times and cost exposure from labor-intensive workflows.
-
Build or buy analytical capabilities: FFT, multi-channel, and vibration-coupled analytics are differentiators for environmental and R&D buyers; consider partnerships or acquisitions to fast-track feature sets.
-
Use market concentration to shape competitive tactics: incumbents should defend premium channels and service contracts; challengers should exploit niche verticals and rapid deployment solutions.
-
Align commercial contracts with lifecycle services: extend warranty and calibration packages to capture post-sale revenue and improve customer retention.
Conclusion — the strategic value of timely intelligence
For corporate strategists, product leaders, and investment teams preparing 2026 plans, the principal value of this research is its synthesis of regulatory, technological, and commercial dynamics into a forward-looking, actionable framework. The market’s projected expansion through 2032, combined with steady CAGR dynamics and a concentrated competitive field, creates clear windows for differentiated plays in product engineering, service design, and M&A.
PW Consulting’s full study contains the granular segmentation, pricing ladders, and region-and-application breakdowns that operational teams need to build precise investment models and go-to-market plans. To examine the detailed splits, vendor benchmarking tables, and downloadable datasets that underpin the strategic recommendations summarized here, please access the full report on our website — the proprietary data will enable your team to convert insight into 2026 action plans with confidence.
For detailed analysis of this topic, please visit the official page: Sound Level Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVC Market to Reach USD 81.57B by 2032 with 18.12% CAGR
By pmarketresearch, 2026-07-08
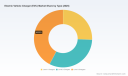
Electric Vehicle Charger (EVC) Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive summary
The EVC market is no longer an emerging niche — it has entered a structural growth phase that will reshape energy systems, mobility business models, and capital allocation decisions over the next decade. Our market model shows a clear trajectory: the global market expanded from USD 4.82 Billion in 2020 to USD 25.55 Billion in 2025 and is projected to reach USD 81.57 Billion by 2032, driven by an 18.12% compound annual growth rate (CAGR) across the 2026–2032 forecast window. For corporate leaders planning investments, partnerships or new product launches in 2026, this report is designed to translate the numbers into executable strategy — while reserving the granular segmentation tables and proprietary scenarios for subscribers and website visitors.
Electric Vehicle Charger (EVC) Market
Why this study matters for 2026 decisions
-
Timing is strategic: 2026 is a pivot year. Many policy, manufacturing and grid-integration initiatives launched in prior years will converge into operational-scale deployments in 2026–2028. Executives who align product roadmaps and channel strategies to this timing capture outsized returns.
Electric Vehicle Charger (EVC) Market -
Macro growth with concentrated execution challenges: strong aggregate expansion masks complex operational constraints — from site acquisition and permitting to uptime enforcement and local content rules. The ability to translate market growth into dependable, high-utilization revenue streams will separate winners from the rest.
Electric Vehicle Charger (EVC) Market -
Capital and partnership design: the financing of charger rollouts is evolving from capex-heavy proprietary models to hybrid structures that blend subsidies, tax incentives, performance contracts and grid-support revenues. The report provides practical frameworks for structuring these deals in 2026.
Market trajectory — what the headline numbers imply
Our base-year calibration (2025) anchors the model and illustrates a multi-year acceleration: after a period of rapid adoption from 2020–2022, the market consolidated in 2023–2025, establishing scalable supply chains and clearer deployment economics. The projected increase to USD 30.3 Billion in 2026 and the sustained growth to USD 81.57 Billion by 2032 reflect multiple, concurrent demand drivers — vehicle electrification rates, public and private charging investments, and the monetization of grid services through bidirectional and battery-integrated systems.
Critically, aggregate growth does not guarantee distributed profitability. Our analysis shows that revenue pools will shift between fast DC charging, managed AC deployments, residential installations and public hubs depending on regulation, utility tariffs and real-world utilization. This is why 2026 strategies must be differentiated by vertical (fleet, retail, residential) and by monetization model (paid charging, subscription services, grid services), rather than assuming uniform uptake.
Strategic implications by stakeholder
-
OEMs and hardware manufacturers: prioritize modular, software-updatable platforms that enable rapid power-scaling and remote diagnostics. Customers in 2026 will expect future-proofing — not legacy fixed-output units. Manufacturing footprint decisions must now factor in evolving trade and local content rules.
-
Charging network operators and site hosts: focus on uptime economics and integrated payment/roaming stacks. Regulatory regimes are moving towards strict reporting and uptime thresholds; operational reliability will be a competitive moat.
-
Utilities and grid operators: design tariffs that reward flexible load and enable co-optimized investments in distribution reinforcements and behind-the-meter storage. Grid-interactive charging solutions present a pathway for non-wires alternatives to accelerate charger density without prohibitive distribution upgrades.
-
Investors and financiers: structure capital with performance tranches linked to availability, energy throughput and ancillary service participation. The report includes valuation templates that stress-test portfolios against realistic uptime and utilization scenarios.
Competitive dynamics — mapping capabilities and recent moves
The market remains moderately fragmented, with leading players demonstrating differentiated strategies across hardware power, software, and manufacturing footprints. Measured concentration metrics show top-three share and top-five share that indicate room for consolidation and alliance formation rather than immediate monopoly formation.
-
XCharge — Specializes in high-power DC fast charging and integrated battery solutions. Its strategic expansion into European assembly capacity in 2026 signals an ambition to reduce lead times for high-power units and to position GridLink-enabled products in public fleet and hub deployments. For corporates, XCharge highlights the importance of aligning product roadmaps with regional manufacturing strategies to mitigate logistics risk.
-
Kempower — Known for modular DC fast chargers and scalable power modules suited for public hubs and heavy-duty applications. Its partnership activity in early 2026 underscores a broader industry trend: interoperability and simplified payment integration are becoming table stakes. OEMs that package modularity with open ecosystem integrations will unlock larger deployment pipelines.
-
Enphase Energy — Bringing bidirectional charging to market linked with distributed energy assets such as solar and storage. The move into volume production timelines in late 2026 suggests that vehicle-to-home and vehicle-to-grid capabilities are transitioning from pilot to commercial deployments, creating new value streams for residential customers and aggregators.
Regulation, incentives and operational constraints — immediate priorities
Policy developments in the U.S. and elsewhere introduce both risks and opportunities that should be modeled in 2026 strategy workstreams:
-
Operational reliability is becoming a regulatory obligation. New standards require frequent reporting of charger inventory and uptime for commercial operators and set minimum uptime benchmarks for recently installed equipment. Compliance will necessitate investment in monitoring, service provisioning and SLA enforcement.
-
Local content and procurement rules are tightening in key markets. Proposed modifications to domestic manufacturing requirements will alter sourcing economics for projects obligated after specific policy effective dates — accelerating decisions on where to locate final assembly and which BOM components to domesticize.
-
Tax credits and residential incentives remain a force-multiplier for EV charger adoption. Residential incentives can lower acquisition costs and accelerate managed-charging adoption if coupled with smart home or V2H products.
What our report contains — practical deliverables for 2026 action plans
This study is built to be a decisioning tool. Subscribers receive:
-
Market sizing and a demand model from 2020–2032 with scenario toggles for vehicle adoption, utilization rates and policy shifts.
-
Commercialization playbooks for major verticals (public hubs, retail, workplace, fleets, multifamily and single-family residences) including go-to-market timelines, margin profiles and procurement checklists.
-
Competitive landscaping with capability matrices, M&A/red team playbooks and supplier risk assessments.
-
Regulatory impact models mapping uptime, reporting and local-content policies into P&L and deployment feasibility outcomes.
-
Operational templates: uptime SLAs, remote diagnostics ROI calculators, and field-service cost models tailored to charger classes and use cases.
-
Investment scenarios and valuation models designed for financiers and corporate development teams to stress-test acquisition targets and joint-venture structures.
How to use this research in 90–180 day planning cycles
-
90 days — Rapid alignment: run the base and downside scenarios against your planned 2026 rollouts, update supplier agreements to reflect potential local-content requirements, and accelerate pilot deployments for uptime validation.
-
180 days — Scaling and capitalization: finalize manufacturing footprints, negotiate performance-linked financing, and lock down partnerships for payment, grid services and site-hosting. Use the report’s procurement playbook to de-risk tender responses and public bids.
Final note — what we intentionally hold back (and why)
Consistent with our “trailer” approach, this introduction demonstrates the report’s analytical depth and practical focus while reserving detailed segment-level tables, downloadable models, and proprietary vendor scoring for the full study. Those detailed data layers — including regional and application splits, full unit economics, and downloadable scenario models — are accessible on our website and are critical for transaction-level decision-making in 2026.
Next steps
For corporate strategy teams, investor groups, and product leaders preparing to make or defend 2026 commitments, we recommend ordering the full report to acquire the complete dataset, customizable models, and the supplier playbooks that translate strategy into executable plans. Contact PW Consulting via the source page to access the full intelligence package and schedule a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Charger (EVC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Doors Market Insights — 4.2% CAGR Forecast (2026–2032)
By pmarketresearch, 2026-07-08
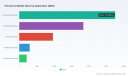
Fire Doors Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest Fire Doors Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) translates a complex product-and-compliance ecosystem into a practical playbook for executives, investors, and procurement leaders preparing to act in 2026. The report synthesizes macro demand trajectories, regulatory inflection points, supply-chain constraints and competitive dynamics so you can prioritize investments with conviction. At the highest level: the global market is expanding at a steady compound annual growth rate (CAGR) of 4.2%, moving from a mid‑single‑digit billion USD opportunity in 2025 toward a substantially larger installed base by 2032 (values reported in USD Million). This growth masks uneven pockets of opportunity and risk — exactly the kind of nuance that separates transactional choices from strategic moves.
Fire Doors Market
Why this research matters in 2026
-
Regulatory momentum has created a hard deadline for capabilities. The 2025 edition of NFPA 80 increases inspection cadence and introduces performance‑based options that materially affect aftermarket services, compliance audits, and product documentation demands. Simultaneously, an updated UL 10C revision (effective 2026) tightens hardware requirements for locks and latches — driving both product redesign and upgraded test plans.
Fire Doors Market -
Certification and testing are now system-level constraints. Leading standards bodies and accreditation requirements emphasize full‑assembly testing (door leaf, frame, hardware, seals, glazing) under ISO/IEC 17025‑compatible regimes. Firms that treat certification as a cost center will find themselves outpaced by those that integrate testing into product development and commercial service offers.
Fire Doors Market -
The market’s structural profile favors specialization and service differentiation. Measured concentration is low: top-three and top-five shares are modest, indicating fragmentation and a long tail of regional suppliers. For buyers and investors this creates both sourcing complexity and M&A optionality.
Macro snapshot (strategic takeaways)
-
Steady expansion. The market recorded consistent growth through 2020–2025 and is projected to continue through the 2026–2032 forecast window at a 4.2% CAGR. This trajectory supports capacity investments, but the returns are highly sensitive to product mix, standards compliance and aftermarket penetration.
-
Regulation as a demand-shaper. The new NFPA 80 and UL updates function as quasi-demand drivers for inspection, retrofitting and replacement cycles. Organizations that can bundle compliant hardware with inspection and maintenance services will capture outsized margins.
-
Fragmentation equals opportunity. Low market concentration creates space for consolidation plays, regional scale-ups, and specialist platform strategies (e.g., vertical integration of testing, installation and field services).
Competitive landscape — what the leading players signal
The market features a mix of global platform incumbents, specialist manufacturers, and regional producers. Recent strategic moves reveal three dominant themes:
-
Consolidation to broaden product-and-service scope: Major platform players are actively acquiring adjacent capabilities — from hardware specialists to service networks — to secure end‑to‑end control of compliant door ecosystems.
-
Product innovation focused on operability and compliance: New low‑energy door assistants and hardware designed to meet the 2026 UL requirements are being introduced, signaling competition around usability without compromising fire performance.
-
Service and aftermarket as margin pools: Acquisitions of fire‑safety service providers reflect a bet that inspection, maintenance and certification services will be durable cash flows as regulatory scrutiny rises.
Representative strategic moves include high‑profile acquisitions and product launches that highlight where incumbents are placing their chips. You should view these moves as directional indicators rather than exhaustive company valuations — they clarify where value is migrating (service networks, certification, product systems) and where competition will intensify (hardware and integrated assemblies).
Practical contents of the PW Consulting report
Our research is designed to be operationally actionable for leaders making capital allocation, product development, channel and M&A decisions in 2026. The deliverables include:
-
Market sizing and seven‑year forecasts (2026–2032) at the total market level, with scenario models that allow you to stress-test outcomes against regulatory and raw‑material shocks.
-
Demand-driver analysis including construction starts, retrofit cycles, regulatory enforcement intensity and public‑sector procurement triggers.
-
Supply‑chain mapping that highlights single‑sourcing risks, certification bottlenecks, and logistics exposures for critical inputs and pre‑assembled systems.
-
Commercial playbooks: go‑to‑market strategies for OEMs, distributors and system integrators; tender and pricing templates for large institutional buyers; and customer segmentation models for aftermarket service monetization.
-
Compliance and testing roadmap showing how to convert new regulatory requirements (e.g., NFPA 80 2025, UL 10C 2026) into product roadmaps and service offerings that minimize time‑to‑market risk.
-
Opportunity scanner for M&A and partnerships, highlighting target archetypes (service providers, hardware specialists, certified assembly manufacturers) and high‑leverage integration levers.
Key strategic recommendations for 2026
-
Prioritize certification‑first engineering. Treat full‑assembly testing and ISO/IEC 17025‑aligned labs not as compliance overhead but as growth enablers. Investing in or partnering with accredited test facilities reduces time‑to‑market friction and creates an entry barrier for lower‑quality alternatives.
-
Monetize service intensity. With NFPA 80 mandating post‑installation inspections and minimum periodic checks, build recurring revenue models around inspection, maintenance and digital lifecycle management. Bundled hardware+service contracts will command premium pricing and higher lifetime value.
-
Design for hardware resilience. UL 10C revisions sharpen the focus on locks, latches and security. Re‑engineer product specifications to meet the new thresholds and use compliance as a commercial differentiator in tenders for institutional customers.
-
Adopt a hybrid scale‑and‑specialist M&A strategy. Given low market concentration, there’s room for roll‑ups of regional manufacturers and services. Target acquisitions that provide field capacity or certification capabilities rather than solely product SKUs.
-
Localize critical supply chains. Countries introducing mandatory national certification (for example, tighter enforcement of local standards) increase demand for locally produced, certified assemblies — this favors firms that combine manufacturing scale with local compliance footprints.
-
Digitize inspection and warranty processes. Invest in IoT‑enabled sensors, inspection workflow software and centralized certification repositories to shorten audit cycles, reduce liability and create upsell pathways for predictive maintenance.
Risks and mitigants
-
Regulatory enforcement variability: Differences in enforcement intensity across jurisdictions can create short-term demand volatility. Mitigate by designing modular compliance packages that can be adapted to regional inspection regimes.
-
Certification bottlenecks: Laboratory capacity constraints can delay product launches. De‑risk by pre‑booking test slots, co-investing in accredited labs, or using recognized third‑party certification partners.
-
Price pressure from large local manufacturers: High‑volume producers may undercut on commodity doors. Compete with services, compliance guarantees and higher‑margin system assemblies.
How leaders should use this analysis in 2026
Executives should treat the report as a decision‑support toolkit: use the scenario models to size capital expenditures, apply the compliance roadmap to de‑risk product introductions, and deploy the M&A scanner to prioritize targets that accelerate service capabilities. For investors, the fragmentation offers a clear playbook — back platforms that can execute roll‑up strategies focused on certified assembly, field services, and digital inspection assets.
Next steps — what the full report delivers (and what we intentionally withheld)
To preserve strategic leverage for our clients and to follow the “trailer” principle of this briefing, we have intentionally withheld granular segment‑level figures and certain region/application splits from this introduction. The full PW Consulting Fire Doors Market report contains:
-
Detailed segment-level forecasts by material, application and region (with scenario toggles).
-
Competitive profiles with relative market positioning and private benchmarking data.
-
Transaction comps, valuation ranges for roll‑up targets, and an M&A integration checklist tailored to fire‑door assemblies and services.
-
Practical templates (tender language, OEM‑installer SLAs, inspection checklists) that you can deploy within 90 days of acquisition.
For teams making capital allocation and operational choices in 2026, the choice is straightforward: follow the report’s compliance‑driven, service‑led framework to convert regulatory change into sustainable revenue streams. PW Consulting’s full study provides the granular maps and models required to execute — from product redesign to M&A prioritization and commercial roll‑out.
Contact
Access the full analysis and supporting datasets through the PW Consulting portal to obtain the segmental forecasts, company valuations and deployment templates that will enable decisive action in 2026.
For detailed analysis of this topic, please visit the official page: Fire Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryocoolers Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-08
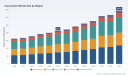
Cryocoolers Market 2026: Strategic Insights for Executive Decision-Making
Executive summary
As organizations across defense, space, medical imaging, quantum technologies, and industrial gas systems plan capital allocation and product roadmaps for 2026, cryocoolers are transitioning from niche enabling components to strategic system-level differentiators. PW Consulting’s latest study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market dynamics, regulatory shifts, supplier positioning, and technology trajectories into an operational playbook for leadership teams. The global cryocoolers market has expanded materially from 2020 to 2025 and—growing at a compound annual growth rate (CAGR) of 6.98%—is forecast to continue through 2032, reflecting accelerating demand from quantum, space, and defense programs.
Cryocoolers Market
Why this report matters to 2026 decision-makers
- Timing: 2026 is a pivotal year for procurement, certification, and supplier consolidation decisions. Several large programs (defense night-vision upgrades, satellite constellations, and quantum commercialization pilots) require procurement commitments or design freezes this year.
- Risk management: New export-controls and testing requirements introduced between 2024–2026 increase compliance complexity and supplier due-diligence burdens for global programs.
- Investment focus: R&D and capex choices made in 2026 will determine who captures the higher-value system integrations emerging by the early 2030s—particularly for long-duration space cryogenic storage and low-vibration quantum cryocoolers.
- Supplier strategy: The market remains fragmented (CR3 ≈ 24.6%; CR5 ≈ 26.2%), which creates opportunities for both large integrators and nimble specialists to scale through targeted partnerships or M&A. Our research maps the commercial levers to exploit this fragmentation.
Market trajectory — a concise data-driven view
PW Consulting’s topline metrics provide a clear frame for strategic planning: the global cryocoolers market increased steadily from 2020 into 2025, and with the base year set at 2025 our forecast extends through 2032 under a mid-cycle scenario (CAGR 6.98%). This trajectory reflects a convergence of drivers—expanded satellite and ISR payloads, quantum-computing deployments, and broader industrial and energy uses—that are reshaping demand profiles and unit economics. While we disclose the aggregate market path in this preview, detailed segment and regional splits are intentionally withheld here to preserve the report’s role as the definitive commercial reference.
Cryocoolers Market
What the full PW Consulting study contains (practical, actionable content)
- Market sizing and forecasting model (base year 2025, historical coverage 2020–2025, forecast 2026–2032) with downloadable scenario files and sensitivity levers for price, adoption, and substitution.
- Demand-driver deep dives: satellite payload schedules, defense procurement cycles, quantum and superconducting use-cases, medical imaging replacement timelines, and industrial gas/liquefaction projects.
- Regulatory & export-control matrix: program-level compliance impacts, national control lists, and practical steps for dual-use supply chains (updated to reflect 2024–2026 rule changes).
- Supplier benchmarking toolkit: capability maps, product-readiness matrices (TRL mapping), and procurement scorecards to accelerate vendor selection and risk mitigation.
- Commercial playbooks: go-to-market options by buyer archetype (prime integrator, OEM, national lab, commercial quantum provider) including pricing and service models that preserve margin while enabling adoption.
- M&A and partnership blueprint: prioritized target lists, valuation comparables, and integration checklists for acquiring complementary cryocooler technologies or manufacturing capacity.
- R&D and product roadmap templates: low-vibration, high-uptime, and low-mass architectures; cooling-power tradeoffs; and quick-win design modifications to shorten qualification cycles.
- Supply-chain resilience planning: critical-buoy component lists, alternate sourcing strategies, inventory sizing guidelines, and nearshoring scenario analysis keyed to regulatory constraints.
- Executive dashboards and decision-support worksheets: cash-flow impacts, TCO calculators, and scenario-based NPV comparisons for strategic investment options.
Competitive landscape — who matters and why
The cryocooler ecosystem mixes long-established industrial players, defense primes, and specialized innovators. Rather than a winner-takes-all market, the current structure rewards technology depth, systems-integration capability, and supply-chain resilience.
Cryocoolers Market
- Sumitomo Heavy Industries (Tokyo) — broad portfolio strength across Gifford-McMahon and pulse-tube families for space, medical imaging, and defense. Their strategy emphasizes high-capacity, lower-maintenance designs that play well into long-duration missions.
- Northrop Grumman (Washington, DC) — leverages systems-integration expertise to embed custom Stirling and pulse-tube units in satellite and sensor payloads. Their competitive edge is integration and mission assurance at prime-contractor scale.
- AMETEK / Sunpower (Waltham) — focuses on Stirling technology optimized for low vibration and maintenance-free operation, attractive for aerospace and sensitive instrumentation.
- Chart Industries (Boulder) — industrial cryogenics specialist; its strength is in scale for gas liquefaction and energy applications where system-level cryogenic management is the differentiator.
- Bluefors (Helsinki) & Cryomech (Syracuse) — pulse-tube leaders targeting quantum and superconducting detector markets with compact, high-performance designs; high-growth adjacency as quantum commercialization matures.
- RICOR, AIM Infrarot-Module, RIX Industries, Stirling Cryogenics — niche specialists in miniature Stirling and premium infrared detector coolers; critical suppliers for defense IR and scientific instrumentation.
- Thales, L3Harris — defense and aerospace primes integrating cryocoolers into night-vision, ISR, and space systems. Their primary moat is system-level certification and secured program flows.
- Air Liquide, Advanced Research Systems, Lake Shore, Superconductor Technologies — combine component-level expertise with downstream system services, especially for research and industrial customers.
Collectively, the market’s low concentration metrics indicate opportunity: large primes can differentiate through integration and service offerings, while specialists can scale by carving application-led niches or partnering with OEM integrators.
Regulatory and technology dynamics to watch in 2026
- Export controls: Recent national controls (e.g., updates in 2024–2026) have added complexity to cross-border supply chains and technology transfers. Buyers and sellers must incorporate export classification and licensing timelines into procurement gates.
- Technology readiness requirements: Programs such as NASA’s CACHE initiative are pushing high-capacity cryocooler TRL thresholds for space cryogenic storage—this raises the bar for vendors seeking inclusion in long-duration mission bids.
- Conference and knowledge flows: Industry forums (notably the June 2026 International Cryocooler Conference) will accelerate transparency on performance benchmarks and integration learnings—attendance and targeted sponsorships are high-ROI activities for market entrants.
- Product innovation: Recent product launches signal performance inflection points—compact two-stage pulse-tube systems for superconducting detectors and whisper-quiet, higher-capacity single-stage units for space and defense. These design advances change system architecture decisions and lifecycle cost profiles.
Strategic moves for executives in 2026 (prioritized)
- Immediate (0–6 months) : Incorporate export-control gating into all procurement and partnership contracts; run a rapid supplier compliance audit to identify potential license needs and contingency suppliers.
- Near-term (6–12 months) : Adopt the PW scenario model to test procurement vs. in-house development trade-offs for high-volume programs; prioritize vendor scorecards that include TRL, spares lead time, and proven integration experience.
- Medium-term (12–24 months) : Form strategic partnerships with pulse-tube and Stirling specialists to co-develop low-vibration and high-life-cycle products tailored to your system requirements—focus on IP-sharing arrangements that preserve optionality.
- Portfolio strategy : For investors and corporate development teams, target tuck-ins that add cryocooler miniaturization or thermal-storage capability; valuation discipline should factor in long qualification cycles and export uncertainty.
- Operational resilience : Rebalance inventories of critical components, invest in dual-sourcing for high-vulnerability subassemblies, and evaluate nearshoring options where regulatory risks are material.
- Talent & R&D : Hire systems engineers with cryogenics integration experience and seed focused R&D on vibration mitigation and mean-time-between-failure (MTBF) improvements—small performance gains translate to outsized system-level advantages.
How PW Consulting’s deliverables support execution
- Customizable financial models and procurement templates to compress vendor selection timelines from months to weeks.
- Operational checklists for export compliance and supplier audits aligned to the latest 2024–2026 regulatory changes.
- M&A diligence packs and integration plans that reflect cryocooler-specific certification and qualification timelines.
- Workshops and executive briefings to cascade findings into program planning and R&D prioritization.
Closing — a trailer, not the full film
This briefing is deliberately selective. It communicates the market’s direction, the regulatory headwinds, the competitive topology, and the practical strategic moves that should be on every executive’s 2026 agenda—while withholding the granular regional, type, and application splits that underpin our proprietary valuation and vendor-ranking models. PW Consulting’s complete Cryocoolers Market report contains those detailed breakdowns, downloadable models, and supplier scorecards essential for transaction-level decisions. For clients preparing procurement specifications, investment memoranda, or program roadmaps in 2026, the full study converts market insight into executable advantage.
To access the full dataset, scenario models, and supplier benchmarking tools, please visit our report page or contact PW Consulting’s team for a tailored executive briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Cryocoolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Exoskeleton Robots Market to Reach USD 363M by 2032 at 17.15% CAGR
By pmarketresearch, 2026-07-08
Exoskeleton Robots Market: Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present an executive preview of our new Exoskeleton Robots Market study — a practitioner-focused synthesis designed to convert the market’s accelerating momentum into concrete boardroom decisions in 2026. This is not a catalogue of figures; it is a strategic briefing that blends verified market trajectory, regulatory inflection points, supplier positioning and actionable playbooks. The objective: equip executives with the situational intelligence needed to prioritize investments, structure pilots, and de-risk commercialization across healthcare, industrial, defence and emerging consumer use cases.
Exoskeleton Robots Market
Market trajectory: growth, scale and strategic inflection
The exoskeleton market is no longer speculative. After consistent expansion through the early 2020s, total industry revenues have accelerated and are projected to continue on a robust upward path. Using 2025 as the base year, our consolidated market model shows sustained double‑digit growth into the early 2030s at a compound annual growth rate of approximately 17.15%. This translates into a near‑term imperative: 2026 is the year to move from experimentation to structured deployment if organizations want to capture first‑mover advantage in procurement, clinical evidence generation, or industrial scale‑up.
Exoskeleton Robots Market
Three strategic consequences flow from this trajectory. First, product and service economics will shift from unit sales to lifecycle value — warranty, maintenance, training and data services will be material contributors to margin. Second, buyers will demand validated outcomes (safety, productivity or clinical efficacy) rather than vendor promises. Third, regulatory and reimbursement milestones will be the primary accelerants or gates for enterprise adoption; companies that align product development and commercialization to these milestones will outpace competitors.
Exoskeleton Robots Market
Why this study matters in 2026
- Actionable regulation intelligence: Recent rule‑setting has changed the compliance landscape. Testing standards for commercial and enterprise robots have been elevated in the U.S. regulatory ecosystem and internationally relevant medical device rules have been updated for powered wearable systems. Executives need a compliance roadmap, not a checklist.
- Reimbursement as a force multiplier: Early listings under public reimbursement pathways are proving that exoskeletons can cross the procurement chasm — but successful claims and programmatic adoption require documented clinical protocols and cost‑effectiveness evidence. Our analysis shows how early adopters unlock procurement cycles by sequencing clinical trials and payer engagement.
- Supply chain and runtime economics: Battery chemistry and component availability remain the gating constraints for operational runtime and unit economics. Integration strategies with battery and power management partners are as strategic as product features in determining market acceptance.
- Fragmented but consolidating supplier base: Market concentration remains modest, leaving space for both focused specialists and broad systems integrators. That creates a window for partnerships, vertical integration and targeted M&A.
What the report delivers — practical content for dealmakers and operators
Our study was designed to be implemented. Highlights of the operational content include:
- Proven market sizing and forecast methodology, with sensitivity scenarios for technology adoption, regulatory timing and reimbursement uptake.
- Decision matrices and procurement playbooks for hospital systems, industrial buyers and defence organizations (including pilot design templates, KPIs and go/no‑go triggers).
- TCO and ROI models that incorporate capital cost, training, maintenance, consumables and productivity gains; templates are pre‑configured for enterprise CFO stress‑testing.
- Regulatory compliance playbook mapping global pathways, recognized consensus standards and test protocols for both safety and therapeutic claims.
- Reimbursement readiness kits featuring clinical evidence roadmaps, payer engagement timelines, and coding/coverage strategies.
- IP and supplier due‑diligence guides, including manufacturing scale assessments, component risk checklists and partner scorecards.
- Human factors evaluation toolkit: protocols for ergonomic validation, user acceptance testing and change management for frontline workforces.
- M&A and commercial partnership screening: target profiles, valuation heuristics and integration risk matrices aligned to strategic objectives.
Note: In keeping with our “preview” approach, this executive article highlights the strategic insights and frameworks. Detailed sub‑segment breakouts, region‑level demand curves and competitor revenue tables are intentionally reserved for the full report and its downloadable datasets.
Competitive landscape — patterns that determine winners
The supplier universe can be understood through three archetypes that appear repeatedly across competitive assessments:
- Specialist clinical innovators: Vendors focused on rehabilitation and neurological therapy are differentiating through clinical evidence, hospital partnerships and device classifications. Clinical trial positioning and payer evidence generation are their primary assets.
- Industrial ergonomics and heavy‑duty integrators: Firms emphasizing tools for lifting, overhead work and load handling compete on durability, integration with workflows and total cost of ownership. These players are forming alliances with construction, manufacturing and logistics OEMs.
- Consumer and niche mobility entrants: Emerging teams target outdoor, sport or personal mobility use cases with emphasis on affordability, certification to consumer performance standards and novel powerform factors.
Recent market activity corroborates this pattern: industrial suppliers have released next‑generation arm and shoulder systems certified for occupational use; clinical players are initiating trials to secure reimbursement; consumer‑grade systems debuted at major technology shows; and one notable regional player completed a public offering to fund global expansion. These developments reflect an industry that is moving from lab to regulated, reimbursed and commercialized offerings.
From a concentration perspective, the market shows moderate fragmentation: the three largest players capture less than a third of market revenues and the five largest account for under forty percent. That dynamic creates substantial opportunity for niche specialists to scale via partnerships or for larger industrial and medical device incumbents to accelerate capability via M&A.
Selected supplier behaviors to monitor (strategic signals)
- Integration of embedded AI and sensors to translate device usage into measurable outcomes and services revenue.
- Moves to obtain occupational safety certifications and medical device clearances in parallel — a dual‑path regulatory strategy that de‑risks both industrial and clinical endpoints.
- Commercialization through channel partners (medical distributors, construction OEMs and defense contractors) rather than direct sales — accelerating reach while managing installation and service costs.
- Capital markets activity and strategic fundraising to scale manufacturing and global market entries; public listings are enabling faster geographic expansion for some vendors.
Strategic recommendations for executives acting in 2026
- Pilot with intention: Run framed pilot programs with predefined success metrics (safety, utilization, productivity/clinical endpoints) and clear transfer‑to‑scale plans. Avoid indefinite “evaluation” pilots that collect data but fail to convert to procurement.
- Align compliance, clinical and procurement timelines: Map product clearances and occupational certifications to procurement windows so that buyer committees can sign off when compliance milestones are hit.
- Design aftermarket and services now: Warranty, remote monitoring, consumables and training create recurring margin pools — include them in procurement RFPs and partner contracts.
- Mitigate power and component constraints: Lock strategic supply agreements for battery modules and power electronics; evaluate hybrid energy solutions and rapid‑swap designs to maintain uptime.
- Invest in outcome measurement: Standardize data collection from the outset. Buyers and payers will require rigorous evidence of benefit; vendors who can deliver validated real‑world evidence will command premium positioning.
- Prepare for consolidation: Build an M&A watchlist and partnership scorecard. The competitive landscape will consolidate around firms that combine clinical credibility, scale manufacturing and field service networks.
Conclusion — what to do next
2026 is the pivot year: the market’s macro trajectory drives urgency, and regulatory plus reimbursement developments create a narrow window where disciplined programs can capture structural advantage. PW Consulting’s Exoskeleton Robots Market study provides the operational playbooks, validated financial models and regulatory roadmaps required to move from pilot to programmatic adoption. For leadership teams preparing investment cases, procurement roadmaps, or M&A decisions, the full report delivers the granular datasets, segmented forecasts and competitive intelligence you need to execute with confidence.
Access the full study for the complete segmented forecasts, regional demand curves, competitor revenue profiles and downloadable ROI models — all designed to convert the market’s momentum into measurable enterprise outcomes.
For detailed analysis of this topic, please visit the official page: Exoskeleton Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nuclear Valves Market to Reach USD 3,246.8 Million by 2032 at 6.1% CAGR — PW Consulting
By pmarketresearch, 2026-07-08
Nuclear Valves Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our new Nuclear Valves Market study. Anchored on a 2025 base and projecting through 2032, the analysis synthesizes historical trends (2020–2025), a rigorous forecast (2026–2032), and proprietary competitive intelligence to inform capital allocation, sourcing, and technology decisions in 2026. At the macro level, the market is positioned for steady expansion: our model shows a compound annual growth rate of 6.1% over the forecast window, with total industry revenues rising materially from the mid-2020s baseline into the early 2030s. This preview outlines why that trajectory matters, how established and emerging suppliers are responding, and what pragmatic actions buyers, suppliers, and investors should consider now.
Nuclear Valves Market
Why this study matters for 2026 strategies
- Policy and programme timing — 2026 is a decision inflection point for many utilities and developers: choices made this year about valve qualification strategies, long-term service agreements, and supplier shortlists will determine readiness and cost for both traditional large reactors and the accelerating wave of SMR projects.
- Procurement and certification lead times — nuclear-grade valves require lengthy design control, stamping, and qualification. Our report quantifies the economic impact of those lead times on project cash flow and schedule risk, turning regulatory compliance from a checklist item into a strategic procurement lever.
- Aftermarket economics — as the installed base ages, lifecycle services (testing, diagnostics, refurbishment) represent a growing, higher-margin portion of supplier revenue. The study models aftermarket trajectories and identifies where service-led business models will outcompete pure OEM supply.
What the PW Consulting report delivers (practical, actionable content)
- Robust macro model covering historical performance (2020–2025) and a forecast (2026–2032) that incorporates scenario sensitivity to project pipeline, nuclear build-rates, and SMR rollouts.
- Decision-grade frameworks for procurement leaders: supplier shortlisting criteria, qualification roadmaps, and RFP language templates that reduce schedule and compliance risk.
- Supply-side diagnostics: capacity mapping, certification bottlenecks, materials and machining constraints, and contingency playbooks for key single-source nodes.
- Commercial guidance for OEMs and service providers: go-to-market plays for winning long-term utility partnerships, aftermarket monetization strategies, and prioritization of R&D investments (actuation, diagnostics, digital twin integration).
- Vendor benchmarking and deal playbooks: comparative profiles, capability matrices and negotiation levers tailored for both new-build and plant-life-extension contexts (note: the full vendor scorecards and numerical rankings are available in the full report).
- Risk matrices and mitigation strategies across regulatory, supply-chain, and geopolitical vectors to support board-level scenario planning.
Key market signals — data-driven perspective
From a top-line standpoint, the nuclear valves industry is growing at a mid-single-digit compounded pace. Our baseline indicates meaningful expansion from the 2025 base through 2032, reflecting a combined effect of new-build programs, SMR commercialization, life-extension projects, and increased spending on waste management infrastructure. Importantly, the market exhibits moderate concentration: a handful of established suppliers control a meaningful share of addressable demand, but there remains room for specialized players that can meet stringent certification and service requirements.
Nuclear Valves Market
For 2026 decision-makers, the implication is two-fold: buyers should lock in supply-chain resilience and long-term service arrangements now; suppliers should prioritize certification, strategic alliances, and targeted capacity investments to capture the higher-value segments of the evolving market.
Nuclear Valves Market
Competitive landscape — capabilities and strategic moves to watch
Our competitive analysis focuses on six firms that collectively exemplify the industry’s strategic dynamics: long-tenured OEMs with deep nuclear pedigree, global players expanding service portfolios, and regionally strong manufacturers pursuing export qualification.
- Crane Nuclear (Kennesaw, Georgia) — A legacy supplier with decades of performance in commercial plants. Strengths: long-standing ASME credentials, deep experience across Class 1–3 systems, and an installed-base service footprint. Strategic posture: maintaining reliability and aftermarket capture in established fleets.
- Neway Valve (Suzhou) — Represents the increasingly capable Asian supplier set that couples cost-competitive manufacturing with full nuclear-grade certifications. Strengths: wide product range and licenses aligned to multiple reactor designs. Strategic posture: export expansion through qualification to international codes and reactor programs.
- Trillium Flow Technologies (UK) — An engineered-valve specialist with emphasis on actuated systems and safety relief hardware. Strengths: ASME Section III stamps at multiple sites and a product set tailored to both new-build and OEM integration. Strategic posture: deepen long-term supply alliances with utilities (and leverage recent offtake-type deals).
- Velan Inc. (Montreal) — A market leader with early ASME 'N' credentials and a growing SMR services footprint. Recent contract wins on SMR programs underline the commercial value of being first-mover in qualification for next-gen reactors. Strategic posture: convert qualification advantage into lifecycle service franchises.
- Flowserve Corporation (Irving, Texas) — A diversified global supplier that bundles pumps, valves, and seals. Strengths: integrated hardware-software offerings and long-term utility relationships. Strategic posture: leverage cross-product platforms to win larger systems contracts and retrofit opportunities.
- Framatome (Paris) — A systems integrator with code expertise across ASME and RCC-M; recent M&A activity demonstrates a strategic intent to consolidate specialty valve capabilities and accelerate product breadth for PWR/BWR and advanced concepts.
Notable recent industry developments that shape 2026 strategies include long-term supply alliances, targeted M&A to consolidate engineered-valve capabilities, and SMR-related contract awards that favor suppliers already qualified to emerging reactor designs. These moves underscore two structural realities: certification equivalence is a de facto market access requirement; and service agreements are becoming as important as one-off equipment sales.
Regulatory and certification dynamics — entry barriers and opportunities
Certification and stamping regimes (ASME 'N'/'NPT', ASME Section III, and country-specific civil-nuclear grades) remain the dominant non-price entry barriers. Several suppliers highlighted in the report hold active stamps or national grade authorizations, and those credentials materially reduce time-to-contract on major projects. For 2026 planning, investors and procurement leads should treat certification programs as strategic investments with multi-year payback horizons—this is not a short-cycle CAPEX decision.
Risks, scenarios, and mitigation playbook
- Certification bottlenecks — Risk: delayed approvals for new production sites. Mitigation: staggered supplier qualification, dual-sourcing critical SKUs, and early engagement with certifying bodies.
- Single-source dependencies — Risk: concentrated supply of key forgings or specialty materials. Mitigation: develop secondary suppliers, leverage strategic inventory pools, and invest in joint-qualification exercises.
- Project timing mismatch — Risk: decoupling between valve deliveries and reactor critical-path milestones. Mitigation: align commercial terms to milestone-based deliverables and penalties, and plan for interim containment spares.
- Geopolitical and trade dynamics — Risk: export controls or policy shifts affecting cross-border supply. Mitigation: local content strategies, regional manufacturing partnerships, and contract clauses to manage regulatory-change exposure.
Actionable recommendations for 2026
- For utilities and EPCs: convert vendor shortlists into multi-year service alliances now, with contractual options for capacity reservation and qualification transfer protocols.
- For OEMs and valve manufacturers: prioritize certification investments tied to identified reactor platforms and target aftermarket service contracts to secure higher-margin recurring revenue.
- For investors and private equity: focus due diligence on suppliers with validated certifications and demonstrable aftermarket capabilities; stress-test acquisition targets against certification and capacity timelines.
- For suppliers in growth markets: pursue selective partnerships or acquisitions to bridge certification gaps quickly rather than attempting sole-source in-house qualification under time pressure.
Next steps — where the full intelligence sits
This preview is designed to establish the strategic frame for 2026 decisions: it shows the market’s growth trajectory, the certification-driven barriers to entry, the competitive moves shaping supplier advantage, and the concrete procurement and risk mitigations to prioritize. The full PW Consulting report contains the granular quantitative segmentation (region, valve type, and application), vendor scorecards with capability ratings, downloadable financial models, and full scenario outputs that underpin the headline 6.1% CAGR forecast. To access the full dataset, vendor rankings, and bespoke briefing options for executive teams, please visit PW Consulting’s Nuclear Valves Market portal or contact our advisory desk for a tailored executive workshop.
In an industry where certification, timing, and service-readiness determine value capture, 2026 is the year to convert market intelligence into durable commercial advantage. Our study gives you the roadmap—and the operational tools—to do just that.
For detailed analysis of this topic, please visit the official page: Nuclear Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com