

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sound Level Meters Market — USD 1.3B in 2025; 5.85% CAGR (2026–2032)

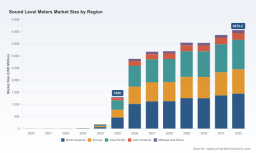
Sound Level Meters Market — Strategic Outlook for 2026 Decisions (PW Consulting)
As regulatory scrutiny, workplace health programs, and environmental monitoring priorities intensify worldwide, the market for sound level meters is moving from a niche instrumentation category into a strategic asset class for instrumentation vendors, occupational health teams, and infrastructure operators. PW Consulting’s latest Sound Level Meters Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical dynamics and a multi-scenario forecast built on a 5.85% compound annual growth rate (CAGR). All monetary figures in this briefing are reported in USD Million. The research is structured to arm executives and investment committees with the precise intelligence they need to make decisive moves in 2026 — while preserving the proprietary, drill‑down datasets that make the full report actionable.
Sound Level Meters Market
Why this research matters for 2026 strategic choices
-
Regulatory alignment is now a board-level issue. Sound level meters are no longer purely technical purchases for EHS teams — they are compliance tools shaped by standards such as IEC 61672-1 and ANSI/ASA S1.4 and referenced by authorities including OSHA and NIOSH. Our study maps how standards timing and reaffirmations will affect capital and operating expenditures across buyer groups in 2026.
Sound Level Meters Market -
Procurement timing and product segmentation decisions will determine margin capture. As the market matures, product attributes (Class 1 vs. Class 2, multi-function analyzers, wireless/cloud connectivity) increasingly differentiate pricing power and aftermarket revenue.
Sound Level Meters Market -
Supply chain and cost structure choices are key. The labor intensity of manufacturing and calibration — which materially affects high-end instrument pricing — makes strategic choices about where to locate manufacturing and calibration essential to competitive positioning.
-
Investment and M&A playbooks need precise TAM/SAM orientation. With a clear historical-to-forecast trajectory, corporate development teams can prioritize bolt-on acquisitions or product investments that accelerate entry into high-opportunity pockets.
Market trajectory and what it means for 2026
The market’s historical evolution through 2020–2025 shows an acceleration in commercial activity that culminates in a significant market size in the report’s base year. Our forecast through 2032 projects continued expansion to a materially larger market, driven by a blend of regulatory enforcement, asset monitoring for urban and transportation projects, and the diffusion of smart, connected measurement solutions. The applied CAGR of 5.85% reflects a balance of continued investment in environmental and occupational monitoring, offset by pockets of commoditization where lower-cost Class 2 instruments and integrated sensing modules are gaining traction.
For decision-makers in 2026, two structural takeaways matter. First, regulatory stability and reaffirmations (for example, the persistence of IEC 61672-1 requirements through 2029 and relative harmonization with ANSI/ASA S1.4) reduce standards risk but increase the importance of certified compliance and documented calibration trails. Second, technological convergence — combining sound level measurement with cloud connectivity, multi-channel analysis, and integrated dosimetry — creates premium product tiers and services that command higher lifetime value.
Competitive landscape — concentration and strategic positioning
The market exhibits moderate concentration: the top three vendors account for a majority share of industry revenue, with the top five accumulating an even larger portion. This concentration crystallizes the competitive dynamics: incumbent precision-instrument manufacturers retain strong brand and standards credentials, while a more diverse group of regional and specialist vendors compete on price, functionality, and service networks.
-
Brüel & Kjær (Denmark) — a long-established leader with professional Class 1 instruments, marketed for precision environmental and laboratory-grade applications. Their product heritage remains a reference point for calibration and measurement accuracy.
-
Larson Davis (USA) — focused on occupational and environmental instruments, with recent product iterations tailored for workplace health professionals. Their Spartan and SoundExpert series reinforce position in regulated occupational markets.
-
HBK (Germany) — combining product engineering with app-enabled workflows, positioning instruments as integrated system components in test-and-measurement portfolios.
-
Quest Technologies/3M, TSI, and others (USA) — differentiated by modular systems and wireless occupational solutions, expanding platforms that integrate into broader industrial hygiene toolkits.
-
European and Asia-Pacific specialists (Norsonic, Rion, Casella, NTI Audio, Svantek, Cirrus Research, and others) — competing on regional service, specialized features (FFT, multi-channel, vibration cross-analysis), and targeted compliance solutions.
Recent product activity underscores market direction: TSI’s 2025 release of a Class 2 module for its OmniTrak™ platform expands wireless workplace noise measurement and reporting capabilities; Larson Davis continues to enhance its Spartan series for occupational health use; and Rion’s introduction of a Class 2 model with FFT support demonstrates demand for advanced analysis features even in lower-tier instruments. These moves reflect a two-track market: precision, certified Class 1 systems for regulatory and research use, and flexible, connected Class 2 modules for field occupational and facility monitoring. Both tracks present differentiated revenue and service expansion opportunities.
Regulatory and cost dynamics shaping 2026 decisions
-
Standards and compliance: The IEC 61672-1 stability window through 2029 and reaffirmations of ANSI/ASA S1.4 reduce near-term standards uncertainty but raise the bar for documented calibration and verification processes in buyer procurement specifications.
-
Workplace enforcement: OSHA’s referencing of ANSI specifications and NIOSH’s emphasis on accessible measurement (including app-based tools) are fueling demand for instruments that can demonstrably support hearing-loss prevention programs.
-
Manufacturing and calibration costs: Labor-intensive manufacturing and calibration for professional Class 1 meters underpin higher price points and longer product life cycles. This creates both margin opportunities for premium vendors and cost-pressure risks for mass-market suppliers.
What the PW Consulting report contains — operationally usable content
PW Consulting’s full report goes beyond high-level narrative. It includes:
-
A decade-plus historical dataset and scenario-modeled forecasts to 2032 with sensitivity analyses by demand drivers and regulatory scenarios.
-
Price and margin ladders across product tiers and use cases, with calibration and service-cost modeling that illuminates aftermarket revenue potential.
-
Provider benchmarking: capability matrices, certification coverage, distribution footprints, and an assessment of product roadmaps for the leading vendors.
-
Regulatory matrix and compliance playbook: practical checklists for procurement, audit preparation, and product certification timing tied to major standards and enforcement pathways.
-
Commercial playbooks and go-to-market options: channel strategies, partnerships with occupational-health service providers, and product bundling templates for SaaS-enabled workflows.
-
Investment heatmaps and M&A playbooks highlighting where scale, tech differentiation, and service networks converge to create acquisition value.
Practical recommendations for executives in 2026
-
Prioritize certified compliance in product lines: ensure key SKUs meet the necessary IEC/ANSI requirements and that calibration processes are auditable for corporate and public-sector buyers.
-
Invest selectively in software and connectivity: cloud data management, automated reporting for compliance, and device fleet monitoring materially increase customer stickiness and recurring revenues.
-
Rebalance product portfolio across precision and modular tiers: maintain premium Class 1 capabilities while accelerating lower-cost, connected modules for occupational customers who prioritize ease-of-use and fleet-level insights.
-
Optimize manufacturing and calibration supply chains: evaluate regional calibration hubs and partnerships to reduce lead times and cost exposure from labor-intensive workflows.
-
Build or buy analytical capabilities: FFT, multi-channel, and vibration-coupled analytics are differentiators for environmental and R&D buyers; consider partnerships or acquisitions to fast-track feature sets.
-
Use market concentration to shape competitive tactics: incumbents should defend premium channels and service contracts; challengers should exploit niche verticals and rapid deployment solutions.
-
Align commercial contracts with lifecycle services: extend warranty and calibration packages to capture post-sale revenue and improve customer retention.
Conclusion — the strategic value of timely intelligence
For corporate strategists, product leaders, and investment teams preparing 2026 plans, the principal value of this research is its synthesis of regulatory, technological, and commercial dynamics into a forward-looking, actionable framework. The market’s projected expansion through 2032, combined with steady CAGR dynamics and a concentrated competitive field, creates clear windows for differentiated plays in product engineering, service design, and M&A.
PW Consulting’s full study contains the granular segmentation, pricing ladders, and region-and-application breakdowns that operational teams need to build precise investment models and go-to-market plans. To examine the detailed splits, vendor benchmarking tables, and downloadable datasets that underpin the strategic recommendations summarized here, please access the full report on our website — the proprietary data will enable your team to convert insight into 2026 action plans with confidence.
For detailed analysis of this topic, please visit the official page: Sound Level Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com