

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Exoskeleton Robots Market to Reach USD 363M by 2032 at 17.15% CAGR

Exoskeleton Robots Market: Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present an executive preview of our new Exoskeleton Robots Market study — a practitioner-focused synthesis designed to convert the market’s accelerating momentum into concrete boardroom decisions in 2026. This is not a catalogue of figures; it is a strategic briefing that blends verified market trajectory, regulatory inflection points, supplier positioning and actionable playbooks. The objective: equip executives with the situational intelligence needed to prioritize investments, structure pilots, and de-risk commercialization across healthcare, industrial, defence and emerging consumer use cases.
Exoskeleton Robots Market
Market trajectory: growth, scale and strategic inflection
The exoskeleton market is no longer speculative. After consistent expansion through the early 2020s, total industry revenues have accelerated and are projected to continue on a robust upward path. Using 2025 as the base year, our consolidated market model shows sustained double‑digit growth into the early 2030s at a compound annual growth rate of approximately 17.15%. This translates into a near‑term imperative: 2026 is the year to move from experimentation to structured deployment if organizations want to capture first‑mover advantage in procurement, clinical evidence generation, or industrial scale‑up.
Exoskeleton Robots Market
Three strategic consequences flow from this trajectory. First, product and service economics will shift from unit sales to lifecycle value — warranty, maintenance, training and data services will be material contributors to margin. Second, buyers will demand validated outcomes (safety, productivity or clinical efficacy) rather than vendor promises. Third, regulatory and reimbursement milestones will be the primary accelerants or gates for enterprise adoption; companies that align product development and commercialization to these milestones will outpace competitors.
Exoskeleton Robots Market
Why this study matters in 2026
- Actionable regulation intelligence: Recent rule‑setting has changed the compliance landscape. Testing standards for commercial and enterprise robots have been elevated in the U.S. regulatory ecosystem and internationally relevant medical device rules have been updated for powered wearable systems. Executives need a compliance roadmap, not a checklist.
- Reimbursement as a force multiplier: Early listings under public reimbursement pathways are proving that exoskeletons can cross the procurement chasm — but successful claims and programmatic adoption require documented clinical protocols and cost‑effectiveness evidence. Our analysis shows how early adopters unlock procurement cycles by sequencing clinical trials and payer engagement.
- Supply chain and runtime economics: Battery chemistry and component availability remain the gating constraints for operational runtime and unit economics. Integration strategies with battery and power management partners are as strategic as product features in determining market acceptance.
- Fragmented but consolidating supplier base: Market concentration remains modest, leaving space for both focused specialists and broad systems integrators. That creates a window for partnerships, vertical integration and targeted M&A.
What the report delivers — practical content for dealmakers and operators
Our study was designed to be implemented. Highlights of the operational content include:
- Proven market sizing and forecast methodology, with sensitivity scenarios for technology adoption, regulatory timing and reimbursement uptake.
- Decision matrices and procurement playbooks for hospital systems, industrial buyers and defence organizations (including pilot design templates, KPIs and go/no‑go triggers).
- TCO and ROI models that incorporate capital cost, training, maintenance, consumables and productivity gains; templates are pre‑configured for enterprise CFO stress‑testing.
- Regulatory compliance playbook mapping global pathways, recognized consensus standards and test protocols for both safety and therapeutic claims.
- Reimbursement readiness kits featuring clinical evidence roadmaps, payer engagement timelines, and coding/coverage strategies.
- IP and supplier due‑diligence guides, including manufacturing scale assessments, component risk checklists and partner scorecards.
- Human factors evaluation toolkit: protocols for ergonomic validation, user acceptance testing and change management for frontline workforces.
- M&A and commercial partnership screening: target profiles, valuation heuristics and integration risk matrices aligned to strategic objectives.
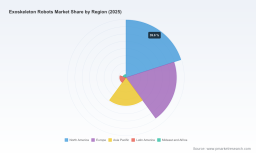
Note: In keeping with our “preview” approach, this executive article highlights the strategic insights and frameworks. Detailed sub‑segment breakouts, region‑level demand curves and competitor revenue tables are intentionally reserved for the full report and its downloadable datasets.
Competitive landscape — patterns that determine winners
The supplier universe can be understood through three archetypes that appear repeatedly across competitive assessments:
- Specialist clinical innovators: Vendors focused on rehabilitation and neurological therapy are differentiating through clinical evidence, hospital partnerships and device classifications. Clinical trial positioning and payer evidence generation are their primary assets.
- Industrial ergonomics and heavy‑duty integrators: Firms emphasizing tools for lifting, overhead work and load handling compete on durability, integration with workflows and total cost of ownership. These players are forming alliances with construction, manufacturing and logistics OEMs.
- Consumer and niche mobility entrants: Emerging teams target outdoor, sport or personal mobility use cases with emphasis on affordability, certification to consumer performance standards and novel powerform factors.
Recent market activity corroborates this pattern: industrial suppliers have released next‑generation arm and shoulder systems certified for occupational use; clinical players are initiating trials to secure reimbursement; consumer‑grade systems debuted at major technology shows; and one notable regional player completed a public offering to fund global expansion. These developments reflect an industry that is moving from lab to regulated, reimbursed and commercialized offerings.
From a concentration perspective, the market shows moderate fragmentation: the three largest players capture less than a third of market revenues and the five largest account for under forty percent. That dynamic creates substantial opportunity for niche specialists to scale via partnerships or for larger industrial and medical device incumbents to accelerate capability via M&A.
Selected supplier behaviors to monitor (strategic signals)
- Integration of embedded AI and sensors to translate device usage into measurable outcomes and services revenue.
- Moves to obtain occupational safety certifications and medical device clearances in parallel — a dual‑path regulatory strategy that de‑risks both industrial and clinical endpoints.
- Commercialization through channel partners (medical distributors, construction OEMs and defense contractors) rather than direct sales — accelerating reach while managing installation and service costs.
- Capital markets activity and strategic fundraising to scale manufacturing and global market entries; public listings are enabling faster geographic expansion for some vendors.
Strategic recommendations for executives acting in 2026
- Pilot with intention: Run framed pilot programs with predefined success metrics (safety, utilization, productivity/clinical endpoints) and clear transfer‑to‑scale plans. Avoid indefinite “evaluation” pilots that collect data but fail to convert to procurement.
- Align compliance, clinical and procurement timelines: Map product clearances and occupational certifications to procurement windows so that buyer committees can sign off when compliance milestones are hit.
- Design aftermarket and services now: Warranty, remote monitoring, consumables and training create recurring margin pools — include them in procurement RFPs and partner contracts.
- Mitigate power and component constraints: Lock strategic supply agreements for battery modules and power electronics; evaluate hybrid energy solutions and rapid‑swap designs to maintain uptime.
- Invest in outcome measurement: Standardize data collection from the outset. Buyers and payers will require rigorous evidence of benefit; vendors who can deliver validated real‑world evidence will command premium positioning.
- Prepare for consolidation: Build an M&A watchlist and partnership scorecard. The competitive landscape will consolidate around firms that combine clinical credibility, scale manufacturing and field service networks.
Conclusion — what to do next
2026 is the pivot year: the market’s macro trajectory drives urgency, and regulatory plus reimbursement developments create a narrow window where disciplined programs can capture structural advantage. PW Consulting’s Exoskeleton Robots Market study provides the operational playbooks, validated financial models and regulatory roadmaps required to move from pilot to programmatic adoption. For leadership teams preparing investment cases, procurement roadmaps, or M&A decisions, the full report delivers the granular datasets, segmented forecasts and competitive intelligence you need to execute with confidence.
Access the full study for the complete segmented forecasts, regional demand curves, competitor revenue profiles and downloadable ROI models — all designed to convert the market’s momentum into measurable enterprise outcomes.
For detailed analysis of this topic, please visit the official page: Exoskeleton Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com