

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Nuclear Valves Market to Reach USD 3,246.8 Million by 2032 at 6.1% CAGR — PW Consulting

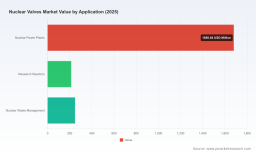
Nuclear Valves Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our new Nuclear Valves Market study. Anchored on a 2025 base and projecting through 2032, the analysis synthesizes historical trends (2020–2025), a rigorous forecast (2026–2032), and proprietary competitive intelligence to inform capital allocation, sourcing, and technology decisions in 2026. At the macro level, the market is positioned for steady expansion: our model shows a compound annual growth rate of 6.1% over the forecast window, with total industry revenues rising materially from the mid-2020s baseline into the early 2030s. This preview outlines why that trajectory matters, how established and emerging suppliers are responding, and what pragmatic actions buyers, suppliers, and investors should consider now.
Nuclear Valves Market
Why this study matters for 2026 strategies
- Policy and programme timing — 2026 is a decision inflection point for many utilities and developers: choices made this year about valve qualification strategies, long-term service agreements, and supplier shortlists will determine readiness and cost for both traditional large reactors and the accelerating wave of SMR projects.
- Procurement and certification lead times — nuclear-grade valves require lengthy design control, stamping, and qualification. Our report quantifies the economic impact of those lead times on project cash flow and schedule risk, turning regulatory compliance from a checklist item into a strategic procurement lever.
- Aftermarket economics — as the installed base ages, lifecycle services (testing, diagnostics, refurbishment) represent a growing, higher-margin portion of supplier revenue. The study models aftermarket trajectories and identifies where service-led business models will outcompete pure OEM supply.
What the PW Consulting report delivers (practical, actionable content)
- Robust macro model covering historical performance (2020–2025) and a forecast (2026–2032) that incorporates scenario sensitivity to project pipeline, nuclear build-rates, and SMR rollouts.
- Decision-grade frameworks for procurement leaders: supplier shortlisting criteria, qualification roadmaps, and RFP language templates that reduce schedule and compliance risk.
- Supply-side diagnostics: capacity mapping, certification bottlenecks, materials and machining constraints, and contingency playbooks for key single-source nodes.
- Commercial guidance for OEMs and service providers: go-to-market plays for winning long-term utility partnerships, aftermarket monetization strategies, and prioritization of R&D investments (actuation, diagnostics, digital twin integration).
- Vendor benchmarking and deal playbooks: comparative profiles, capability matrices and negotiation levers tailored for both new-build and plant-life-extension contexts (note: the full vendor scorecards and numerical rankings are available in the full report).
- Risk matrices and mitigation strategies across regulatory, supply-chain, and geopolitical vectors to support board-level scenario planning.
Key market signals — data-driven perspective
From a top-line standpoint, the nuclear valves industry is growing at a mid-single-digit compounded pace. Our baseline indicates meaningful expansion from the 2025 base through 2032, reflecting a combined effect of new-build programs, SMR commercialization, life-extension projects, and increased spending on waste management infrastructure. Importantly, the market exhibits moderate concentration: a handful of established suppliers control a meaningful share of addressable demand, but there remains room for specialized players that can meet stringent certification and service requirements.
Nuclear Valves Market
For 2026 decision-makers, the implication is two-fold: buyers should lock in supply-chain resilience and long-term service arrangements now; suppliers should prioritize certification, strategic alliances, and targeted capacity investments to capture the higher-value segments of the evolving market.
Nuclear Valves Market
Competitive landscape — capabilities and strategic moves to watch
Our competitive analysis focuses on six firms that collectively exemplify the industry’s strategic dynamics: long-tenured OEMs with deep nuclear pedigree, global players expanding service portfolios, and regionally strong manufacturers pursuing export qualification.
- Crane Nuclear (Kennesaw, Georgia) — A legacy supplier with decades of performance in commercial plants. Strengths: long-standing ASME credentials, deep experience across Class 1–3 systems, and an installed-base service footprint. Strategic posture: maintaining reliability and aftermarket capture in established fleets.
- Neway Valve (Suzhou) — Represents the increasingly capable Asian supplier set that couples cost-competitive manufacturing with full nuclear-grade certifications. Strengths: wide product range and licenses aligned to multiple reactor designs. Strategic posture: export expansion through qualification to international codes and reactor programs.
- Trillium Flow Technologies (UK) — An engineered-valve specialist with emphasis on actuated systems and safety relief hardware. Strengths: ASME Section III stamps at multiple sites and a product set tailored to both new-build and OEM integration. Strategic posture: deepen long-term supply alliances with utilities (and leverage recent offtake-type deals).
- Velan Inc. (Montreal) — A market leader with early ASME 'N' credentials and a growing SMR services footprint. Recent contract wins on SMR programs underline the commercial value of being first-mover in qualification for next-gen reactors. Strategic posture: convert qualification advantage into lifecycle service franchises.
- Flowserve Corporation (Irving, Texas) — A diversified global supplier that bundles pumps, valves, and seals. Strengths: integrated hardware-software offerings and long-term utility relationships. Strategic posture: leverage cross-product platforms to win larger systems contracts and retrofit opportunities.
- Framatome (Paris) — A systems integrator with code expertise across ASME and RCC-M; recent M&A activity demonstrates a strategic intent to consolidate specialty valve capabilities and accelerate product breadth for PWR/BWR and advanced concepts.
Notable recent industry developments that shape 2026 strategies include long-term supply alliances, targeted M&A to consolidate engineered-valve capabilities, and SMR-related contract awards that favor suppliers already qualified to emerging reactor designs. These moves underscore two structural realities: certification equivalence is a de facto market access requirement; and service agreements are becoming as important as one-off equipment sales.
Regulatory and certification dynamics — entry barriers and opportunities
Certification and stamping regimes (ASME 'N'/'NPT', ASME Section III, and country-specific civil-nuclear grades) remain the dominant non-price entry barriers. Several suppliers highlighted in the report hold active stamps or national grade authorizations, and those credentials materially reduce time-to-contract on major projects. For 2026 planning, investors and procurement leads should treat certification programs as strategic investments with multi-year payback horizons—this is not a short-cycle CAPEX decision.
Risks, scenarios, and mitigation playbook
- Certification bottlenecks — Risk: delayed approvals for new production sites. Mitigation: staggered supplier qualification, dual-sourcing critical SKUs, and early engagement with certifying bodies.
- Single-source dependencies — Risk: concentrated supply of key forgings or specialty materials. Mitigation: develop secondary suppliers, leverage strategic inventory pools, and invest in joint-qualification exercises.
- Project timing mismatch — Risk: decoupling between valve deliveries and reactor critical-path milestones. Mitigation: align commercial terms to milestone-based deliverables and penalties, and plan for interim containment spares.
- Geopolitical and trade dynamics — Risk: export controls or policy shifts affecting cross-border supply. Mitigation: local content strategies, regional manufacturing partnerships, and contract clauses to manage regulatory-change exposure.
Actionable recommendations for 2026
- For utilities and EPCs: convert vendor shortlists into multi-year service alliances now, with contractual options for capacity reservation and qualification transfer protocols.
- For OEMs and valve manufacturers: prioritize certification investments tied to identified reactor platforms and target aftermarket service contracts to secure higher-margin recurring revenue.
- For investors and private equity: focus due diligence on suppliers with validated certifications and demonstrable aftermarket capabilities; stress-test acquisition targets against certification and capacity timelines.
- For suppliers in growth markets: pursue selective partnerships or acquisitions to bridge certification gaps quickly rather than attempting sole-source in-house qualification under time pressure.
Next steps — where the full intelligence sits
This preview is designed to establish the strategic frame for 2026 decisions: it shows the market’s growth trajectory, the certification-driven barriers to entry, the competitive moves shaping supplier advantage, and the concrete procurement and risk mitigations to prioritize. The full PW Consulting report contains the granular quantitative segmentation (region, valve type, and application), vendor scorecards with capability ratings, downloadable financial models, and full scenario outputs that underpin the headline 6.1% CAGR forecast. To access the full dataset, vendor rankings, and bespoke briefing options for executive teams, please visit PW Consulting’s Nuclear Valves Market portal or contact our advisory desk for a tailored executive workshop.
In an industry where certification, timing, and service-readiness determine value capture, 2026 is the year to convert market intelligence into durable commercial advantage. Our study gives you the roadmap—and the operational tools—to do just that.
For detailed analysis of this topic, please visit the official page: Nuclear Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com