

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Connectors Market USD 7.0B in 2025, to USD 11.17B by 2032 (6.97% CAGR)

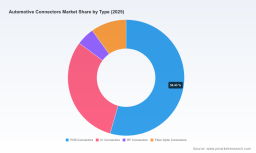
Automotive Connectors Market: Strategic Imperatives for 2026 — A PW Consulting Preview
The automotive connectors market stands at a strategic inflection point. After a steady recovery through the early 2020s, total industry revenue expanded from USD 4.98 Billion in 2020 to USD 7.00 Billion in our base year of 2025. Our outlook projects continued momentum across 2026–2032, with the market reaching approximately USD 11.17 Billion by 2032 at a compound annual growth rate (CAGR) of 6.97% (USD, revenue unit: Billion). For leaders planning 2026 strategies, this report synthesizes where value will be created, who is positioned to capture it, and which near-term decisions will most materially affect competitive positioning.
Automotive Connectors Market
Why this research matters for 2026 decision cycles
2026 is the first full planning year after several structural shifts converged: accelerated EV adoption, tightening standards for high-voltage charging, rapid embedding of domain controllers and automotive Ethernet, and concentrated supply risks for key raw materials. The 2026 budget and capital allocation decisions you make now will determine product roadmaps, supplier relationships, and M&A appetite through the next business cycle. Our Automotive Connectors Market study translates macro growth into operationally relevant choices—where to allocate R&D, how to configure manufacturing footprints, and which partnerships will produce defensible margins.
Automotive Connectors Market
Core findings you can act on
- Growth trajectory and investment window: With the market expanding at ~6.97% CAGR over the forecast horizon, there is sustained room for investment in higher-value connectors (high-voltage, high-speed data, ruggedized interconnects) and integrated harness systems. This growth is not uniform; it is driven by technology and regulatory catalysts rather than uniform vehicle volume expansion.
- Market structure and concentration: The market exhibits moderate concentration: the top three players control a clear majority of industry revenue while the top five widen that dominance further. This dynamic favors scale players for high-volume, capital-intensive segments, but specialist suppliers and regionally focused companies retain pockets of technical differentiation.
- Standards and regulatory inflection points: The publication of SAE J3400/2 and related adapter guidance, along with technical guidance such as the ZVEI validation guideline for low-voltage connectors, are reshaping product specifications and qualification cycles. Compliance and standards engagement have become competitive levers rather than mere risk controls.
- Supply chain and materials risk: High dependence on limited-source plastic resins and precious metals elevates geopolitical and licensing risk. Contract strategies for 2026 must blend long-term supplier commitments with diversified secondary sources and hedging where feasible.
What the report contains — practical, operational insight
This study is designed for decision-makers who need more than forecasts: it is a playbook for execution. Key deliverables include:
Automotive Connectors Market
- Detailed market sizing and trend analysis (historical 2020–2025; base year 2025; forecast 2026–2032).
- Technology and product roadmaps identifying where technical differentiation (e.g., high-voltage eHV systems, 25A+ power connectors, automotive Ethernet, fiber/RF solutions) will produce margin uplift.
- Commercial playbooks: pricing levers, channel strategies for OE vs. aftermarket, and go-to-market frameworks for tiered supplier models.
- Supply chain risk matrix and mitigation options, including dual-sourcing playbooks, nearshoring scenarios, and inventory strategies tied to materials risk profiles.
- Competitive benchmarking with vendor scorecards (technology, manufacturing footprint, program wins, ADAS/EV alignment) and a prioritized M&A target list based on capability gaps.
- Regulatory and standards tracker with scenario-based impacts on product lifecycles and certification costs.
- Case studies that map design-to-manufacture timelines and cost-to-serve analytics for representative product families.
- Decision-ready dashboards and scenario models to stress-test capital investments, shift in vehicle architectures, and supplier consolidation outcomes.
Competitive landscape — who matters and why
The market combines global systems integrators and specialized regional manufacturers. Large, diversified players command program access and scale advantages; niche players and component specialists provide innovation in electrical contacts, compact high-density connectors, and application-specific certifications.
- TE Connectivity (Schaffhausen): A scale leader with a broad portfolio across low-voltage signal and power connectivity. TE’s public disclosures also highlight exposure to concentrated raw material supply chains—an element buyers and procurement teams must internalize when negotiating long-term programs.
- Amphenol Corporation (Wallingford, CT): Known for ruggedized interconnects and systems for EVs and sensors; strong in environmental and mechanical protection features valued in off-highway and commercial vehicle segments.
- Molex (Koch Industries, Lisle, IL): A primary player in eHV high-voltage systems; its high-current distribution solutions are central to EV platform engineering and auxiliary power management.
- JAE Electronics (Tokyo): Specialist in compact, high-density connectors and emerging high-power/up-to-25A solutions. Recent product launches underscore a push into automotive Ethernet and high-power segments — watch for program qualification wins in 2026 procurement cycles.
- Hirose Electric, Sumitomo Electric, Yazaki: These firms combine product breadth with close OEM relationships in key vehicle markets; they accelerate time-to-vehicle integration for infotainment, wiring harness, and high-voltage subsystems.
- Regional and niche suppliers (e.g., KSTerminals, Greenconn, Sunkye, Rosenberger): Offer specialization in aftermarket, IATF-certified manufacturing, MIL-spec variants, and RF/high-speed communications — essential partners when OEMs require tailored or localized solutions.
- Aptiv: Integrates connectors into broader wiring and electronic architecture platforms, creating higher-value systems solutions that move the value chain upstream.
Recent developments shaping 2026 strategies
- SAE’s publication of J3400/2 (May 2025) and related adapter guidance shifts the technical bar for charging hardware, enabling designs that support higher voltage and faster charge rates. This creates new product qualification requirements and a window for suppliers able to accelerate certification timelines.
- CharIN and SAE alignment on adapter standards reduces interoperability friction but increases the cost and complexity of compliance — suppliers must be prepared for longer validation cycles and upgraded testing suites.
- Product launches from leading connector suppliers — including high-power 25A-class connectors and 1000BASE-T1-capable Ethernet products — signal OEM demand moving from discrete components to integrated, software-aware interconnect solutions.
- Regulatory and procurement actions, such as DOT inquiries into connector performance and national-level trade dynamics, will affect supplier selection and contract structuring for North American programs in 2026.
Strategic implications and recommended actions for 2026
Translate market growth and technical developments into a defensible plan with the following priority moves:
- Prioritize standards-aligned R&D: Allocate a portion of R&D to ensure product families meet J3400-class and automotive Ethernet requirements. Early engagement with standards bodies and conformance testing labs reduces time-to-program approval.
- Build supply resilience: Implement dual-sourcing for critical resins and contact metals, pursue strategic inventory agreements, and qualify geographically diverse secondary suppliers to mitigate geopolitical exposures highlighted by major incumbents’ disclosures.
- Targeted M&A and partnerships: Acquire or partner with firms that add high-voltage capability, in-cabin high-density connectors, or automotive Ethernet expertise to rapidly fill portfolio gaps without long internal development cycles.
- Commercial differentiation: Move beyond price competition; offer systems-level warranties, integrated harness solutions, and digital product passports that shorten OEM validation timelines and capture aftermarket value.
- Operational footprint optimization: Reassess manufacturing placement to balance proximity to OEMs with risk diversification. Nearshoring or regional assembly hubs can be decisive for 2026 program wins.
- Engage in standards and ecosystem coalitions: Participate in SAE, CharIN, and regional bodies to help shape implementation specifics — being in the room influences technical choices and early adopter advantages.
How PW Consulting supports 2026 execution
Our Automotive Connectors Market study combines quantitative forecasts with decision-ready deliverables: vendor scorecards, program qualification timelines, supplier risk heatmaps, and an M&A screening engine calibrated to capture synergies in power and data connector domains. We also provide a regulatory impact simulator that models certification cost, time-to-market delta, and expected margin pressure under alternative compliance scenarios.
For teams preparing procurement plans, product roadmaps, or M&A pipelines for 2026, the research provides the evidence base and playbooks needed to move from analysis to action while preserving upside in a market expected to expand materially through 2032.
Next steps
This preview highlights strategic themes and operational levers. The full PW Consulting report contains the granular segmentation, regional and application breakdowns, modelled scenarios, and vendor-level financial and technical benchmarking that underpin procurement decisions and R&D prioritization for 2026. To access the complete dataset, detailed segment-level forecasts, and the executable playbooks, please refer to our full report.
For detailed analysis of this topic, please visit the official page: Automotive Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com