

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cryocoolers Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Cryocoolers Market 2026: Strategic Insights for Executive Decision-Making
Executive summary
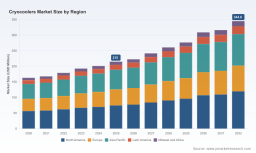
As organizations across defense, space, medical imaging, quantum technologies, and industrial gas systems plan capital allocation and product roadmaps for 2026, cryocoolers are transitioning from niche enabling components to strategic system-level differentiators. PW Consulting’s latest study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market dynamics, regulatory shifts, supplier positioning, and technology trajectories into an operational playbook for leadership teams. The global cryocoolers market has expanded materially from 2020 to 2025 and—growing at a compound annual growth rate (CAGR) of 6.98%—is forecast to continue through 2032, reflecting accelerating demand from quantum, space, and defense programs.
Cryocoolers Market
Why this report matters to 2026 decision-makers
- Timing: 2026 is a pivotal year for procurement, certification, and supplier consolidation decisions. Several large programs (defense night-vision upgrades, satellite constellations, and quantum commercialization pilots) require procurement commitments or design freezes this year.
- Risk management: New export-controls and testing requirements introduced between 2024–2026 increase compliance complexity and supplier due-diligence burdens for global programs.
- Investment focus: R&D and capex choices made in 2026 will determine who captures the higher-value system integrations emerging by the early 2030s—particularly for long-duration space cryogenic storage and low-vibration quantum cryocoolers.
- Supplier strategy: The market remains fragmented (CR3 ≈ 24.6%; CR5 ≈ 26.2%), which creates opportunities for both large integrators and nimble specialists to scale through targeted partnerships or M&A. Our research maps the commercial levers to exploit this fragmentation.
Market trajectory — a concise data-driven view
PW Consulting’s topline metrics provide a clear frame for strategic planning: the global cryocoolers market increased steadily from 2020 into 2025, and with the base year set at 2025 our forecast extends through 2032 under a mid-cycle scenario (CAGR 6.98%). This trajectory reflects a convergence of drivers—expanded satellite and ISR payloads, quantum-computing deployments, and broader industrial and energy uses—that are reshaping demand profiles and unit economics. While we disclose the aggregate market path in this preview, detailed segment and regional splits are intentionally withheld here to preserve the report’s role as the definitive commercial reference.
Cryocoolers Market
What the full PW Consulting study contains (practical, actionable content)
- Market sizing and forecasting model (base year 2025, historical coverage 2020–2025, forecast 2026–2032) with downloadable scenario files and sensitivity levers for price, adoption, and substitution.
- Demand-driver deep dives: satellite payload schedules, defense procurement cycles, quantum and superconducting use-cases, medical imaging replacement timelines, and industrial gas/liquefaction projects.
- Regulatory & export-control matrix: program-level compliance impacts, national control lists, and practical steps for dual-use supply chains (updated to reflect 2024–2026 rule changes).
- Supplier benchmarking toolkit: capability maps, product-readiness matrices (TRL mapping), and procurement scorecards to accelerate vendor selection and risk mitigation.
- Commercial playbooks: go-to-market options by buyer archetype (prime integrator, OEM, national lab, commercial quantum provider) including pricing and service models that preserve margin while enabling adoption.
- M&A and partnership blueprint: prioritized target lists, valuation comparables, and integration checklists for acquiring complementary cryocooler technologies or manufacturing capacity.
- R&D and product roadmap templates: low-vibration, high-uptime, and low-mass architectures; cooling-power tradeoffs; and quick-win design modifications to shorten qualification cycles.
- Supply-chain resilience planning: critical-buoy component lists, alternate sourcing strategies, inventory sizing guidelines, and nearshoring scenario analysis keyed to regulatory constraints.
- Executive dashboards and decision-support worksheets: cash-flow impacts, TCO calculators, and scenario-based NPV comparisons for strategic investment options.
Competitive landscape — who matters and why
The cryocooler ecosystem mixes long-established industrial players, defense primes, and specialized innovators. Rather than a winner-takes-all market, the current structure rewards technology depth, systems-integration capability, and supply-chain resilience.
Cryocoolers Market
- Sumitomo Heavy Industries (Tokyo) — broad portfolio strength across Gifford-McMahon and pulse-tube families for space, medical imaging, and defense. Their strategy emphasizes high-capacity, lower-maintenance designs that play well into long-duration missions.
- Northrop Grumman (Washington, DC) — leverages systems-integration expertise to embed custom Stirling and pulse-tube units in satellite and sensor payloads. Their competitive edge is integration and mission assurance at prime-contractor scale.
- AMETEK / Sunpower (Waltham) — focuses on Stirling technology optimized for low vibration and maintenance-free operation, attractive for aerospace and sensitive instrumentation.
- Chart Industries (Boulder) — industrial cryogenics specialist; its strength is in scale for gas liquefaction and energy applications where system-level cryogenic management is the differentiator.
- Bluefors (Helsinki) & Cryomech (Syracuse) — pulse-tube leaders targeting quantum and superconducting detector markets with compact, high-performance designs; high-growth adjacency as quantum commercialization matures.
- RICOR, AIM Infrarot-Module, RIX Industries, Stirling Cryogenics — niche specialists in miniature Stirling and premium infrared detector coolers; critical suppliers for defense IR and scientific instrumentation.
- Thales, L3Harris — defense and aerospace primes integrating cryocoolers into night-vision, ISR, and space systems. Their primary moat is system-level certification and secured program flows.
- Air Liquide, Advanced Research Systems, Lake Shore, Superconductor Technologies — combine component-level expertise with downstream system services, especially for research and industrial customers.
Collectively, the market’s low concentration metrics indicate opportunity: large primes can differentiate through integration and service offerings, while specialists can scale by carving application-led niches or partnering with OEM integrators.
Regulatory and technology dynamics to watch in 2026
- Export controls: Recent national controls (e.g., updates in 2024–2026) have added complexity to cross-border supply chains and technology transfers. Buyers and sellers must incorporate export classification and licensing timelines into procurement gates.
- Technology readiness requirements: Programs such as NASA’s CACHE initiative are pushing high-capacity cryocooler TRL thresholds for space cryogenic storage—this raises the bar for vendors seeking inclusion in long-duration mission bids.
- Conference and knowledge flows: Industry forums (notably the June 2026 International Cryocooler Conference) will accelerate transparency on performance benchmarks and integration learnings—attendance and targeted sponsorships are high-ROI activities for market entrants.
- Product innovation: Recent product launches signal performance inflection points—compact two-stage pulse-tube systems for superconducting detectors and whisper-quiet, higher-capacity single-stage units for space and defense. These design advances change system architecture decisions and lifecycle cost profiles.
Strategic moves for executives in 2026 (prioritized)
- Immediate (0–6 months) : Incorporate export-control gating into all procurement and partnership contracts; run a rapid supplier compliance audit to identify potential license needs and contingency suppliers.
- Near-term (6–12 months) : Adopt the PW scenario model to test procurement vs. in-house development trade-offs for high-volume programs; prioritize vendor scorecards that include TRL, spares lead time, and proven integration experience.
- Medium-term (12–24 months) : Form strategic partnerships with pulse-tube and Stirling specialists to co-develop low-vibration and high-life-cycle products tailored to your system requirements—focus on IP-sharing arrangements that preserve optionality.
- Portfolio strategy : For investors and corporate development teams, target tuck-ins that add cryocooler miniaturization or thermal-storage capability; valuation discipline should factor in long qualification cycles and export uncertainty.
- Operational resilience : Rebalance inventories of critical components, invest in dual-sourcing for high-vulnerability subassemblies, and evaluate nearshoring options where regulatory risks are material.
- Talent & R&D : Hire systems engineers with cryogenics integration experience and seed focused R&D on vibration mitigation and mean-time-between-failure (MTBF) improvements—small performance gains translate to outsized system-level advantages.
How PW Consulting’s deliverables support execution
- Customizable financial models and procurement templates to compress vendor selection timelines from months to weeks.
- Operational checklists for export compliance and supplier audits aligned to the latest 2024–2026 regulatory changes.
- M&A diligence packs and integration plans that reflect cryocooler-specific certification and qualification timelines.
- Workshops and executive briefings to cascade findings into program planning and R&D prioritization.
Closing — a trailer, not the full film
This briefing is deliberately selective. It communicates the market’s direction, the regulatory headwinds, the competitive topology, and the practical strategic moves that should be on every executive’s 2026 agenda—while withholding the granular regional, type, and application splits that underpin our proprietary valuation and vendor-ranking models. PW Consulting’s complete Cryocoolers Market report contains those detailed breakdowns, downloadable models, and supplier scorecards essential for transaction-level decisions. For clients preparing procurement specifications, investment memoranda, or program roadmaps in 2026, the full study converts market insight into executable advantage.
To access the full dataset, scenario models, and supplier benchmarking tools, please visit our report page or contact PW Consulting’s team for a tailored executive briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Cryocoolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com