

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Membrane Air Dryers Market Poised for 6.98% CAGR to 2032
By pmarketresearch, 2026-07-09
Membrane Air Dryers Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior strategic adviser and chief industry analyst, I present a concise, practitioner‑focused preview of our full Membrane Air Dryers Market study. This briefing distills the macro trends, competitive dynamics, and high‑value strategic implications that should shape executive choices in 2026. The full report contains the granular segment-level figures, vendor scorecards, and scenario models referenced here; this preview deliberately omits those line‑by‑line data to preserve strategic value and direct stakeholders to the complete intelligence package.
Membrane Air Dryers Market
Market at a glance: scale, trajectory and concentration
Membrane air dryers are a growth market. By our base year (2025) the global market surpassed the billion‑dollar threshold (reported in USD, revenue unit: Million), and the forecast to 2032 is underpinned by a steady compound annual growth rate of 6.98% across the 2026–2032 horizon. Market concentration remains relatively low for a specialized industrial component: the top three vendors account for just over one‑fifth of market share (CR3 ~22.5%) with the top five approaching the high‑20s (CR5 ~27.8%). That competitive profile points to ongoing opportunity for differentiated entrants, regional champions, and consolidation plays.
Membrane Air Dryers Market
Why this study matters to a 2026 strategic agenda
-
Capital allocation and procurement: Procurement teams and plant managers must reconcile compressor system upgrades, point‑of‑use decisions, and replacement cycles with constrained capital budgets. Our study quantifies the projected demand envelope and operational levers that change the total cost of ownership.
Membrane Air Dryers Market -
Product and R&D prioritization: Membrane technology offers distinct trade‑offs—energy neutrality (no rotating components), compactness, and low dew point capability set against purge‑air penalties and filtration sensitivity. The report translates those trade‑offs into R&D and product roadmaps aligned with end‑market needs.
-
M&A, partnerships and aftermarket strategy: Given moderate concentration, carefully targeted acquisitions and channel partnerships unlock immediate scale, service footprints, and IP synergies. The study maps likely consolidation corridors and partner archetypes.
-
Sustainability and regulatory compliance: ISO 8573‑1 moisture classifications, regional emissions and energy mandates, and the emergent corporate net‑zero programs require operators to choose drying solutions that balance performance and lifecycle environmental impact. Our modeling links compliance outcomes to technology choice.
What’s in the full report (operationally actionable)
-
Market sizing and seven‑year forecasts (2026–2032) with scenario sensitivity to energy prices, purge‑air optimization, and tariff escalation.
-
Detailed segmentation by region, product type, and application with time‑series datasets and heat maps for prioritization (note: segment tables are available in the main report only).
-
Competitive benchmarking including capability matrices, route‑to‑market analysis, and near‑term product roadmaps for leading vendors.
-
Supply‑chain risk analysis focused on membrane substrates, housing components, and filtration media; includes tariff stress tests and mitigation options (dual sourcing, relocation economics, and inventory strategies).
-
Commercial playbooks for OEMs and distributors: pricing levers, service bundling, SLAs, and retrofit economics to accelerate aftermarket revenue.
-
Technical annexes covering performance trade‑offs: dew‑point achievement, purge‑air consumption ranges, and pre‑filtration design criteria for hollow‑fiber membranes.
-
Executive decision tools: NPV calculators, capex vs. opex frameworks, and an implementation checklist for plant engineers and procurement leads.
Competitive landscape — who is shaping product and go‑to‑market moves
The market features a mix of large industrial systems suppliers and specialized niche manufacturers. Leading names to watch are:
-
Atlas Copco (Stockholm) — strong push on integrating membrane dryers into IoT and predictive maintenance ecosystems. Their SDM/SMD lines illustrate a strategy of higher‑value, integrated offerings that target energy optimization and compact installation footprints.
-
Parker Hannifin (Cleveland) — combines membrane modules with coalescing and filtration to address industrial cleanliness and longevity. Recent product introductions emphasize sustainability and low emissions as differentiators.
-
SMC Corporation (Tokyo) — positions membrane dryers for precision applications (laser processing, instrument air) where very low dew points without power supply are critical. Their product focus highlights the adjacency to pneumatic subsystem OEMs.
-
Hankison, Pentair, Festo, BEKO, Dri‑Air — each brings distinct strengths: compact industrial designs, high‑performance housings, wear‑free operation, and market specialization (e.g., low‑throughput plastics drying). These players are important partners or acquisition targets depending on your entry strategy.
Recent vendor moves underscore two themes: (1) product innovation that reduces lifecycle cost via smarter controls and lower purge rates, and (2) positioning around sustainability credentials. Notable examples include Parker’s sustainability‑focused product launch (2024), Atlas Copco’s IoT‑ready systems (2024) and later SMD announcements (2026), and Dri‑Air’s stainless‑steel MicroDryer for low‑throughput precision applications (2024).
Market dynamics that will dictate near‑term winners
-
Regulatory and quality standards: ISO 8573‑1 moisture classes govern acceptable performance metrics across industrial applications; vendors that deliver certified, verifiable performance will command premium placements.
-
Operational efficiency: membrane systems are attractive because they avoid moving parts, but they trade off purge air consumption—typical ranges must be engineered into plant air balances (purge consumption commonly falls in the 10–20% band for -40°F targets). Executives must optimize system layout and compressor loading to realize promised gains.
-
Supply‑chain pressure: rising tariffs on raw materials and components have materially increased costs for housings, fittings, and membrane substrates. Procurement organizations need near‑term mitigations (contract hedging, local sourcing) to preserve margin while avoiding service disruptions.
-
Pre‑filtration dependency: hollow‑fiber membranes are sensitive to oil and particulate contamination; effective upstream filtration architecture is a prerequisite—not an option—for sustained membrane performance and warranties.
Strategic implications and recommended priorities for 2026
Executives should treat membrane dryer decisions as system‑level choices that affect compressor sizing, plant air economics, and aftercare revenue streams. Key priorities:
-
Embed purge‑air and pre‑filtration metrics into procurement contracts. Negotiate acceptance tests and performance‑based SLAs tied to dew point and purge consumption.
-
Invest selectively in IoT and predictive maintenance capabilities that convert product upgrades into recurring service revenue. Vendors that provide real‑time monitoring reduce total cost of ownership and increase stickiness.
-
Hedge raw‑material exposure through supplier diversification or nearshoring for critical components. The report’s tariff sensitivity scenarios quantify break‑even points for reshoring vs. continued imports.
-
Pursue targeted M&A or distribution partnerships to accelerate penetration in specialized end markets (laser processing, instrument air, medical breathing air), where membrane advantages are most pronounced.
-
Prioritize lifecycle emissions and energy reporting for corporate sustainability programs—membrane solutions can be positioned as low‑energy, low‑maintenance pathways to compliance when lifecycle data is disclosed.
Five high‑impact questions for executives
-
Have we quantified the plant‑level impact of purge‑air consumption on compressor sizing and electricity spend across our sites?
-
Do our procurement terms include performance‑linked acceptance criteria (dew point, purge, uptime) and penalties for underperformance?
-
Is our supplier portfolio diversified enough to withstand tariff shocks and membrane substrate shortages?
-
Can we convert product upgrades (IoT, predictive alerts) into a defended aftermarket subscription business within 18 months?
-
Which end markets in our portfolio demand the unique benefits of membrane drying (size, no power requirement, low dew points) and how should GTM prioritize them?
Conclusion: The membrane air dryer market is mature in engineering but emergent in commercial structures. Technology differentiation, supply‑chain resilience, and aftermarket models will decide which players scale with the mid‑to‑upper single‑digit market growth projected through 2032. This preview sketches the strategic terrain and immediate imperatives; the full PW Consulting report supplies the proprietary segment datasets, supplier scorecards, and implementation tools your team will need to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: Membrane Air Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Atomic Force Microscope Market — Strategic Preview for 2026 Decisions
Executive overview
As organizations finalize capex, R&D roadmaps, and partnership strategies for 2026, a clear, evidence-based view of the Atomic Force Microscope (AFM) market is a strategic asset. Our PW Consulting market synthesis shows a resilient, mid-single-digit-to-high-single-digit growth profile rooted in accelerating demand across semiconductor metrology, materials science, and bio-nanotechnology. From 2020 through our base year of 2025, the AFM market expanded meaningfully, and our forecast through 2032 anticipates sustained growth at a compound annual growth rate (CAGR) of 7.1%, taking the total market from the mid-hundreds of millions (USD) in 2025 to a substantially larger market by 2032.
Atomic Force Microscope Market
This preview distills the implications of that trajectory for strategic planners — what it means for product roadmaps, manufacturing footprints, channel approaches, and M&A prioritization — while intentionally withholding granular subsegment tables that are included in the full PW Consulting report. Think of this as the trailer: deep enough to orient and provoke action, but designed to drive decision-makers to the full analysis for executable specifics.
Atomic Force Microscope Market
Market trajectory & what it signals for 2026
-
Momentum and scale: The AFM market has shown steady expansion across the historical period (2020–2025) and enters 2026 from a position of strengthened demand. Our modeling projects a steady climb through the forecast window (2026–2032), with the market approaching nearly double-digit relative gains in critical years driven by sequential advances in semiconductor packaging, advanced materials, and integrated life-science workflows.
Atomic Force Microscope Market -
Concentration and competitive dynamics: The market exhibits moderate-to-high concentration among leading players; our concentration metrics indicate that the top three firms account for a dominant share of the market, with the top five firms together capturing the bulk of global revenues. This structure has three practical consequences for 2026 planning: pricing power at the top, attractive niches for focused challengers, and an active M&A backdrop as companies seek capability-based consolidation.
-
Technology-driven upsell: Recent advances in probe fabrication, multimodal AFM modalities, and Raman-coupled systems are converting single-purpose AFMs into platform assets. These technology developments not only expand addressable applications but also increase average selling price (ASP) and lifecycle spend via consumables and software — a critical consideration for vendors and buyers negotiating multi-year support contracts in 2026.
Five strategic implications for 2026 decision-makers
-
Prioritize modular, upgradeable platforms. With rapid modality innovation (e.g., multimodal mechanical characterization and Raman-AFM integrations), buyers and vendors who emphasize modularity capture lifecycle revenue and reduce obsolescence risk. R&D and procurement teams should require upgrade paths and software-forward roadmaps in procurement RFPs.
-
Build resilience into supply chains. Non-tariff barriers, export-control frictions, and logistics delays are causing months-long disruptions in some corridors. Suppliers should diversify sourcing for critical components (probes, scanners, control electronics) and map regulatory timelines into product launch schedules; buyers should factor extended lead times into project plans for 2026.
-
Capture adjacent value in services and consumables. The market’s trajectory supports shifting commercial models from one-time instrument sales to subscription-like service bundles (maintenance, analytics, consumables). Manufacturers can increase customer lifetime value by bundling predictive maintenance, remote diagnostics, and spare-part pipelines for large-sample platforms.
-
Target high-growth application intersections. While we do not disclose granular subsegment share in this preview, our full report highlights which application intersections are growing fastest. Strategic investors should focus on offerings that address combined needs — for example, semiconductor process control paired with high-throughput wafer inspection, or Raman-coupled AFM for chemically-sensitive materials research.
-
Use concentration dynamics to shape M&A and partner playbooks. Leaders with strong installed bases are investing in ecosystem plays (software, probes, service networks). For challengers, partnering with specialized platform providers or acquiring capability-focused startups can be a faster route to competing effectively in 2026.
Competitive landscape — what matters in 2026
Leading vendors remain differentiated by a mix of platform breadth, application specialization, and service ecosystems. Key players we profile in the full study include established instrument manufacturers, niche innovators, and vertically integrated metrology firms. Strategic takeaways by capability:
-
Platform breadth and metrology integration: Firms offering families of AFM instruments across research and industrial grade systems maintain advantage in enterprise procurement cycles where compatibility with legacy workflows and cross-center standardization matter.
-
Application specialization: Vendors that pair AFM systems with domain-specific software (e.g., battery research suites, semiconductor defect-classification workflows, or bio-AFM protocols) unlock premium pricing and stickiness.
-
Service and user community: Companies that invest in training, user conferences, and open instrument programmability cultivate ecosystems that accelerate adoption—evidenced by vendor-hosted conferences and interactive showcases in recent years.
Notable vendor actions and signals observed through 2025–2026 include product launches aimed at semiconductor metrology, expanded catalogues targeting wafer-scale inspection, and platform showcases that emphasize large-sample automation and autonomous operation. Several vendors have also emphasized quality certifications and manufacturing standardization to reassure enterprise buyers.
Technology and regulation — risk and opportunity zones
-
Probe and fabrication innovation: October 2025 demonstrations of batch-fabricated ultra-sharp probes point to falling costs and improved throughput for high-precision imaging. This reduces a key cost barrier for routine nanoscale metrology — accelerating deployment in industrial settings.
-
Multimodal convergence: January 2026 work applying multimodal AFM to advanced packaging materials demonstrates growing relevance for AFM in heterogeneous integration and hybrid bonding quality assurance — a clear demand signal for semiconductor equipment buyers.
-
Standards and compliance: Recent ISO certifications and evolving import safety standards are raising the bar for manufacturing quality and documentation. Suppliers should pre-empt regulatory friction by embedding compliance into design controls and export readiness programs.
What the full PW Consulting report delivers (practical components)
The full market study is designed as an operational playbook for procurement leads, product executives, investors, and strategy teams. Core deliverables include:
-
Granular market sizing and validated forecasts (historical 2020–2025 base and forecast 2026–2032), with scenario modelling across technology and regulatory pathways;
-
Segmentation deep-dives (by region, instrument type, and application) with detailed subsegment tables and growth drivers; note: these granular splits are purposefully omitted from this preview to preserve the report’s proprietary value;
-
Vendor benchmarking and capability maps (product portfolios, service models, installed base estimates, and route-to-market analysis);
-
Commercial playbooks for market entry and expansion — including pricing benchmarks, channel design, and consumables monetization templates;
-
Supply chain and regulatory risk register with mitigation levers;
-
M&A and partnership heatmaps to inform near-term deal screening and joint-venture design;
-
Practical annexes — procurement checklists, RFP language templates, and an implementation roadmap for 12–36 month horizons.
How to act on this preview in Q1–Q2 2026
-
For buyers (corporate R&D & fabs): Initiate supplier audits that prioritize upgradeability and service SLAs. Build lead-time buffers into equipment procurement timelines and require demonstrable regulatory readiness in supplier contracts.
-
For vendors: Accelerate modularity in product roadmaps, double down on consumables and software revenue plays, and formalize compliance pipelines to shorten customer procurement cycles.
-
For investors and corporates considering M&A: Use market concentration metrics and capability matrices to prioritize targets that close platform gaps or bring differentiated application IP — and validate these choices against our scenario-modeled demand curves.
Closing — why this matters for your 2026 strategy
The AFM market’s steady expansion and technological momentum create both opportunities and execution risks in 2026. Companies that treat AFM investments as strategic platform decisions — aligning procurement, product design, and service monetization — will capture disproportionate value as the market scales. Our full PW Consulting report provides the tables, segment-level growth rates, vendor scorecards, and executable templates you need to translate the market’s macro trends into operational outcomes.
To access the comprehensive datasets, subsegment breakdowns, vendor profiles, and the decision-useful annexes (including the procurement RFP templates and M&A heatmap), please consult the full Atomic Force Microscope Market report on our website. This preview deliberately omits proprietary subsegment detail to preserve the report’s tactical utility for subscribing clients.
For detailed analysis of this topic, please visit the official page: Atomic Force Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pinch Valve Market to Hit USD 847M by 2032 on 4.2% CAGR
By pmarketresearch, 2026-07-09
Pinch Valve Market 2026: Strategic Preview for Executive Decision-Makers
Executive summary
As we approach 2026, pinch valves occupy a quietly strategic position in industrial and process-control portfolios. Our latest market study—anchored to a 2025 base year and projecting through 2032—shows the market following a steady growth trajectory (CAGR 4.2% across the forecast horizon). The market has moved from an early-growth posture in the first half of this decade into a phase characterized by selective product innovation, distribution consolidation, and application-driven adoption that rewards lifecycle optimization and system integration.
Pinch Valve Market
This preview outlines the strategic value of the full PW Consulting report for executives preparing 2026 plans. It highlights directional market sizing, competitive dynamics, technology and channel trends, and the practical tools included in the publication that enable fast, decision-ready actions—while intentionally omitting core segmented datapoints that are reserved for subscribers.
Pinch Valve Market
Why 2026 is a decisive planning year
-
CapEx cycles: Capital allocation in water/wastewater, mining, and food & beverage is moving from catch-up replacement toward targeted modernization programs. Buyers in 2026 will favor suppliers who can demonstrate lower total cost of ownership rather than lowest first-cost.
Pinch Valve Market -
Supply-chain resilience: Material choices and tube-sleeve sourcing have emerged as differentiators. Designs that permit the use of lower-cost tube materials in appropriate applications are expanding addressable markets without compromising reliability.
-
Regulatory and hygiene demands: Sterile and single-use trends in pharmaceuticals and life sciences compress design cycles and increase the premium on compatibility with regulated environments.
Market trajectory—what the macro data tells you
PW Consulting’s topline market sizing shows clear, measurable momentum. From our historical baseline, the market has expanded meaningfully through 2025 and continues to advance through the forecast period to 2032 under a steady compound annual growth rate (CAGR) of 4.2%. This growth path reflects combined demand from replacement cycles, capacity additions in targeted end markets, and incremental uptake driven by product innovation in sleeve life and actuator efficiency.
For executives, this profile creates a predictable planning envelope: investment cases that hinge on multi-year paybacks can be built with confidence, while shorter-cycle go-to-market initiatives can exploit pockets of higher-than-average demand. The market is large enough to support new entrants and adjacent incumbents, yet fragmented enough that focused tactical moves—distribution agreements, tube-material partnerships, or niche product launches—can meaningfully shift competitive position.
Key dynamics and technology trends shaping 2026 decisions
-
Longevity of consumables: Sleeve technology innovations and manufacturing methods that extend sleeve life materially change maintenance intervals and whole-life costs. Innovations that extend sleeve life or reduce stress on the tube sleeve will command premium valuation in industrial applications.
-
Design-for-single-use and compact automation: Motorized, compact pinch valve designs tailored for single-use systems reduce plant footprint and ease integration into automated lines—critical for pharmaceutical single-use processing and lab automation.
-
Cost-down tube compatibility: New valve designs that permit the controlled use of cost-effective tube materials (e.g., certain PVC compounds) without sacrificing process integrity open large pricing-sensitive segments, especially in filling and dispensing.
-
Diagnostics and integration: The addition of state-feedback, LED diagnostics, and cleaner actuation options increases appeal to labs and automated production facilities where uptime and traceability are non-negotiable.
-
Channel plays and regional distribution: Strategic distribution partnerships that bundle certification (ASME/ANSI, DIN, ISO) and local service capabilities accelerate municipal and utilities adoption where compliance and serviceability are primary buying criteria.
Competitive landscape—strategic profiles and implications
The market is consolidated at the top but remains broadly fragmented, providing opportunity for regionally strong, technology-focused, and service-led players. The report analyzes leading vendors and their strategic postures; below is a high-level synthesis of core players and what they represent for potential partners or acquirers.
-
Onyx Valve Company (Cinnaminson, NJ, USA) — A U.S.-based manufacturer focused on pneumatic and heavy-duty pinch valves with a vertically integrated, in-house machining and assembly model. Onyx’s strength lies in industrial-grade robustness and a manufacturing footprint that supports rapid customization for heavy industrial flow-control needs. Strategic implication: attractive partner for end-users requiring fast customization and domestic sourcing assurances.
-
Lexair, Inc. (Lexington, KY, USA) — Known for Tube-O-Matic® pneumatic pinch valves, Lexair targets abrasive, corrosive, and fibrous media control. In-house manufacturing produces consistent quality for fluid power and industrial applications. Strategic implication: compelling fit for distributors and OEMs seeking proven solutions for abrasive-service lines.
-
RF Valves, Inc. (Hanover, MD, USA) — Differentiates on sleeve longevity and ruggedness with patented tube-folding technologies. Their product set spans high-pressure conditions and a wide dimensional range, making them a go-to for applications demanding extended sleeve life. Strategic implication: potential acquisition target for firms aiming to own key sleeve-life IP.
-
Valmet Oyj (Espoo, Finland) — Through Flowrox™ products, Valmet brings a heavy-duty, process-centric portfolio targeting slurry, powder and granule handling across mining, wastewater, and power generation. The company’s global reach and cross-industry experience make it a strong contender for large projects requiring integrated supply and lifecycle services.
-
AKO Armaturen & Separationstechnik GmbH (Trebur-Astheim, Germany) — Specializes in hygienic and sterile pinch valves, offering online commerce and a wide DN range. AKO’s emphasis on hygiene, Ex-rated products, and rapid web-based ordering meets the needs of food, pharma, and process industries prioritizing compliance and speed.
Recent market moves—motorized pinch valves for single-use systems, power-optimized designs for cost-sensitive filling processes, precision lab-focused valves with integrated diagnostics, and strengthened regional distribution partnerships—highlight how vendors are carving out differentiated plays. Each of these moves translates into tactical opportunities for buyers and bidders: product licensing, co-development, and exclusive distribution are practical levers to accelerate market entry or defend share.
What the full report contains (practical, execution-ready content)
The PW Consulting market study is designed for immediate operational use by strategists, BD teams, product managers, and procurement. Key deliverables include:
-
Methodology and transparent market-sizing model (base year 2025; historical 2020–2025; forecast 2026–2032) with downloadable inputs and sensitivity toggles.
-
Segment-level frameworks (by type, by application, by region) and buyer-persona heat maps—note: granular segment-specific financial tables are available in the subscriber edition.
-
Supply-chain mapping, bill-of-material cost drivers, and sleeve-material sourcing playbooks.
-
Competitive benchmarking with strategic positioning matrices, SWOTs, and M&A candidate shortlists.
-
Commercial playbooks: pricing strategies, distributor scoring, tender-response templates, and channel incentive models geared to 2026 procurement cycles.
-
Risk and scenario analysis covering raw-material shocks, regulatory tightening in hygienic sectors, and rapid substitution risk from alternative flow-control technologies.
-
Implementation roadmaps: 90/180/365 day execution plans for product launches, partner rollouts, and retrofit campaigns targeting mid-sized utilities and process OEMs.
Actionable strategic implications for 2026
-
Prioritize whole-life economics: Reframe selling propositions to procurement teams around sleeve longevity, mean-time-between-maintenance (MTBM), and field-service limits—not just per-unit price.
-
Targeted product bets: Invest selectively in motorized compact designs and state-feedback diagnostics for single-use and lab markets, while preserving a robust industrial portfolio for heavy-duty slurry and abrasive services.
-
Channel acceleration: Secure distribution agreements in geographies where local certifications and on-the-ground service convert tenders—partner with regional players that can offer ASME/ANSI/DIN/ISO compliance and rapid spare-part fulfillment.
-
M&A and IP strategy: Consider tuck-in acquisitions that bring sleeve-life innovations or tube-material compatibility into your product set to quickly differentiate on lifecycle cost.
-
Operational readiness: Align production footprints to support customization and rapid lead times—vertical integration can be a competitive advantage in industrial and high-spec applications.
How to access the full intelligence
This preview is designed to demonstrate the depth and directionality of our analysis while reserving the detailed segment-level models and transactional intelligence for the full report. Subscribers receive the complete dataset, downloadable market model, supplier scorecards, and implementation templates needed to start executing in 2026.
For direct inquiries and bespoke briefings—competitive benchmarking tailored to your portfolio, acquisition target screens, or a 90-day go-to-market plan—PW Consulting’s Pinch Valve Market team is available for executive workshops. The full report includes named company analyses, recent development timelines, and an appendix with sourced primary interviews and supplier contacts to accelerate your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Pinch Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Drilling for Aerospace to Reach USD 344.8 Million by 2032
By pmarketresearch, 2026-07-09
Laser Drilling Machine for Aerospace Market: Strategic Insights for 2026 Decision-Makers
As aerospace programs push for higher thermal efficiency, lighter architectures, and tighter tolerances, laser drilling has evolved from a specialized capability into a strategic enabler across turbine manufacturing, hot-section component repair, and complex composite processing. This briefing previews PW Consulting’s upcoming market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—designed to inform board-level capital allocation, manufacturing modernization roadmaps, and supplier selection in 2026.
Laser Drilling Machine for Aerospace Market
Executive snapshot
The global market for laser drilling machines applied to aerospace is on a sustained growth path. Our topline measures show the market expanding from about USD 163 million in 2020 to roughly USD 215 million in 2025, and continuing to grow at a compound annual growth rate (CAGR) of 6.98% through the forecast window to reach an estimated USD 345 million by 2032. Importantly, market composition remains fragmented (CR3 ~24.6%, CR5 ~26.2%), a dynamic that shapes competitive positioning and partner strategies.
Laser Drilling Machine for Aerospace Market
Why this research matters for 2026 decisions
-
Timing of investment: Procurement and CAPEX cycles for specialty laser equipment require lead times of 6–24 months when considering NADCAP/OEM qualification, fixture design, and automation integration. The 2026 planning year is therefore the decisive window for firms that want equipment operational for the mid-decade rise in aero engine MRO and new engine ramp-ups.
Laser Drilling Machine for Aerospace Market -
Risk calibration: Aerospace customers now demand certified process chains (NADCAP, OEM approvals). Our analysis quantifies the incremental time and cost to achieve those approvals and models break-even timelines for systems deployed in high-throughput effusion cooling hole production versus low-volume repair use cases.
-
Technology match: Different laser architectures (fiber, YAG, CO2) and multi-axis kinematics deliver distinct trade-offs in throughput, hole quality, and material scope. Choosing the wrong class of machine can constrain future product lines or force costly retrofits—this report maps those trade-offs against real-world aero alloy and composite use cases.
Market trajectory and strategic implications
The market’s near-term growth is driven by three converging forces: accelerating demand for high-efficiency turbine engines and their tighter cooling requirements; the expanding scope of additive and hybrid manufacturing where laser drilling is a finishing step; and an increase in aero MRO volumes as global aircraft utilization normalizes. Given the near-7% CAGR, executives can expect a meaningful enlargement of the addressable market over the next six years, but with continued heterogeneity by use case—production drilling for OEMs, repair/overhaul, and service bureau models.
For CFOs and strategy teams, the implication is clear: allocate capital where unit economics are validated for certification-heavy aerospace pathways (payback periods differ materially between high-volume effusion hole production and low-volume repair lines). For procurement and operations, prioritize systems that minimize qualification cycles and can be integrated into multi-stage automation cells.
Technology & process dynamics
-
Precision and speed: State-of-the-art multi-axis platforms deliver micro-hole precision down to 0.05 mm and positioning accuracy on the order of single-digit micrometers—examples include 5-axis systems reporting 9 µm positioning and process rates reaching hundreds of bores per second in optimized setups. These performance envelopes unlock high-density cooling patterns and enable consistent blade/airfoil production at scale.
-
Certification and standards: Success in aerospace requires more than a capable laser source. NADCAP accreditation for non-conventional machining (e.g., Laser Beam Machining) and OEM approvals (GE, Rolls-Royce, Pratt & Whitney, Honeywell) are de facto entry barriers. Our report quantifies certification pathways, average lead times, and typical rework/loss rates encountered during initial qualification.
-
Material & process breadth: Fiber lasers dominate new system deployments due to beam quality, reliability, and maintenance profiles, but YAG and other architectures retain niche roles (e.g., certain repair or ceramic applications). Multi-axis kinematics (5–7 axes) and moving-beam concepts reduce fixturing complexity and enable trepanning and helical drilling approaches needed for specific aero geometries.
Competitive landscape — who matters and why
Market fragmentation presents both challenge and opportunity. Our competitive module profiles the installed- and emerging-base players that matter to OEMs, MROs, and service providers.
-
DMG MORI — Positioned with a 5-axis LASERTEC PowerDrill family that emphasizes precision drilling for turbine blades and vanes. Their product differentiation stems from integrated process control (PowerShape and LASERSOFT stack), which eases qualification and supports advanced cooling-hole patterns in high-value aero components.
-
Prima Power — Known for multi-axis LASERDYNE-class systems delivering micro-hole accuracy and low heat-affected zones. Prima’s strength lies in CNC monitoring and a focus on minimizing collateral metallurgical effects—an important consideration for OEMs designing thin-wall cooling passages.
-
EBTEC Corporation — A U.S.-based provider combining Nd:YAG and fiber options across a range of power classes. Their aerospace-aligned credentials (AS9100, NADCAP) and OEM approvals make them a go-to for both production and certified repair workflows, particularly within North America.
-
Corry Laser Technology — Specializes in moving-beam, multi-axis systems and holds multiple OEM certifications. Their architecture is optimized for complex 3D geometries and trepanning techniques common in hot-section components.
-
Lenox Laser and Accumet Engineering — Represent service-focused players and niche-system integrators that excel in calibrated micro-hole work, small-leak and flow-control components, and secondary processing services—critical for shops that prefer outsourcing over heavy capital investment.
Recent industry activity—trade-show rollouts, new smart drilling modules, and concentrated industry forums—underscores a cycle of continuous incremental innovation rather than a disruptive technology replacement. In short: expect performance and integration improvements, not wholesale architectural shifts, over the 2026 planning horizon.
Strategic options for different stakeholders
-
OEMs scaling production: Invest in multi-axis fiber laser assets with integrated process control and plan for staggered qualification to avoid production bottlenecks. Consider co-investment or long-term supply agreements with equipment vendors that offer shared validation support.
-
MRO and repair networks: Evaluate a mixed strategy—retain a limited in-house certified capability for high-value, time-sensitive repairs, and contract out overflow to specialized service providers. Prioritize systems that minimize setup time for diverse component portfolios.
-
Component suppliers & bureaus: Differentiate via certifications and throughput economics. NA/EMEA supply chain dynamics favor service providers with quick certification turnarounds and repeatable quality metrics documented for OEM audits.
-
Investors & private equity: Low market concentration and the capital intensity of certification create consolidation opportunities. Targets with proven NADCAP workflows, sticky OEM relationships, and scalable automation have the most attractive exit pathways.
What’s inside the full report (practical deliverables)
-
Proprietary market-sizing model with bottom-up demand drivers, scenario-based forecasts to 2032, and sensitivity analysis around engine program cycles and MRO utilization.
-
Decision-grade capex and TCO calculators tailored to common deployment models (high-volume OEM line, repair cell, and contract-service bureau).
-
Regulatory and certification playbook that maps NADCAP requirements, OEM audit expectations, and a stepwise timeline to achieve end-client approvals.
-
Supplier heatmaps and vendor profiles with comparative matrices on precision, throughput, service capability, and integration maturity for automation and Industry 4.0 data exchange.
-
Use-case templates: validated process plans for effusion cooling hole production, hybrid additively manufactured surfaces finishing, and repair workflows that reduce cycle time while preserving metallurgical integrity.
-
Negotiation levers for procurement: recommended contract terms, performance-based acceptance criteria, and warranty/maintenance structures geared to aerospace customers.
How to use this research in 2026 planning cycles
Leaders should use the study as a decision-support tool across three planning pillars: where to commit capital, how to structure supplier partnerships, and what capabilities to certify in-house. The market’s projected expansion and continued fragmentation mean that timing, certification readiness, and supplier selection will drive both operational performance and program risk. The report provides the analytics to weight those choices objectively.
Final note — preview, not a substitute for the full study
This briefing showcases the strategic contours and operational levers relevant to laser drilling adoption in aerospace but intentionally omits detailed regional and application-level breakouts, unit economics for specific machine classes, and proprietary segmentation that underpin our forecasting model. Those datasets and the interactive tools described above are available only in the full PW Consulting report, which is essential for transaction-level decisions and program-specific investment cases in 2026.
For detailed analysis of this topic, please visit the official page: Laser Drilling Machine for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dot Peen Marking Market to Reach USD 615.4M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-09
Dot Peen Marking Machines Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As manufacturers and traceability-focused stakeholders prepare capital and product decisions for 2026, the dot peen marking machines market presents a predictable, resilient growth story — but one that rewards targeted strategy more than broad optimism. Our new PW Consulting industry primer synthesizes five years of historical performance (2020–2025) and a forward-looking scenario through 2032 to translate market momentum into actionable choices. The market expanded from approximately USD 295 million in 2020 to about USD 399 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of roughly 6.5% through the forecast window, reaching an estimated USD 615 million by 2032. These topline dynamics create distinct windows for product innovation, channel reorientation, and consolidation plays — each explored at a level designed to inform boardroom decisions while reserving the granular segmentation tables and source datasets for the full report.
Dot Peen Marking Machines Market
Why 2026 is a strategic inflection point
Two converging phenomena make 2026 uniquely consequential. First, regulatory and quality frameworks (medical device MDR/UDI, automotive IATF 16949, aerospace AS9100, and public sector traceability procurement rules) are maturing, converting compliance needs into recurring demand for permanent, verifiable marking. Second, operational modernization across factory floors — from serialized traceability to embedded track-and-trace in automated production lines — is accelerating buyers' preference for integrated and networked marking solutions. Taken together, these drivers shift vendor evaluation criteria from basic hardware reliability to lifecycle services, software interoperability, and data assurance.
Dot Peen Marking Machines Market
Market dynamics and growth drivers
- Regulatory-led baseline demand: Dot peen marking is explicitly referenced in multiple regulatory and standards contexts for traceability and durability; this regulatory tailwind underpins steady baseline growth rather than one-off purchases.
- Industry diversification: Traditional heavy-industry and automotive use remains important, while aerospace, medical device manufacturing, and precision electronics contribute above-average quality and traceability requirements, expanding the addressable market for higher-specification machines.
- Shift toward portable and line-integrated solutions: Buyers increasingly value flexibility — portable, battery-operated units for field servicing and compact, integrated systems for in-line serialisation. This bifurcation invites differentiated product roadmaps.
- Aftermarket and software monetization: As marking becomes a node in digital traceability loops, software modules for data capture, audit-ready logs, and predictive maintenance create recurring revenue opportunities that outsize hardware margins.
- Technical substitution risk: Laser marking continues to encroach on some higher-volume and non-ferrous applications. Dot peen retains advantages in depth, permanence, and cost-per-mark for many metallic components, but vendors must articulate a defensible value proposition.
- Validation and durability requirements: Proven resistance to abrasion and corrosion (e.g., salt spray standards) and compatibility with customer quality regimes materially influence procurement choices.
Competitive landscape: who matters and why
The market remains moderately fragmented: the top three suppliers control a meaningful but not dominant share, and the top five increase concentration only modestly — a structure that supports both organic positioning and opportunistic M&A. Competitors can be grouped by capability and strategic posture:
Dot Peen Marking Machines Market
- Pryor Marking Machines (Sheffield, UK): Niche specialist known for low-stress permanent marking; appeals to customers where material integrity matters. Strength: specification-led engineering and British manufacturing pedigree.
- MarkinBox (Tokyo, Japan / MB Metal Technologies): Japanese engineering quality with a portfolio spanning portable and line-integrated solutions; plays well to East Asian OEMs and precision manufacturers focused on reliability.
- Telesis Technologies (USA): Rugged product lines designed for industrial production environments (e.g., PINSTAMP, BenchMark). Strength: robustness and established line-integration credentials for high-throughput shops.
- Brady (formerly MECCO) (USA): Offers deep and fast marking systems targeting heavy fabrication and metalworking sectors; active in trade shows demonstrating product breadth and new pin/laser hybrids.
- Pannier Corporation (USA): Focus on battery-operated and portable models for traceability in field and shop-floor contexts; strong aftermarket and field-service positioning.
- Kwik Mark Inc. (USA): Compact benchtop and heavy-duty offerings for tag and plate marking — appeals to mid-market fabricators and labeling houses.
- Automator Marking Systems (Italy): Long heritage in portable, production-integrable markers; European OEM relationships and legacy service networks are strategic assets.
- SIC Marking & Gravotech (France): Multi-technology players that pair dot peen with lasers and scribe options; their systems approach and regulatory positioning make them preferred suppliers for complex traceability programs.
- TechnoMark Inc. (USA): Emphasizes seamless production-line integration and compliance-driven marking solutions, with market traction in oil and gas and industrial tooling where standards enforcement is strict.
- CNMarking (China): Cost-competitive electric and pneumatic offerings targeted at automotive and component suppliers; pressure on price-sensitive procurement channels is a persistent competitive factor.
Recent trade-show activity — for example, Brady’s visible presence at major industry events and other exhibitors demonstrating hybrid marking capabilities — signals that incumbents are investing in both product evolution and channel visibility. These market signals are important leading indicators for procurement cycles and competitive responses in 2026.
Strategic implications for 2026 decision-making
- For OEMs and large end-users: Treat marking as a systems decision, not a point purchase. Prioritize suppliers that offer validated compliance outputs (audit-ready logs, standardized mark verification), integration APIs, and a clear roadmap for software-driven services. Consider multi-vendor pilots to stress-test in-line performance under real production tolerances.
- For manufacturers and suppliers: Differentiate on software and services. Hardware alone will compete increasingly on price. Invest in remote diagnostics, subscription-based maintenance, and modules that capture traceability metadata to create annuity streams.
- For investors and private equity: The market’s moderate concentration suggests ripe opportunities for roll-up strategies — combine regional specialists with software enablers and aftermarket platforms to create scale and margin expansion. Target companies with installed base data and service revenue potential.
- For procurement and service providers: Reassess total cost of ownership (TCO) frameworks to include mark validation, regulatory audit costs, and product lifecycle software. Lower upfront costs can be false economies when compliance and traceability audits are factored in.
- For product teams: Roadmaps should balance ruggedization (for heavy industry) and miniaturization/portability (for field service and small-batch manufacturers). Hybrid offerings that combine dot peen and laser or offer configurable heads will win proof-of-concept budgets.
What the PW Consulting report delivers — practical contents
Our market study is structured to convert insight into action. Highlights include:
- Topline market sizing and validated forecast model (2026–2032) with scenario sensitivity for substitution risk and regulatory tightening.
- Competitor dossiers and capability matrices that map product families to buyer needs, service footprints, and integration readiness.
- Regulatory and standards matrix aligning marking technologies to industry-specific compliance requirements and test protocols.
- Commercial playbooks: GTM templates, channel scorecards, price-to-service migration pathways, and aftermarket pricing strategies.
- Transaction support tools: diligence checklists, synergy quantifiers for roll-up cases, and vendor selection rubrics for strategic sourcing.
- Practical tools for operators: ROI calculators for fleet upgrades, lifecycle maintenance schedules, and a sample API data model for traceability integration.
To respect confidentiality and buyer timing, the full report retains the granular regional and application-level datasets, supplier-level share tables, and downloadable model files exclusively behind our access layer — ensuring clients gain both data and an executable plan.
How to use this research in 2026 decisions
Concrete use cases where our analysis creates value in 2026:
- CapEx prioritization: Use the forecast scenarios and TCO models to decide which lines to upgrade first, balancing volume concentration with regulatory exposure.
- Sourcing strategy: Develop supplier segmentation (core, qualified, contingency) informed by supplier capability matrices and service footprints.
- M&A diligence: Rapidly size target acquisition upside by applying our synergy templates to service cross-sell and geographic expansion levers.
- Product roadmap decisions: Allocate R&D budgets between hardware robustness improvements and software/IoT integration based on quantified demand vectors in the report.
- Compliance remediation: Map your product portfolio to standards and validation tests required by customers (e.g., medical, aerospace) to prioritize certification investments.
Conclusion and next steps
The dot peen marking market is not a high-velocity disruptor; it is a steadily growing, standards-driven market where differentiation will accrue to firms that combine durable hardware with software, services, and compliance assurance. With the aggregate market expanding from roughly USD 295 million in 2020 to near USD 399 million in 2025 and an expected rise to about USD 615 million by 2032 (CAGR ~6.5%), the next 12–18 months are prime for strategic positioning. Whether you are an incumbent supplier, a manufacturing OEM, or an investor, 2026 choices about integration, service models, and product architecture will determine who captures the higher-margin, durable segments of the industry.
For the complete datasets, supplier share tables, region- and application-level breakouts, and fully modeled forecast files used to construct these scenarios, access the full PW Consulting Dot Peen Marking Machines Market report. Our team is available to run a tailored briefing and to map these findings into a 90-day action plan aligned to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Dot Peen Marking Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grain Combine Harvester Market Poised for 4.85% CAGR Through 2032
By pmarketresearch, 2026-07-09
Grain Combine Harvester Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this executive preview of our Grain Combine Harvester Market study to outline the decisions that will define competitive positions in 2026. The market narrative below combines our proprietary modeling, public signals, and on‑the‑ground commercial intelligence to show where value will be created — while reserving the detailed segment tables and proprietary forecasts for the full report.
Grain Combine Harvester Market
Market snapshot: what the numbers tell us
After a steady recovery and reinvestment cycle across advanced agriculture markets, the global grain combine harvester market reached an estimated USD 165 million in our base year (2025). Our model projects a mid‑single‑digit compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window, culminating in a market near USD 235 million by 2032. Historical dynamics between 2020 and 2025 show a clear structural rebound driven by capacity upgrades, technology adoption, and replacement demand in mature markets, coupled with accelerated mechanization in select growth geographies.
Grain Combine Harvester Market
These topline dynamics matter because they change the calculus for capital allocation, product roadmaps, and aftermarket strategies: growth is steady but selective, meaning firms that target profitable segments and operationalize service economics will outperform those competing on volume alone.
Grain Combine Harvester Market
What the report delivers — practical, transaction‑ready insights
- Validated market sizing and scenario‑based forecasts (base year 2025; forecast period 2026–2032) with transparent methodology and sensitivity testing.
- Segment playbooks (by type, application and geography) designed for priority setting — note: granular split tables are included in the full report.
- Competitor value‑chain maps, including product portfolios, pricing ladders, and go‑to‑market channels.
- Strategic frameworks for R&D prioritization, aftermarket expansion, and dealer network optimisation.
- Supply‑chain stress tests and sourcing redesign options to de‑risk critical components and spare parts availability.
- M&A screening templates and synergy calculators to assess bolt‑on targets or vertical plays.
- Commercial playbooks for pricing, leasing, and operator training to accelerate adoption of higher‑value configurations.
Key market dynamics shaping 2026 choices
- Technology is the differentiator. Automation (harvest settings automation, predictive ground‑speed control), advanced headers, and telematics are moving from premium differentiators to near‑table stakes for enterprise customers seeking throughput and reduced operator variability. Recent OEM updates — for example, John Deere’s 2026 enhancements to X9 and S7 series and New Holland’s 2026 model updates — underscore this push.
- Aftermarket economics are mission critical. With replacement cycles stretching and capital expenditure constrained for many operators, parts, service contracts, and upgrades are the principal lever to preserve margin. Firms that systematize spare parts logistics and remote diagnostics will capture recurring revenue and raise switching costs.
- Regulatory and sustainability pressures are intensifying. Emissions compliance for diesel powertrains is not optional. OEMs are already integrating third‑generation SCR systems and optimizing engine architectures (as seen with manufacturer programs), which affects cost structures, supplier selection, and R&D timetables.
- Market concentration creates strategic opportunity and risk. The market exhibits meaningful concentration at the top end: a small set of global incumbents command a disproportionate share of value. That creates scale advantages in R&D and distribution but also opens niches for specialized or lower‑cost entrants in segments where service and price sensitivity dominate.
- Geography and crop mix matter — but selectively. Growth pockets are uneven. The implication for manufacturers and investors is to avoid blanket geographic expansion; instead, apply a targeted market‑entry play that aligns product configuration, dealer capability, and financing models to local operator economics.
- Macro forecasts vary by source. While some industry sources projected modest growth into 2026, our model — which incorporates machine economics, adoption lags, and parts monetization — points to stronger medium‑term expansion, reinforcing the case for action rather than wait‑and‑see.
Competitive landscape: how to think about rivals in 2026
Leading OEMs maintain differentiated positions based on technology stacks, distribution breadth, and brand trust. Global incumbents emphasize automation, capacity, and integrated precision solutions; legacy European and North American players typically combine premium R&D with deep dealer networks, while select Asian manufacturers compete on cost‑performance and export agility.
- Technology leaders continue to push automation and operator aids to compress harvest windows and improve throughput — features that enterprise customers prize during tight harvests.
- Volume players secure share through localized manufacturing, aggressive component sourcing, and competitive price points for standardized configurations.
- Service specialists differentiate on uptime guarantees, rapid parts fulfilment, and tailored financing/leasing models that lower adoption friction for mid‑tier operators.
Our competitive dossiers include tactical intelligence on each major OEM’s product roadmap, channel economics, and recent developments. As examples, John Deere’s 2026 product updates add tighter automation controls and operator aids to defend premium positions, while New Holland’s 2026 model refreshes emphasize header performance and adjustability that appeal to high‑output operators. At the same time, export‑focused manufacturers from other regions prioritize cost, parts availability, and regulatory compliance to expand footholds.
Strategic playbook: recommended actions for 2026
- Reprioritize R&D dollars: Shift investment toward modular automation features and remote diagnostics that are monetizable through subscription or retrofit programs.
- Double down on aftermarket capabilities: Build regional spare‑parts hubs, digitize inventory management, and create service SLA tiers that capture willingness to pay for uptime.
- Rethink channel economics: Move from transactional distribution to partnership models with dealers that include shared KPIs, outcome‑based pricing, and co‑funded training for operators.
- Embed emissions roadmaps into product strategy: Prioritize engine and after‑treatment investments now to avoid late‑cycle compliance cost shocks and to position products as future‑proof.
- Use M&A tactically: Target acquisitions or alliances that close capability gaps in telematics, headers, or local service infrastructure rather than pursuing only scale buys.
- Apply scenario‑based capital planning: Stress test CapEx and inventory policies under multiple harvest pricing and supply‑chain disruption scenarios before committing to factory expansions.
- Launch pilot commercialization models: Experiment with short‑term leasing, operator training bundles, and yield‑linked contracts to accelerate adoption among risk‑averse customers.
How PW Consulting’s study accelerates execution
Our full study goes beyond narrative to provide transaction‑ready tools: a calibrated financial model you can plug into your internal planning, dealer profitability matrices, a prioritized R&D roadmap with estimated ROI windows, and a deal‑sourcing list for inorganic options. We validate market assumptions against primary interviews, trade flows, and OEM announcements so that your 2026 roadmaps are grounded in market reality rather than optimistic guesses.
Importantly, while this preview shares high‑level conclusions and the strategic lens you need for 2026, detailed segment tables, regional breakdowns, and the full set of proprietary unit‑price curves are intentionally excluded here. Those elements are included in the published report and the interactive models we deliver to clients.
Immediate next steps for senior leaders
- Commission a rapid 60‑day audit of your aftermarket operations and parts inventory to identify quick win margin improvements.
- Run an R&D reallocation workshop using our scenario templates to quantify payback timelines for automation and emissions projects.
- Engage in disciplined channel segmentation: identify top dealers for strategic investment and a second tier for performance improvement programs.
- Secure a shortlist of M&A targets that fill capability gaps (telematics, headers, regional service hubs) and run preliminary valuation stress tests using our synergy model.
- Schedule a briefing with PW Consulting to receive the interactive forecast model and a bespoke 90‑day action plan tailored to your portfolio.
In short: 2026 will be a year for choices that compound. Firms that convert the macro growth tailwinds into differentiated, service‑driven revenue streams — while hardening their product and regulatory roadmaps — will capture disproportionate value. Those that continue to compete on price alone will find margins compressed as service and technology become the primary battlegrounds.
For the complete data tables, regional and application splits, and the interactive forecast model, schedule a briefing with PW Consulting or visit our Grain Combine Harvester Market report page to unlock the full intelligence package and bespoke strategy options for 2026.
For detailed analysis of this topic, please visit the official page: Grain Combine Harvester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Advanced IC Packaging Equipment Market Poised for 12.5% CAGR Through 2032
By pmarketresearch, 2026-07-09
Advanced IC Packaging Equipment Market: Strategic Imperatives for 2026 Decision‑Makers
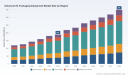
This briefing introduces PW Consulting’s Advanced IC Packaging Equipment Market study — a practical, decision‑focused analysis designed for executives who must set technology, capital‑investment, and supply‑chain strategy in 2026. Built on a 2025 base year with a historical window covering 2020–2025 and a forward view to 2032, the study frames opportunities and risks for equipment OEMs, OSATs, IDM packaging groups, private equity investors, and national policy planners. At the macro level, the market is forecast to expand from approximately USD 190 Million (base year 2025) to roughly USD 350 Million by 2032, representing a compound annual growth rate of about 12.5% — a pace that signals meaningful capital redeployment and technology refresh cycles across the ecosystem.
Advanced IC Packaging Equipment Market
Why this study matters in 2026
-
Technology inflection: Advanced packaging has moved from a performance differentiator to a foundational enabler for AI accelerators, high‑bandwidth memory (HBM), and heterogeneous system integration. Industry indicators show a majority of AI accelerator shipments already leveraging advanced packaging formats, driving demand for fine‑pitch interconnects and hybrid bonding process tools.
Advanced IC Packaging Equipment Market -
Policy and capital: Public programs (for example, national semiconductor initiatives awarded to packaging projects) and fresh private investments are de‑risking domestic capacity builds. That shift is creating windows for suppliers and OSATs to secure subsidies, but it also compresses timelines for equipment qualification and factory ramp‑up.
Advanced IC Packaging Equipment Market -
Market economics: The projected mid‑teens CAGR for equipment demand outpaces many adjacent semiconductor capital categories, reflecting both unit volume growth and significant per‑unit price escalation tied to higher automation, metrology integration, and yield enhancement capabilities.
Key market dynamics shaping buyer choices
-
Integration complexity: The move to multi‑die and silicon‑interposer solutions elevates requirements for precision dicing, thinning, hybrid bonding, and wafer‑level assembly. Buyers must prioritize equipment that integrates metrology and in‑line inspection to contain yield loss as overlay and planarity tolerances tighten.
-
Throughput vs. fidelity tradeoffs: As device architectures push pitch and density limits, the classic tradeoff between throughput and process fidelity becomes strategic. Early adopters of process platforms that maintain yield at scale will extract the largest marginal returns during the 2026–2029 ramp.
-
Automation and labor dynamics: Rising labor costs and workforce shortages in key geographies are increasing the value of robotics and end‑to‑end automation. Capital allocation should reflect not only machine cost but operational expense savings and reduced qualification time through standardization.
-
Supply resilience and localization: Geopolitical dynamics are prompting OSATs and IDMs to diversify equipment sourcing and to seek regional redundancy. Supplier selection today must factor export controls, spare‑parts logistics, and the ability to establish local service footprints.
-
Materials and process validation timelines: Raw‑material availability and incremental process windows (e.g., for new plating chemistries or thermal interface materials) are increasingly rate‑limiting. The most competitive equipment suppliers are those that partner upstream with materials vendors to accelerate qualification.
What the PW Consulting study delivers (practical, executable content)
-
Forward‑looking market sizing and demand modeling: a disciplined baseline (2020–2025) and a scenario‑based projection (2026–2032) that translate technology adoption curves into equipment spend profiles.
-
Technology and process roadmaps: mapping of key equipment classes to packaging architectures (e.g., wafer‑level, fan‑out, 2.5D/3D) and expected lifecycle timing for next‑generation modules.
-
Procurement playbook: specification templates, qualification checkpoints, and total cost of ownership (TCO) calculators designed for procurement teams to accelerate RFQs and reduce vendor selection risk.
-
CapEx phasing models and ROI scenarios: interactive frameworks showing how different mix choices (automation intensity, throughput targets, local vs. external service models) affect payback timelines.
-
Supplier scorecards and negotiation levers: qualitative and quantitative criteria to rank suppliers across technical capability, installed base, service network, and roadmap alignment.
-
Risk heatmaps and mitigation playbooks: regulatory exposures, critical‑spare dependencies, and geopolitical scenarios with prioritized mitigation actions for 12–36 month horizons.
Competitive landscape — reading supplier intent and capacity
Our study synthesizes public disclosures, engineering footprints, and product roadmaps to generate commercially actionable insight on leading equipment suppliers. Some strategic themes emerge across the competitive set:
-
Specialists with domain depth: Firms focused on discrete process steps (for example, wafer singulation, precision dicing, or molding) continue to command premium positions where process tolerance is the primary bottleneck. These vendors preserve margin by owning critical process IP and providing turnkey qualification support.
-
System integrators and platform players: Larger suppliers that bundle metrology, bonding, and fine‑line redistribution (RDL) solutions are positioning to sell higher‑value, fully integrated lines, shortening time‑to‑yield for customers but increasing supplier lock‑in risk for buyers.
-
Robotics and automation entrants: Companies delivering high‑precision handling and pick‑and‑place systems are increasingly central to packaging lines as vendors seek to automate labor‑intensive steps and reduce footprint.
-
Geographic strategy: Some OEMs are extending manufacturing capacity in target regions to better serve local OSAT ecosystems; others are doubling down on R&D and advanced process centers to protect IP and foster co‑development.
Highlights on named competitors (directional, strategic implications):
-
PacTech — laser and wafer‑level assembly specialist: strong in laser soldering and wafer‑level ball placement; attractive partner for OSATs pursuing heterogeneous integration pathways.
-
DISCO Corporation — precision singulation and grinding leader: foundational for 3D/2.5D flows where thinning and singulation determine yield. Their product maturity shortens qualification timelines.
-
Kulicke & Soffa — assembly and bonding breadth: combines bonding platforms with lithography tools for fan‑out and other advanced processes, enabling end‑to‑end assembly solutions.
-
BESI — focused on wafer‑level and hybrid bonding processes: advantaged where substrate and leadframe variety requires adaptable assembly equipment.
-
Applied Materials — materials engineering and hybrid bonding scale: recent strategic acquisitions broadened their plug‑and‑play portfolio for heterogeneous integration, accelerating their competitiveness in pilot‑to‑production transitions.
-
SUSS MicroTec, TOWA, Yamaha Robotics, Tokyo Seimitsu, Advantest, HANMI — each brings distinct strengths across lithography, molding, robotics, grinding, test, and AI/HBM oriented packaging tools. Buyers should prefer multi‑vendor collaboration models where no single OEM covers all specialized process steps.
Recent developments shaping near‑term strategy
-
Strategic R&D and facility moves: Industry announcements in 2025–2026 — new plants, rebranding and consolidation of bonding lines, and the opening of innovation centers — reflect supplier investments in production capacity and customer co‑development. These moves shorten qualification cycles and improve responsiveness for early‑stage pilots.
-
M&A and team integrations: Acquisitions that merge niche teams into larger semiconductor groups change the competitive topology, creating more vertically integrated suppliers that can offer bundled solutions, but sometimes at the cost of reduced outside interoperability.
-
Public funding: National semiconductor programs that include packaging initiatives materially affect where new capacity will be placed and which suppliers will be favored for local content requirements.
How to translate insight into 2026 action
-
Prioritize pilot investments now: Allocate a meaningful portion of 2026 process‑development budgets to pilot lines that validate hybrid bonding, high‑density RDL, and HBM assembly. Early qualification wins shorten time‑to‑volume in 2027–2029.
-
Design for supplier modularity: When specifying equipment, insist on open interfaces and clear IP handover paths to avoid technical lock‑in while still capturing the operational benefits of integrated systems.
-
Negotiate performance‑based contracts: Shift procurement toward outcome‑based SLAs that tie payment and warranty terms to throughput and yield milestones during ramp phases.
-
Use scenario planning: Develop three prioritized scenarios (baseline demand growth, accelerated AI adoption, and fragmented/regulatory constrained supply) and stress‑test capex and sourcing plans against each.
-
Leverage public incentives strategically: Target grants and subsidies for the riskiest qualification stages (materials/process validation) while using commercial capital to scale later stages.
Closing — where to go next
The Advanced IC Packaging Equipment Market will be a high‑velocity domain between 2026 and 2032. For executives, the imperative is clear: move beyond vendor claims to quantify how equipment choices affect yield, time‑to‑volume, and unit economics across plausible demand scenarios. PW Consulting’s full report provides the granular segmentation, supplier scorecards, and downloadable CapEx models that practitioners need to convert strategy into executable programs. For the complete datasets, detailed segmentation, and executable procurement templates, please refer to the report’s primary access channel.
For detailed analysis of this topic, please visit the official page: Advanced IC Packaging Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Palletizing Machine Market to Grow at 6.12% CAGR, Reaching USD 466.6M by 2032
By pmarketresearch, 2026-07-09
Palletizing Machine Market — Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s latest Palletizing Machine Market study (base year 2025) synthesizes seven years of market dynamics and a seven‑year forward view to deliver decision-ready intelligence for executives planning capital allocation, automation roadmaps, and supply‑chain strategies in 2026. The market has demonstrated steady expansion through 2020–2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.12% over the 2026–2032 forecast window. This research is designed as a strategic playbook: it surfaces the structural moves, technological inflection points, and procurement levers that matter this year, while preserving granular segment data for licensed subscribers who require the complete dataset and vendor-level benchmarking.
Palletizing Machine Market
Market Trajectory and Strategic Context
After a measured recovery and modernization cycle in the first half of the decade, the palletizing market has moved from being a pure mechanical stacker industry into a hybrid ecosystem of robotics, collaborative automation, AI‑enabled mixed palletizing, and integrated warehouse controls. Our macro sizing shows clear momentum continuing into the next growth phase, driven by rising labor costs, SKU proliferation, tighter sustainability targets, and the increasing economics of automation for mid‑sized plants. PW Consulting’s forecast through 2032 captures how these forces compound into capital investment opportunities and operational tradeoffs that are actionable in 2026 procurement cycles.
Palletizing Machine Market
Why 2026 Is a Pivotal Decision Year
- Regulatory reset: Updated international machine‑safety standards (ISO 10218:2025) and regional palletizer safety standards (EN 415‑4:2025) materially affect cell design, validation time, and vendor certification requirements—risking schedule slips for non‑compliant retrofits.
- Labor economics: Rising labor cost baselines—illustrated by median operating wages and fully loaded cost statistics in key markets—shorten payback windows for automation and make staged rollout plans more attractive for 2026 budgets.
- Technology inflection: Cobot families and AI‑augmented mixed palletizers launched across 2025–2026 change the implementation calculus: lower‑risk pilots are now viable on lines with moderate throughput and high SKU mix.
- Integration premium: Buyers increasingly value systems that integrate controls, warehouse management, and upstream packaging lines to minimize downtime and accelerate changeover—making integrator selection as important as robot selection.
What the Full Report Delivers (Practical, Actionable Contents)
Our study is designed to convert insight into action. Highlights of the deliverables that drive 2026 decision processes include:
Palletizing Machine Market
- Proven market‑sizing methodology, with historical reconciliation (2020–2025) and scenario‑based forecasts for 2026–2032.
- Demand driver analysis (labor, e‑commerce, SKU proliferation, sustainability) and sensitivity modeling to test capex under multiple labor and component‑cost scenarios.
- Segmentation by technology, application, and region (subscriber access provides the full split tables and trend matrices).
- Vendor scorecards and a procurement playbook: RFP templates, evaluation criteria, SLA and warranty negotiation points.
- Implementation artifacts: pilot KPIs, changeover and uptime benchmarks, commissioning checklists, and plant‑level TCO calculators.
- Compliance and safety gap analysis mapped to ISO 10218:2025 and EN 415‑4:2025, with remediation roadmaps and estimated lead times.
- Technology roadmap and competitive threat matrix: robotics, cobots, AI mixed palletizing, and conveyor‑driven solutions.
- M&A and partnership pipeline mapping for strategic buyers and financial sponsors, including comp tables and integration playbooks.
Competitive Landscape — Who Moves Markets and Why
The palletizing ecosystem now includes classic robotics OEMs, turnkey system integrators, packaging specialists, and agile modular vendors. Market concentration remains moderate: the top players capture a material but not dominating share, leaving ample opportunity for specialized entrants and regional integrators.
- Robotics OEMs (ABB, KUKA, FANUC, Yaskawa): These incumbents continue to extend payloads, cycle speeds, and cell controllers. Recent product activity—such as collaborative‑grade releases and refreshed cobot families—lowers entry barriers for collaborative palletizing in mixed‑SKU environments and accelerates retrofits where footprint or personnel proximity is a constraint.
- System integrators and material‑handling leaders (Krones, BEUMER Group, Honeywell Intelligrated, FlexLink): These firms sell integrated lines and value throughput guarantees. Their competitive advantage is the end‑to‑end control stack and the ability to reduce integration risk for complex beverage, food, and consumer goods lines.
- Packaging and specialized palletizer vendors (A‑B‑C Packaging, Columbia Machine, Symach, Schneider Packaging, TopTier, NOVA Automation): These players excel at specific use cases—high‑speed cases, bundle/tier arrangements or compact cell footprints—and are frequent targets for strategic partnerships as OEMs seek to broaden portfolios.
- Modular and software‑first entrants (Vention, FlexLink): Agile platforms and AI‑driven mixed palletizing solutions are creating new procurement models (shorter lead times, subscription software, modular expansion) that can materially reduce time‑to‑value.
Recent market activity illustrates these shifts. Product launches across 2025–2026 introduced enhanced collaborative ergonomics and AI capability in palletizing lines; major vendors doubled down on cobot variants and mixed palletizer solutions showcased at global trade events. These innovations shorten pilot cycles but raise the bar for safety certification and control‑system compatibility.
Implications for Procurement, Operations and Technology Strategy
Your 2026 decisions should be organized around three strategic priorities:
- Modularity and optionality: Favor architectures that enable phased investment—start with cobot or single‑robot pilots and scale to full robotic or mixed palletizing cells as ROI is proven.
- Standards‑first design: Build compliance to ISO 10218:2025 and EN 415‑4:2025 into procurement specs to avoid retrofit risk and commissioning delays.
- Integration over components: Prioritize suppliers or integrators that provide demonstrable controls and WMS integration, not just hardware. Integration eliminates hidden costs associated with changeovers and software interoperability.
Practical Recommendations — A 2026 Playbook
- Run two parallel pilots this year: one cobot/low‑infeed line to prove economics, one full automation line for high throughput—compare payback under conservative labor inflation scenarios.
- Use our vendor scorecard to shortlist integrators who commit to safety certification timelines and provide spare‑parts availability guarantees.
- Request application‑specific TCO models that include commissioning, spare parts, planned downtime, and staff upskilling—avoid vendor quotes that list hardware only.
- Design contracts with options for modular expansion and software upgrades to capture future AI and mixed‑SKU capability without rip‑and‑replace.
- Include cybersecurity and control‑system isolation requirements in RFPs for new palletizing cells to protect upstream ERP/WMS integrations.
- Consider leasing or outcome‑based contracts where capex is constrained and where vendors can deliver uptime guarantees tied to performance.
Use Cases and ROI Patterns
We observe consistent ROI patterns across sectors: labor‑intensive, high‑SKU lines and 24/7 operations deliver the fastest paybacks; beverage and e‑commerce packing centers frequently capture early wins through layer‑forming automation and mixed palletizing. The report contains customizable ROI templates that allow you to model payback under different throughput, labor, and capital cost assumptions—critical for board‑level capex approvals in 2026.
Why PW Consulting — Research Rigor and Client Utility
Our approach combines proprietary shipment and install datasets, primary interviews with OEMs and integrators, and stakeholder workshops in manufacturing, warehousing, and procurement. We map regulatory change to implementation timelines, quantify vendor positioning, and produce client‑ready artifacts—RFPs, compliance checklists, and scenario‑based capex models—so that procurement, operations, and digital transformation leaders can act decisively this year.
To preserve strategic value for our clients, this preview intentionally omits the full segment and vendor revenue tables, regional and application splits, and the detailed vendor financial benchmarking. The full dataset and actionable appendices—complete segmentation, CR‑based market shares, vendor scorecards, and the downloadable ROI/TCO tools—are available through PW Consulting’s market page and subscription channels.
Contact PW Consulting to obtain the complete Palletizing Machine Market report, schedule a tailored briefing for your executive team, or request the interactive ROI workbook to stress‑test acquisition scenarios for 2026.
For detailed analysis of this topic, please visit the official page: Palletizing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Cyanide (HCN) Market 2026: Strategic Imperatives for Manufacturers, Offtakers, and Investors
As PW Consulting’s lead industry analyst, I present an executive preview of our full Hydrogen Cyanide (HCN) Market study — a practical, decision-grade research asset timed for companies planning capital, sourcing, and portfolio moves in 2026. This overview demonstrates the analytic depth and strategic framework we used while deliberately withholding core granular segment tables and modeling outputs to guide readers to the full report for complete intelligence.
Hydrogen Cyanide (HCN) Market
Why this study matters for 2026 decision-making
HCN sits at the intersection of specialty chemicals, industrial gases, and mining chemicals. The commodity’s role as a precursory feedstock — from nitriles to cyanide salts — means that small shifts in regulation, logistics rules, or process integration can produce outsized effects on margins and reliability for producers and consumers alike.
Hydrogen Cyanide (HCN) Market
- Base-year anchoring: Our analysis uses 2025 as the base year (historical window 2020–2025) and projects market dynamics through a 2026–2032 forecast horizon. The market size in 2025 is reported at approximately USD 2.2 Billion.
- Multi-scenario forward view: For planning purposes we supply a range of outcomes — including a baseline built on a 2.2% compound annual growth assumption for selected scenarios — alongside downside scenarios reflecting tightening transport regulations, shifts in end-use demand, and technology substitution.
- Practical orientation: The study is structured to support three types of 2026 decisions — immediate sourcing and operational measures, medium-term capital allocation and partnerships, and longer-term portfolio and regulatory engagement strategies.
Market pulse: what the headline numbers mean
Historical data show the market cooling from the early-2020 peak through 2025 as manufacturers and downstream customers adjusted inventories, upgraded safety regimes, and optimized feedstock mixes. That recent contraction is a critical backdrop for 2026 decisions: firms should not assume a return to previous demand patterns without explicit signals from end-markets and policy. The baseline scenarios in our model—which use a 2.2% CAGR for selected pathways—illustrate that modest growth is possible if integrated production and regulatory adaptation accelerate; however, downside pathways expose meaningful revenue pressure if transport and storage rules escalate compliance costs.
Hydrogen Cyanide (HCN) Market
Structurally, the market remains moderately fragmented: the top three suppliers account for roughly a quarter of total capacity, while the top five approach one-third. This concentration profile sustains opportunity for mid-sized specialists, integrated producers, and nimble on-site service models to capture value through proximity, differentiation, and service bundling.
What’s in the full report — practical tools and outputs
Stakeholders told us they needed more than descriptive analysis. The full PW Consulting HCN report therefore combines market intelligence with actionable tools designed for boardrooms and procurement floors:
- Market model (Excel) — downloadable, transparent assumptions, sensitivity toggles for feedstock costs, regulatory tax/penalty scenarios, and logistics premiums. Users can run bespoke scenarios for contract negotiation or capex planning.
- Supply chain heatmap — supplier criticality scoring, single-source exposure, and transit risk indicators by corridor (non-public, anonymized scoring to protect commercial confidentiality).
- Capex and maintenance playbook — a checklist and cost impact framework for storage, containment, and turnaround planning aligned to emerging regulatory trends.
- Commercial playbook — contracting templates, on-site production assessment methodology, and an offtake optimization matrix for consumers who want to weigh delivered vs. onsite HCN economics.
- M&A and partnership screen — high-level candidate profiles and value-creation levers tailored to buyers (scale, integration, vertical capture) and sellers (de-risking, carve-outs, JV options).
- Regulatory timeline and impact scenarios — granular mapping of near-term transport and storage rule changes and their anticipated P&L impacts across producer and consumer archetypes.
Competitive landscape: capabilities and strategic postures
The HCN value chain is populated by a mix of specialty chemical groups, industrial gas players, integrated petrochemical operators, and niche suppliers. Our competitive analysis focuses on capability clusters and strategic motions rather than raw share tables (reserved for the full report).
- Large specialty producers (e.g., Evonik Industries AG): Strong in large-scale production and supplying HCN as a precursor to specialty chemicals. Their strategic advantage lies in access to downstream customers and the ability to offer integrated value across adjacent product lines.
- Integrated petrochemical operators (e.g., INEOS): Operators with integrated nitriles complexes and on-site HCN recovery show resilience under tightening transport rules. INEOS’s recent project activity expands future process options that could lower delivered costs and reduce transport exposure.
- Industrial gas and specialty gas suppliers (e.g., Air Liquide, Matheson Tri-Gas): These firms compete on logistics expertise, purity grades, and tailored industrial-gas services (including calibration gases and small-batch specialty supply).
- Feedstock-tied producers (e.g., Ascend Performance Materials): Producers serving polymer and advanced-materials chains benefit from captive demand but remain sensitive to upstream economics and capex cycles.
- Niche and downstream specialists (e.g., Draslovka, Cyanco, Butachimie, Cornerstone Chemical, CSBP): These players focus on mining chemicals, fumigants, or on-site production models — areas where regulatory compliance, service reliability, and chemistry know-how create defensible positions.
Recent corporate moves underscore strategic themes. INEOS’s Trillium demonstration plant start-up in 2025 signals continued experimentation with process alternatives and potential feedstock flexibility. Draslovka’s completion of a major HCN storage project in late 2025 reduces certain maintenance capex pressures for their operations and demonstrates how storage investments can change the economics of supply continuity. Meanwhile, infrastructure transfers (for example, Evonik’s move of site operations to a specialist operator in 2026) are reshaping who owns operational risk vs. chemical margin.
Regulatory and logistical dynamics that will shape 2026 outcomes
- Tightening transport and storage rules: Policymakers in multiple jurisdictions are raising the bar for hazardous transport and stationary storage. These changes raise the value of on-site HCN production models, longer-term storage investments, and supplier logistics capabilities.
- De-risking through integration: Producers that can internalize recovery, minimize long-haul transport, or provide closed-loop supply to major offtakers will enjoy competitive advantage as compliance complexity grows.
- Maintenance capex vs. operational continuity: The design life and redundancy of storage assets now factor directly into procurement and insurance costs. Strategic storage projects or outsourced operational arrangements can produce immediate balance-sheet relief.
- Reputation and ESG: Even beyond hard compliance costs, HCN-related incidents create outsized reputational risk. Firms with demonstrable HSE performance, traceability, and community engagement will secure premium access to end-markets and capital.
Actionable priorities for 2026
For companies making strategic choices in 2026, we recommend a focused set of actions built on our analysis and scenario outputs.
- Procurement and operations (0–12 months): Run scenario-based procurement auctions that incorporate logistics premiums for compliance; pilot on-site supply with a trusted partner where concentration risk is high; and audit storage and emergency-response preparedness to reduce insurance and regulatory friction.
- Capital allocation (12–36 months): Prioritize investments that reduce transport exposure (on-site units, buffer storage) and investments that enable feedstock flexibility. Consider partnering with industrial gas providers or specialty operators to de-risk construction and permitting timelines.
- M&A and partnerships (12–36 months): Target assets that deliver either vertical integration into nitriles or differentiated service capabilities (calibration gases, mining-focused product lines). Small-cap specialists with strong safety records can be accretive for scale players seeking to expand applications.
- Policy and stakeholder engagement (ongoing): Engage proactively with regulators to shape feasible compliance pathways and secure consenting timelines. Transparent community engagement programs materially reduce the risk of project delays and reputational costs.
What you’ll get from the full PW Consulting HCN Market report
Our full product delivers the confidential, transaction-grade materials clients need to execute in 2026: the fully auditable market model, supplier scorecards, a library of commercial contract language, capex and opex benchmarking for production and storage options, and an M&A target shortlist cross-referenced to strategic fit and geographies. The report’s appendices include extended due-diligence templates and a regulatory playbook keyed to the most material jurisdictions.
We designed the report to be used at three decision levels — procurement teams negotiating 12-month supply, CFOs allocating mid-term capex, and corporate strategy teams evaluating M&A or divestiture options. To protect strategic value and commercial sensitivity, the full segmentation tables, regional and application-level shares, and raw scenario model are available only via the report portal.
Next steps
For a guided walk-through, PW Consulting offers a short, interactive briefing that pairs the key findings with a live run of the model and a tailored risk-heatmap for your supply chain. If you are preparing 2026 procurement terms, planning a brownfield or greenfield investment, or evaluating acquisition targets in the HCN chain, schedule a briefing to see how the full report changes the decision calculus.
HCN is a small but strategically important market where regulatory shifts and integration choices determine winners and losers. Our study equips leaders with the scenario-tested insight and practical tools needed to make those high-stakes 2026 decisions with confidence.
For detailed analysis of this topic, please visit the official page: Hydrogen Cyanide (HCN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Aluminum Plating Machine Market to reach USD 547.4M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-07-09
Vacuum Aluminum Plating Machine Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market study on Vacuum Aluminum Plating Machines provides a strategic, decision‑ready view for executives planning capital allocation, technology choices, and go‑to‑market moves in 2026. The market has moved from a niche industrial capability into a mainstream finishing technology: total industry revenues expanded from roughly USD 180 million in 2020 to about USD 303 million in 2025, and our forecast shows persistent expansion through the 2026–2032 horizon, reaching an estimated USD 547 million by 2032 at a compounded annual growth rate (CAGR) of 8.9%. These topline dynamics create both opportunity and urgency for manufacturers, component suppliers, integrators, and investors.
Vacuum Aluminum Plating Machine Market
Why this study matters for 2026 decisions
-
Timing of capital deployment — With the market on an 8.9% growth path and regulatory timelines accelerating in key geographies, 2026 is a window in which timely equipment upgrades translate directly into avoided compliance risk and first‑mover margin advantage. Our analysis converts market growth and regulation timelines into explicit investment priorities and payback horizons for CFOs and plant managers.
Vacuum Aluminum Plating Machine Market -
Technology selection under cost and compliance pressures — Vacuum aluminum metallizing sits at the intersection of process engineering, environmental regulation, and product aesthetics. The report synthesizes comparative technology tradeoffs (e.g., thermal evaporation, magnetron sputtering, cathodic arc, PVD enhancements) into practical selection matrices keyed to throughput, finish quality, energy profile, and emissions compliance.
Vacuum Aluminum Plating Machine Market -
Supplier strategy and service economics — Given the market’s moderate concentration (the top three players account for a majority share and the top five substantially more), procurement teams must balance scale advantages (reliability, installed base, financing) against the cost and innovation momentum of regional vendors. Our competitor scorecards and procurement playbook help companies negotiate T&Cs, service SLAs, and spare parts strategies that materially affect lifecycle cost.
-
Regulatory and transition risk — Recent changes in air quality and solvent‑use regulations (notably updates to the EPA Clean Air Act frameworks, EU VOC directives, and region‑specific standards such as China’s national emission rules and CARB requirements) are accelerating migration away from wet chemical plating toward vacuum technologies. The study lays out compliance pathways that minimize shutdown risk and provide timelines to meet escalating enforcement.
What the report delivers — operationally focused content
-
Market sizing and trend analysis: a transparent, audit‑ready topline and historical series (2020–2025) with modelled forecasts to 2032. The forecast embeds demand drivers such as packaging automation, electronics finishing, and automotive lighting trends, and tests scenarios for macro slowdown or accelerated regulation.
-
Practical CapEx & OpEx modelling: downloadable templates and scenario calculators that let you model payback for machine classes across throughput bands and automation levels, including sensitivity to raw material (metal wire) prices and labor intensity associated with loading/unloading processes.
-
Vendor benchmarking and procurement playbooks: standardized scorecards for technical fit, service coverage, lead times, financing options, after‑sales support, and total cost of ownership. These are designed to be used in RFPs and supplier workshops.
-
Regulatory compliance playbook: timelines and mitigation steps tied to jurisdictional actions so you can prioritize retrofits vs. greenfield investments and quantify the benefits of replacing wet processes with vacuum aluminum metallizing.
-
Go‑to‑market and M&A roadmaps: strategic options for incumbent OEMs, contract coaters, captive finishers, and private equity — including bolt‑on targets and capability gaps that unlock margin expansion or rapid revenue growth.
-
Risk matrices and scenario planning: operational, supply chain and policy risks with recommended contingency actions and trigger points for reassessment.
Competitive landscape — how to read vendor dynamics
The competitive field combines specialist equipment manufacturers with vertically integrated regional players. Leading Western specialists provide high‑spec sputtering and evaporation systems optimized for high‑brightness reflectors and automotive lighting, while a set of Asia‑based firms offer broad portfolios that include PVD thermal evaporation, multi‑arc coating, and roll‑to‑roll metallizing geared to plastics and films.
-
Mustang Vac (United States) — a specialist oriented to high‑brightness reflectors, automotive lighting and decorative functional coatings. Strengths include domain expertise for high‑value optical applications and deep service relationships in OEM channels.
-
Shanghai Royal Technology Inc. (China) — rapidly positioning itself with next‑generation PVD and decorative chrome/color coating equipment as alternatives to traditional electroplating. Recent 2026 product activity (catalog updates, product optimization announcements, and a Generation III high‑vacuum deposition machine targeted at forensic and premium decorative applications) signals an aggressive push into higher‑margin applications and compliance‑friendly solutions.
-
Guangdong Zhenhua, Atop Industry, Zhaoqing Kerun, Lanzhou Vacuum and HCVAC (China and regional players) — together they form a technology and price competitive cluster that supplies a wide range of evaporation, sputtering, and vacuum metalizing lines. Their strengths lie in cost competitiveness, customization for local supply chains, and integrated production lines for plastics, films and mirrors.
Strategic takeaway: buyers should view supplier choice as a multidimensional decision (technical fit, service footprint, financing, upgrade path). The market concentration metrics in our study show a moderate level of supplier dominance at the top, but meaningful capability and price competition among regional vendors — creating opportunities for selective outsourcing or dual‑sourcing strategies.
Key dynamics that will shape competitive advantage in 2026
-
Regulatory acceleration — Legislative and standards pressure is shifting demand from solvent‑based wet finishes to vacuum technologies. Companies that map their compliance roadmap to equipment procurement timelines will reduce retrofit costs and secure capacity advantages.
-
Capital intensity and financing innovation — A typical upgrade or greenfield cell attracts significant capex (industry references suggest equipment and infrastructure investments commonly range from several hundred thousand to multiple millions of USD per facility). This creates demand for vendor financing, lease models, and performance‑based contracts; buyers who negotiate such structures improve near‑term cash flow while preserving long‑term upside.
-
Labor and process automation — Aluminum metallizing retains labor‑intensive steps (metal wire handling, vacuum chamber fixtures, manual loading/unloading). Automation and modular line designs will be decisive in reducing unit labour costs and improving throughput predictability, particularly for high‑volume packaging and electronics applications.
-
Product differentiation via material science and finishes — New PVD color and chrome processes, and hybrid workflows that combine sputtering with downstream treatments, are opening premium niches where finish quality commands significant price premiums.
-
Aftermarket and service economy — Spare parts, consumables, and proactive maintenance contracts represent a persistent revenue stream. Suppliers that build robust remote monitoring and predictive maintenance capabilities will capture higher lifecycle margins and create switching costs for customers.
Actionable next steps for corporate decision‑makers in 2026
-
Run a rapid CapEx prioritization exercise using our payback templates to identify which production lines to upgrade in 2026 versus 2027–2028, incorporating local regulatory deadlines.
-
Implement a supplier dual‑track RFP: engage a proven Western specialist for high‑value optical/automotive lines while soliciting competitive bids from regional OEMs for volume and cost‑sensitive lines.
-
Pursue modular automation investments to lower labor intensity in loading/unloading operations and to future‑proof lines against rising labour costs.
-
Negotiate performance‑linked financing with equipment vendors to preserve liquidity while meeting near‑term compliance obligations.
-
Assess M&A targets in adjacent services — spare parts distributors, remote‑monitoring platforms, and specialty consumables — to rapidly build aftermarket capabilities.
How PW Consulting helps
This introduction outlines the strategic context and operational levers that matter in 2026. The full PW Consulting report contains the granular market tables, proprietary segment models, region‑ and application‑level forecasts, supplier scorecards, and downloadable financial models you need to execute. We intentionally present the strategic insight here while reserving the full segment tables and vendor scorecards for the complete report and interactive briefing.
Contact PW Consulting for a tailored executive briefing that maps the report findings to your facility footprint, product mix, and regulatory context — or access the full study to obtain the detailed segment-level intelligence, pricing grids, and supplier negotiation templates required to act with confidence this year.
For detailed analysis of this topic, please visit the official page: Vacuum Aluminum Plating Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com