

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Advanced IC Packaging Equipment Market Poised for 12.5% CAGR Through 2032

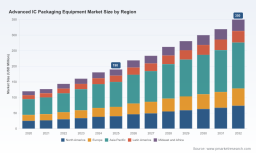
Advanced IC Packaging Equipment Market: Strategic Imperatives for 2026 Decision‑Makers
This briefing introduces PW Consulting’s Advanced IC Packaging Equipment Market study — a practical, decision‑focused analysis designed for executives who must set technology, capital‑investment, and supply‑chain strategy in 2026. Built on a 2025 base year with a historical window covering 2020–2025 and a forward view to 2032, the study frames opportunities and risks for equipment OEMs, OSATs, IDM packaging groups, private equity investors, and national policy planners. At the macro level, the market is forecast to expand from approximately USD 190 Million (base year 2025) to roughly USD 350 Million by 2032, representing a compound annual growth rate of about 12.5% — a pace that signals meaningful capital redeployment and technology refresh cycles across the ecosystem.
Advanced IC Packaging Equipment Market
Why this study matters in 2026
-
Technology inflection: Advanced packaging has moved from a performance differentiator to a foundational enabler for AI accelerators, high‑bandwidth memory (HBM), and heterogeneous system integration. Industry indicators show a majority of AI accelerator shipments already leveraging advanced packaging formats, driving demand for fine‑pitch interconnects and hybrid bonding process tools.
Advanced IC Packaging Equipment Market -
Policy and capital: Public programs (for example, national semiconductor initiatives awarded to packaging projects) and fresh private investments are de‑risking domestic capacity builds. That shift is creating windows for suppliers and OSATs to secure subsidies, but it also compresses timelines for equipment qualification and factory ramp‑up.
Advanced IC Packaging Equipment Market -
Market economics: The projected mid‑teens CAGR for equipment demand outpaces many adjacent semiconductor capital categories, reflecting both unit volume growth and significant per‑unit price escalation tied to higher automation, metrology integration, and yield enhancement capabilities.
Key market dynamics shaping buyer choices
-
Integration complexity: The move to multi‑die and silicon‑interposer solutions elevates requirements for precision dicing, thinning, hybrid bonding, and wafer‑level assembly. Buyers must prioritize equipment that integrates metrology and in‑line inspection to contain yield loss as overlay and planarity tolerances tighten.
-
Throughput vs. fidelity tradeoffs: As device architectures push pitch and density limits, the classic tradeoff between throughput and process fidelity becomes strategic. Early adopters of process platforms that maintain yield at scale will extract the largest marginal returns during the 2026–2029 ramp.
-
Automation and labor dynamics: Rising labor costs and workforce shortages in key geographies are increasing the value of robotics and end‑to‑end automation. Capital allocation should reflect not only machine cost but operational expense savings and reduced qualification time through standardization.
-
Supply resilience and localization: Geopolitical dynamics are prompting OSATs and IDMs to diversify equipment sourcing and to seek regional redundancy. Supplier selection today must factor export controls, spare‑parts logistics, and the ability to establish local service footprints.
-
Materials and process validation timelines: Raw‑material availability and incremental process windows (e.g., for new plating chemistries or thermal interface materials) are increasingly rate‑limiting. The most competitive equipment suppliers are those that partner upstream with materials vendors to accelerate qualification.
What the PW Consulting study delivers (practical, executable content)
-
Forward‑looking market sizing and demand modeling: a disciplined baseline (2020–2025) and a scenario‑based projection (2026–2032) that translate technology adoption curves into equipment spend profiles.
-
Technology and process roadmaps: mapping of key equipment classes to packaging architectures (e.g., wafer‑level, fan‑out, 2.5D/3D) and expected lifecycle timing for next‑generation modules.
-
Procurement playbook: specification templates, qualification checkpoints, and total cost of ownership (TCO) calculators designed for procurement teams to accelerate RFQs and reduce vendor selection risk.
-
CapEx phasing models and ROI scenarios: interactive frameworks showing how different mix choices (automation intensity, throughput targets, local vs. external service models) affect payback timelines.
-
Supplier scorecards and negotiation levers: qualitative and quantitative criteria to rank suppliers across technical capability, installed base, service network, and roadmap alignment.
-
Risk heatmaps and mitigation playbooks: regulatory exposures, critical‑spare dependencies, and geopolitical scenarios with prioritized mitigation actions for 12–36 month horizons.
Competitive landscape — reading supplier intent and capacity
Our study synthesizes public disclosures, engineering footprints, and product roadmaps to generate commercially actionable insight on leading equipment suppliers. Some strategic themes emerge across the competitive set:
-
Specialists with domain depth: Firms focused on discrete process steps (for example, wafer singulation, precision dicing, or molding) continue to command premium positions where process tolerance is the primary bottleneck. These vendors preserve margin by owning critical process IP and providing turnkey qualification support.
-
System integrators and platform players: Larger suppliers that bundle metrology, bonding, and fine‑line redistribution (RDL) solutions are positioning to sell higher‑value, fully integrated lines, shortening time‑to‑yield for customers but increasing supplier lock‑in risk for buyers.
-
Robotics and automation entrants: Companies delivering high‑precision handling and pick‑and‑place systems are increasingly central to packaging lines as vendors seek to automate labor‑intensive steps and reduce footprint.
-
Geographic strategy: Some OEMs are extending manufacturing capacity in target regions to better serve local OSAT ecosystems; others are doubling down on R&D and advanced process centers to protect IP and foster co‑development.
Highlights on named competitors (directional, strategic implications):
-
PacTech — laser and wafer‑level assembly specialist: strong in laser soldering and wafer‑level ball placement; attractive partner for OSATs pursuing heterogeneous integration pathways.
-
DISCO Corporation — precision singulation and grinding leader: foundational for 3D/2.5D flows where thinning and singulation determine yield. Their product maturity shortens qualification timelines.
-
Kulicke & Soffa — assembly and bonding breadth: combines bonding platforms with lithography tools for fan‑out and other advanced processes, enabling end‑to‑end assembly solutions.
-
BESI — focused on wafer‑level and hybrid bonding processes: advantaged where substrate and leadframe variety requires adaptable assembly equipment.
-
Applied Materials — materials engineering and hybrid bonding scale: recent strategic acquisitions broadened their plug‑and‑play portfolio for heterogeneous integration, accelerating their competitiveness in pilot‑to‑production transitions.
-
SUSS MicroTec, TOWA, Yamaha Robotics, Tokyo Seimitsu, Advantest, HANMI — each brings distinct strengths across lithography, molding, robotics, grinding, test, and AI/HBM oriented packaging tools. Buyers should prefer multi‑vendor collaboration models where no single OEM covers all specialized process steps.
Recent developments shaping near‑term strategy
-
Strategic R&D and facility moves: Industry announcements in 2025–2026 — new plants, rebranding and consolidation of bonding lines, and the opening of innovation centers — reflect supplier investments in production capacity and customer co‑development. These moves shorten qualification cycles and improve responsiveness for early‑stage pilots.
-
M&A and team integrations: Acquisitions that merge niche teams into larger semiconductor groups change the competitive topology, creating more vertically integrated suppliers that can offer bundled solutions, but sometimes at the cost of reduced outside interoperability.
-
Public funding: National semiconductor programs that include packaging initiatives materially affect where new capacity will be placed and which suppliers will be favored for local content requirements.
How to translate insight into 2026 action
-
Prioritize pilot investments now: Allocate a meaningful portion of 2026 process‑development budgets to pilot lines that validate hybrid bonding, high‑density RDL, and HBM assembly. Early qualification wins shorten time‑to‑volume in 2027–2029.
-
Design for supplier modularity: When specifying equipment, insist on open interfaces and clear IP handover paths to avoid technical lock‑in while still capturing the operational benefits of integrated systems.
-
Negotiate performance‑based contracts: Shift procurement toward outcome‑based SLAs that tie payment and warranty terms to throughput and yield milestones during ramp phases.
-
Use scenario planning: Develop three prioritized scenarios (baseline demand growth, accelerated AI adoption, and fragmented/regulatory constrained supply) and stress‑test capex and sourcing plans against each.
-
Leverage public incentives strategically: Target grants and subsidies for the riskiest qualification stages (materials/process validation) while using commercial capital to scale later stages.
Closing — where to go next
The Advanced IC Packaging Equipment Market will be a high‑velocity domain between 2026 and 2032. For executives, the imperative is clear: move beyond vendor claims to quantify how equipment choices affect yield, time‑to‑volume, and unit economics across plausible demand scenarios. PW Consulting’s full report provides the granular segmentation, supplier scorecards, and downloadable CapEx models that practitioners need to convert strategy into executable programs. For the complete datasets, detailed segmentation, and executable procurement templates, please refer to the report’s primary access channel.
For detailed analysis of this topic, please visit the official page: Advanced IC Packaging Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com