

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Palletizing Machine Market to Grow at 6.12% CAGR, Reaching USD 466.6M by 2032

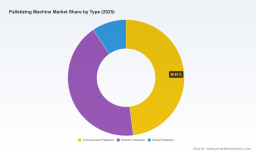
Palletizing Machine Market — Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s latest Palletizing Machine Market study (base year 2025) synthesizes seven years of market dynamics and a seven‑year forward view to deliver decision-ready intelligence for executives planning capital allocation, automation roadmaps, and supply‑chain strategies in 2026. The market has demonstrated steady expansion through 2020–2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.12% over the 2026–2032 forecast window. This research is designed as a strategic playbook: it surfaces the structural moves, technological inflection points, and procurement levers that matter this year, while preserving granular segment data for licensed subscribers who require the complete dataset and vendor-level benchmarking.
Palletizing Machine Market
Market Trajectory and Strategic Context
After a measured recovery and modernization cycle in the first half of the decade, the palletizing market has moved from being a pure mechanical stacker industry into a hybrid ecosystem of robotics, collaborative automation, AI‑enabled mixed palletizing, and integrated warehouse controls. Our macro sizing shows clear momentum continuing into the next growth phase, driven by rising labor costs, SKU proliferation, tighter sustainability targets, and the increasing economics of automation for mid‑sized plants. PW Consulting’s forecast through 2032 captures how these forces compound into capital investment opportunities and operational tradeoffs that are actionable in 2026 procurement cycles.
Palletizing Machine Market
Why 2026 Is a Pivotal Decision Year
- Regulatory reset: Updated international machine‑safety standards (ISO 10218:2025) and regional palletizer safety standards (EN 415‑4:2025) materially affect cell design, validation time, and vendor certification requirements—risking schedule slips for non‑compliant retrofits.
- Labor economics: Rising labor cost baselines—illustrated by median operating wages and fully loaded cost statistics in key markets—shorten payback windows for automation and make staged rollout plans more attractive for 2026 budgets.
- Technology inflection: Cobot families and AI‑augmented mixed palletizers launched across 2025–2026 change the implementation calculus: lower‑risk pilots are now viable on lines with moderate throughput and high SKU mix.
- Integration premium: Buyers increasingly value systems that integrate controls, warehouse management, and upstream packaging lines to minimize downtime and accelerate changeover—making integrator selection as important as robot selection.
What the Full Report Delivers (Practical, Actionable Contents)
Our study is designed to convert insight into action. Highlights of the deliverables that drive 2026 decision processes include:
Palletizing Machine Market
- Proven market‑sizing methodology, with historical reconciliation (2020–2025) and scenario‑based forecasts for 2026–2032.
- Demand driver analysis (labor, e‑commerce, SKU proliferation, sustainability) and sensitivity modeling to test capex under multiple labor and component‑cost scenarios.
- Segmentation by technology, application, and region (subscriber access provides the full split tables and trend matrices).
- Vendor scorecards and a procurement playbook: RFP templates, evaluation criteria, SLA and warranty negotiation points.
- Implementation artifacts: pilot KPIs, changeover and uptime benchmarks, commissioning checklists, and plant‑level TCO calculators.
- Compliance and safety gap analysis mapped to ISO 10218:2025 and EN 415‑4:2025, with remediation roadmaps and estimated lead times.
- Technology roadmap and competitive threat matrix: robotics, cobots, AI mixed palletizing, and conveyor‑driven solutions.
- M&A and partnership pipeline mapping for strategic buyers and financial sponsors, including comp tables and integration playbooks.
Competitive Landscape — Who Moves Markets and Why
The palletizing ecosystem now includes classic robotics OEMs, turnkey system integrators, packaging specialists, and agile modular vendors. Market concentration remains moderate: the top players capture a material but not dominating share, leaving ample opportunity for specialized entrants and regional integrators.
- Robotics OEMs (ABB, KUKA, FANUC, Yaskawa): These incumbents continue to extend payloads, cycle speeds, and cell controllers. Recent product activity—such as collaborative‑grade releases and refreshed cobot families—lowers entry barriers for collaborative palletizing in mixed‑SKU environments and accelerates retrofits where footprint or personnel proximity is a constraint.
- System integrators and material‑handling leaders (Krones, BEUMER Group, Honeywell Intelligrated, FlexLink): These firms sell integrated lines and value throughput guarantees. Their competitive advantage is the end‑to‑end control stack and the ability to reduce integration risk for complex beverage, food, and consumer goods lines.
- Packaging and specialized palletizer vendors (A‑B‑C Packaging, Columbia Machine, Symach, Schneider Packaging, TopTier, NOVA Automation): These players excel at specific use cases—high‑speed cases, bundle/tier arrangements or compact cell footprints—and are frequent targets for strategic partnerships as OEMs seek to broaden portfolios.
- Modular and software‑first entrants (Vention, FlexLink): Agile platforms and AI‑driven mixed palletizing solutions are creating new procurement models (shorter lead times, subscription software, modular expansion) that can materially reduce time‑to‑value.
Recent market activity illustrates these shifts. Product launches across 2025–2026 introduced enhanced collaborative ergonomics and AI capability in palletizing lines; major vendors doubled down on cobot variants and mixed palletizer solutions showcased at global trade events. These innovations shorten pilot cycles but raise the bar for safety certification and control‑system compatibility.
Implications for Procurement, Operations and Technology Strategy
Your 2026 decisions should be organized around three strategic priorities:
- Modularity and optionality: Favor architectures that enable phased investment—start with cobot or single‑robot pilots and scale to full robotic or mixed palletizing cells as ROI is proven.
- Standards‑first design: Build compliance to ISO 10218:2025 and EN 415‑4:2025 into procurement specs to avoid retrofit risk and commissioning delays.
- Integration over components: Prioritize suppliers or integrators that provide demonstrable controls and WMS integration, not just hardware. Integration eliminates hidden costs associated with changeovers and software interoperability.
Practical Recommendations — A 2026 Playbook
- Run two parallel pilots this year: one cobot/low‑infeed line to prove economics, one full automation line for high throughput—compare payback under conservative labor inflation scenarios.
- Use our vendor scorecard to shortlist integrators who commit to safety certification timelines and provide spare‑parts availability guarantees.
- Request application‑specific TCO models that include commissioning, spare parts, planned downtime, and staff upskilling—avoid vendor quotes that list hardware only.
- Design contracts with options for modular expansion and software upgrades to capture future AI and mixed‑SKU capability without rip‑and‑replace.
- Include cybersecurity and control‑system isolation requirements in RFPs for new palletizing cells to protect upstream ERP/WMS integrations.
- Consider leasing or outcome‑based contracts where capex is constrained and where vendors can deliver uptime guarantees tied to performance.
Use Cases and ROI Patterns
We observe consistent ROI patterns across sectors: labor‑intensive, high‑SKU lines and 24/7 operations deliver the fastest paybacks; beverage and e‑commerce packing centers frequently capture early wins through layer‑forming automation and mixed palletizing. The report contains customizable ROI templates that allow you to model payback under different throughput, labor, and capital cost assumptions—critical for board‑level capex approvals in 2026.
Why PW Consulting — Research Rigor and Client Utility
Our approach combines proprietary shipment and install datasets, primary interviews with OEMs and integrators, and stakeholder workshops in manufacturing, warehousing, and procurement. We map regulatory change to implementation timelines, quantify vendor positioning, and produce client‑ready artifacts—RFPs, compliance checklists, and scenario‑based capex models—so that procurement, operations, and digital transformation leaders can act decisively this year.
To preserve strategic value for our clients, this preview intentionally omits the full segment and vendor revenue tables, regional and application splits, and the detailed vendor financial benchmarking. The full dataset and actionable appendices—complete segmentation, CR‑based market shares, vendor scorecards, and the downloadable ROI/TCO tools—are available through PW Consulting’s market page and subscription channels.
Contact PW Consulting to obtain the complete Palletizing Machine Market report, schedule a tailored briefing for your executive team, or request the interactive ROI workbook to stress‑test acquisition scenarios for 2026.
For detailed analysis of this topic, please visit the official page: Palletizing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com