

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AFM Market to Reach USD 862.0M by 2032 on 7.1% CAGR

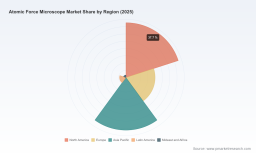
Atomic Force Microscope Market — Strategic Preview for 2026 Decisions
Executive overview
As organizations finalize capex, R&D roadmaps, and partnership strategies for 2026, a clear, evidence-based view of the Atomic Force Microscope (AFM) market is a strategic asset. Our PW Consulting market synthesis shows a resilient, mid-single-digit-to-high-single-digit growth profile rooted in accelerating demand across semiconductor metrology, materials science, and bio-nanotechnology. From 2020 through our base year of 2025, the AFM market expanded meaningfully, and our forecast through 2032 anticipates sustained growth at a compound annual growth rate (CAGR) of 7.1%, taking the total market from the mid-hundreds of millions (USD) in 2025 to a substantially larger market by 2032.
Atomic Force Microscope Market
This preview distills the implications of that trajectory for strategic planners — what it means for product roadmaps, manufacturing footprints, channel approaches, and M&A prioritization — while intentionally withholding granular subsegment tables that are included in the full PW Consulting report. Think of this as the trailer: deep enough to orient and provoke action, but designed to drive decision-makers to the full analysis for executable specifics.
Atomic Force Microscope Market
Market trajectory & what it signals for 2026
-
Momentum and scale: The AFM market has shown steady expansion across the historical period (2020–2025) and enters 2026 from a position of strengthened demand. Our modeling projects a steady climb through the forecast window (2026–2032), with the market approaching nearly double-digit relative gains in critical years driven by sequential advances in semiconductor packaging, advanced materials, and integrated life-science workflows.
Atomic Force Microscope Market -
Concentration and competitive dynamics: The market exhibits moderate-to-high concentration among leading players; our concentration metrics indicate that the top three firms account for a dominant share of the market, with the top five firms together capturing the bulk of global revenues. This structure has three practical consequences for 2026 planning: pricing power at the top, attractive niches for focused challengers, and an active M&A backdrop as companies seek capability-based consolidation.
-
Technology-driven upsell: Recent advances in probe fabrication, multimodal AFM modalities, and Raman-coupled systems are converting single-purpose AFMs into platform assets. These technology developments not only expand addressable applications but also increase average selling price (ASP) and lifecycle spend via consumables and software — a critical consideration for vendors and buyers negotiating multi-year support contracts in 2026.
Five strategic implications for 2026 decision-makers
-
Prioritize modular, upgradeable platforms. With rapid modality innovation (e.g., multimodal mechanical characterization and Raman-AFM integrations), buyers and vendors who emphasize modularity capture lifecycle revenue and reduce obsolescence risk. R&D and procurement teams should require upgrade paths and software-forward roadmaps in procurement RFPs.
-
Build resilience into supply chains. Non-tariff barriers, export-control frictions, and logistics delays are causing months-long disruptions in some corridors. Suppliers should diversify sourcing for critical components (probes, scanners, control electronics) and map regulatory timelines into product launch schedules; buyers should factor extended lead times into project plans for 2026.
-
Capture adjacent value in services and consumables. The market’s trajectory supports shifting commercial models from one-time instrument sales to subscription-like service bundles (maintenance, analytics, consumables). Manufacturers can increase customer lifetime value by bundling predictive maintenance, remote diagnostics, and spare-part pipelines for large-sample platforms.
-
Target high-growth application intersections. While we do not disclose granular subsegment share in this preview, our full report highlights which application intersections are growing fastest. Strategic investors should focus on offerings that address combined needs — for example, semiconductor process control paired with high-throughput wafer inspection, or Raman-coupled AFM for chemically-sensitive materials research.
-
Use concentration dynamics to shape M&A and partner playbooks. Leaders with strong installed bases are investing in ecosystem plays (software, probes, service networks). For challengers, partnering with specialized platform providers or acquiring capability-focused startups can be a faster route to competing effectively in 2026.
Competitive landscape — what matters in 2026
Leading vendors remain differentiated by a mix of platform breadth, application specialization, and service ecosystems. Key players we profile in the full study include established instrument manufacturers, niche innovators, and vertically integrated metrology firms. Strategic takeaways by capability:
-
Platform breadth and metrology integration: Firms offering families of AFM instruments across research and industrial grade systems maintain advantage in enterprise procurement cycles where compatibility with legacy workflows and cross-center standardization matter.
-
Application specialization: Vendors that pair AFM systems with domain-specific software (e.g., battery research suites, semiconductor defect-classification workflows, or bio-AFM protocols) unlock premium pricing and stickiness.
-
Service and user community: Companies that invest in training, user conferences, and open instrument programmability cultivate ecosystems that accelerate adoption—evidenced by vendor-hosted conferences and interactive showcases in recent years.
Notable vendor actions and signals observed through 2025–2026 include product launches aimed at semiconductor metrology, expanded catalogues targeting wafer-scale inspection, and platform showcases that emphasize large-sample automation and autonomous operation. Several vendors have also emphasized quality certifications and manufacturing standardization to reassure enterprise buyers.
Technology and regulation — risk and opportunity zones
-
Probe and fabrication innovation: October 2025 demonstrations of batch-fabricated ultra-sharp probes point to falling costs and improved throughput for high-precision imaging. This reduces a key cost barrier for routine nanoscale metrology — accelerating deployment in industrial settings.
-
Multimodal convergence: January 2026 work applying multimodal AFM to advanced packaging materials demonstrates growing relevance for AFM in heterogeneous integration and hybrid bonding quality assurance — a clear demand signal for semiconductor equipment buyers.
-
Standards and compliance: Recent ISO certifications and evolving import safety standards are raising the bar for manufacturing quality and documentation. Suppliers should pre-empt regulatory friction by embedding compliance into design controls and export readiness programs.
What the full PW Consulting report delivers (practical components)
The full market study is designed as an operational playbook for procurement leads, product executives, investors, and strategy teams. Core deliverables include:
-
Granular market sizing and validated forecasts (historical 2020–2025 base and forecast 2026–2032), with scenario modelling across technology and regulatory pathways;
-
Segmentation deep-dives (by region, instrument type, and application) with detailed subsegment tables and growth drivers; note: these granular splits are purposefully omitted from this preview to preserve the report’s proprietary value;
-
Vendor benchmarking and capability maps (product portfolios, service models, installed base estimates, and route-to-market analysis);
-
Commercial playbooks for market entry and expansion — including pricing benchmarks, channel design, and consumables monetization templates;
-
Supply chain and regulatory risk register with mitigation levers;
-
M&A and partnership heatmaps to inform near-term deal screening and joint-venture design;
-
Practical annexes — procurement checklists, RFP language templates, and an implementation roadmap for 12–36 month horizons.
How to act on this preview in Q1–Q2 2026
-
For buyers (corporate R&D & fabs): Initiate supplier audits that prioritize upgradeability and service SLAs. Build lead-time buffers into equipment procurement timelines and require demonstrable regulatory readiness in supplier contracts.
-
For vendors: Accelerate modularity in product roadmaps, double down on consumables and software revenue plays, and formalize compliance pipelines to shorten customer procurement cycles.
-
For investors and corporates considering M&A: Use market concentration metrics and capability matrices to prioritize targets that close platform gaps or bring differentiated application IP — and validate these choices against our scenario-modeled demand curves.
Closing — why this matters for your 2026 strategy
The AFM market’s steady expansion and technological momentum create both opportunities and execution risks in 2026. Companies that treat AFM investments as strategic platform decisions — aligning procurement, product design, and service monetization — will capture disproportionate value as the market scales. Our full PW Consulting report provides the tables, segment-level growth rates, vendor scorecards, and executable templates you need to translate the market’s macro trends into operational outcomes.
To access the comprehensive datasets, subsegment breakdowns, vendor profiles, and the decision-useful annexes (including the procurement RFP templates and M&A heatmap), please consult the full Atomic Force Microscope Market report on our website. This preview deliberately omits proprietary subsegment detail to preserve the report’s tactical utility for subscribing clients.
For detailed analysis of this topic, please visit the official page: Atomic Force Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com