

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dot Peen Marking Market to Reach USD 615.4M by 2032 at 6.5% CAGR

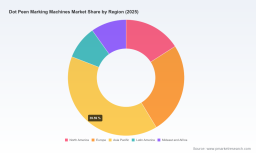
Dot Peen Marking Machines Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As manufacturers and traceability-focused stakeholders prepare capital and product decisions for 2026, the dot peen marking machines market presents a predictable, resilient growth story — but one that rewards targeted strategy more than broad optimism. Our new PW Consulting industry primer synthesizes five years of historical performance (2020–2025) and a forward-looking scenario through 2032 to translate market momentum into actionable choices. The market expanded from approximately USD 295 million in 2020 to about USD 399 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of roughly 6.5% through the forecast window, reaching an estimated USD 615 million by 2032. These topline dynamics create distinct windows for product innovation, channel reorientation, and consolidation plays — each explored at a level designed to inform boardroom decisions while reserving the granular segmentation tables and source datasets for the full report.
Dot Peen Marking Machines Market
Why 2026 is a strategic inflection point
Two converging phenomena make 2026 uniquely consequential. First, regulatory and quality frameworks (medical device MDR/UDI, automotive IATF 16949, aerospace AS9100, and public sector traceability procurement rules) are maturing, converting compliance needs into recurring demand for permanent, verifiable marking. Second, operational modernization across factory floors — from serialized traceability to embedded track-and-trace in automated production lines — is accelerating buyers' preference for integrated and networked marking solutions. Taken together, these drivers shift vendor evaluation criteria from basic hardware reliability to lifecycle services, software interoperability, and data assurance.
Dot Peen Marking Machines Market
Market dynamics and growth drivers
- Regulatory-led baseline demand: Dot peen marking is explicitly referenced in multiple regulatory and standards contexts for traceability and durability; this regulatory tailwind underpins steady baseline growth rather than one-off purchases.
- Industry diversification: Traditional heavy-industry and automotive use remains important, while aerospace, medical device manufacturing, and precision electronics contribute above-average quality and traceability requirements, expanding the addressable market for higher-specification machines.
- Shift toward portable and line-integrated solutions: Buyers increasingly value flexibility — portable, battery-operated units for field servicing and compact, integrated systems for in-line serialisation. This bifurcation invites differentiated product roadmaps.
- Aftermarket and software monetization: As marking becomes a node in digital traceability loops, software modules for data capture, audit-ready logs, and predictive maintenance create recurring revenue opportunities that outsize hardware margins.
- Technical substitution risk: Laser marking continues to encroach on some higher-volume and non-ferrous applications. Dot peen retains advantages in depth, permanence, and cost-per-mark for many metallic components, but vendors must articulate a defensible value proposition.
- Validation and durability requirements: Proven resistance to abrasion and corrosion (e.g., salt spray standards) and compatibility with customer quality regimes materially influence procurement choices.
Competitive landscape: who matters and why
The market remains moderately fragmented: the top three suppliers control a meaningful but not dominant share, and the top five increase concentration only modestly — a structure that supports both organic positioning and opportunistic M&A. Competitors can be grouped by capability and strategic posture:
Dot Peen Marking Machines Market
- Pryor Marking Machines (Sheffield, UK): Niche specialist known for low-stress permanent marking; appeals to customers where material integrity matters. Strength: specification-led engineering and British manufacturing pedigree.
- MarkinBox (Tokyo, Japan / MB Metal Technologies): Japanese engineering quality with a portfolio spanning portable and line-integrated solutions; plays well to East Asian OEMs and precision manufacturers focused on reliability.
- Telesis Technologies (USA): Rugged product lines designed for industrial production environments (e.g., PINSTAMP, BenchMark). Strength: robustness and established line-integration credentials for high-throughput shops.
- Brady (formerly MECCO) (USA): Offers deep and fast marking systems targeting heavy fabrication and metalworking sectors; active in trade shows demonstrating product breadth and new pin/laser hybrids.
- Pannier Corporation (USA): Focus on battery-operated and portable models for traceability in field and shop-floor contexts; strong aftermarket and field-service positioning.
- Kwik Mark Inc. (USA): Compact benchtop and heavy-duty offerings for tag and plate marking — appeals to mid-market fabricators and labeling houses.
- Automator Marking Systems (Italy): Long heritage in portable, production-integrable markers; European OEM relationships and legacy service networks are strategic assets.
- SIC Marking & Gravotech (France): Multi-technology players that pair dot peen with lasers and scribe options; their systems approach and regulatory positioning make them preferred suppliers for complex traceability programs.
- TechnoMark Inc. (USA): Emphasizes seamless production-line integration and compliance-driven marking solutions, with market traction in oil and gas and industrial tooling where standards enforcement is strict.
- CNMarking (China): Cost-competitive electric and pneumatic offerings targeted at automotive and component suppliers; pressure on price-sensitive procurement channels is a persistent competitive factor.
Recent trade-show activity — for example, Brady’s visible presence at major industry events and other exhibitors demonstrating hybrid marking capabilities — signals that incumbents are investing in both product evolution and channel visibility. These market signals are important leading indicators for procurement cycles and competitive responses in 2026.
Strategic implications for 2026 decision-making
- For OEMs and large end-users: Treat marking as a systems decision, not a point purchase. Prioritize suppliers that offer validated compliance outputs (audit-ready logs, standardized mark verification), integration APIs, and a clear roadmap for software-driven services. Consider multi-vendor pilots to stress-test in-line performance under real production tolerances.
- For manufacturers and suppliers: Differentiate on software and services. Hardware alone will compete increasingly on price. Invest in remote diagnostics, subscription-based maintenance, and modules that capture traceability metadata to create annuity streams.
- For investors and private equity: The market’s moderate concentration suggests ripe opportunities for roll-up strategies — combine regional specialists with software enablers and aftermarket platforms to create scale and margin expansion. Target companies with installed base data and service revenue potential.
- For procurement and service providers: Reassess total cost of ownership (TCO) frameworks to include mark validation, regulatory audit costs, and product lifecycle software. Lower upfront costs can be false economies when compliance and traceability audits are factored in.
- For product teams: Roadmaps should balance ruggedization (for heavy industry) and miniaturization/portability (for field service and small-batch manufacturers). Hybrid offerings that combine dot peen and laser or offer configurable heads will win proof-of-concept budgets.
What the PW Consulting report delivers — practical contents
Our market study is structured to convert insight into action. Highlights include:
- Topline market sizing and validated forecast model (2026–2032) with scenario sensitivity for substitution risk and regulatory tightening.
- Competitor dossiers and capability matrices that map product families to buyer needs, service footprints, and integration readiness.
- Regulatory and standards matrix aligning marking technologies to industry-specific compliance requirements and test protocols.
- Commercial playbooks: GTM templates, channel scorecards, price-to-service migration pathways, and aftermarket pricing strategies.
- Transaction support tools: diligence checklists, synergy quantifiers for roll-up cases, and vendor selection rubrics for strategic sourcing.
- Practical tools for operators: ROI calculators for fleet upgrades, lifecycle maintenance schedules, and a sample API data model for traceability integration.
To respect confidentiality and buyer timing, the full report retains the granular regional and application-level datasets, supplier-level share tables, and downloadable model files exclusively behind our access layer — ensuring clients gain both data and an executable plan.
How to use this research in 2026 decisions
Concrete use cases where our analysis creates value in 2026:
- CapEx prioritization: Use the forecast scenarios and TCO models to decide which lines to upgrade first, balancing volume concentration with regulatory exposure.
- Sourcing strategy: Develop supplier segmentation (core, qualified, contingency) informed by supplier capability matrices and service footprints.
- M&A diligence: Rapidly size target acquisition upside by applying our synergy templates to service cross-sell and geographic expansion levers.
- Product roadmap decisions: Allocate R&D budgets between hardware robustness improvements and software/IoT integration based on quantified demand vectors in the report.
- Compliance remediation: Map your product portfolio to standards and validation tests required by customers (e.g., medical, aerospace) to prioritize certification investments.
Conclusion and next steps
The dot peen marking market is not a high-velocity disruptor; it is a steadily growing, standards-driven market where differentiation will accrue to firms that combine durable hardware with software, services, and compliance assurance. With the aggregate market expanding from roughly USD 295 million in 2020 to near USD 399 million in 2025 and an expected rise to about USD 615 million by 2032 (CAGR ~6.5%), the next 12–18 months are prime for strategic positioning. Whether you are an incumbent supplier, a manufacturing OEM, or an investor, 2026 choices about integration, service models, and product architecture will determine who captures the higher-margin, durable segments of the industry.
For the complete datasets, supplier share tables, region- and application-level breakouts, and fully modeled forecast files used to construct these scenarios, access the full PW Consulting Dot Peen Marking Machines Market report. Our team is available to run a tailored briefing and to map these findings into a 90-day action plan aligned to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Dot Peen Marking Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com