

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Membrane Air Dryers Market Poised for 6.98% CAGR to 2032

Membrane Air Dryers Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior strategic adviser and chief industry analyst, I present a concise, practitioner‑focused preview of our full Membrane Air Dryers Market study. This briefing distills the macro trends, competitive dynamics, and high‑value strategic implications that should shape executive choices in 2026. The full report contains the granular segment-level figures, vendor scorecards, and scenario models referenced here; this preview deliberately omits those line‑by‑line data to preserve strategic value and direct stakeholders to the complete intelligence package.
Membrane Air Dryers Market
Market at a glance: scale, trajectory and concentration
Membrane air dryers are a growth market. By our base year (2025) the global market surpassed the billion‑dollar threshold (reported in USD, revenue unit: Million), and the forecast to 2032 is underpinned by a steady compound annual growth rate of 6.98% across the 2026–2032 horizon. Market concentration remains relatively low for a specialized industrial component: the top three vendors account for just over one‑fifth of market share (CR3 ~22.5%) with the top five approaching the high‑20s (CR5 ~27.8%). That competitive profile points to ongoing opportunity for differentiated entrants, regional champions, and consolidation plays.
Membrane Air Dryers Market
Why this study matters to a 2026 strategic agenda
-
Capital allocation and procurement: Procurement teams and plant managers must reconcile compressor system upgrades, point‑of‑use decisions, and replacement cycles with constrained capital budgets. Our study quantifies the projected demand envelope and operational levers that change the total cost of ownership.
Membrane Air Dryers Market -
Product and R&D prioritization: Membrane technology offers distinct trade‑offs—energy neutrality (no rotating components), compactness, and low dew point capability set against purge‑air penalties and filtration sensitivity. The report translates those trade‑offs into R&D and product roadmaps aligned with end‑market needs.
-
M&A, partnerships and aftermarket strategy: Given moderate concentration, carefully targeted acquisitions and channel partnerships unlock immediate scale, service footprints, and IP synergies. The study maps likely consolidation corridors and partner archetypes.
-
Sustainability and regulatory compliance: ISO 8573‑1 moisture classifications, regional emissions and energy mandates, and the emergent corporate net‑zero programs require operators to choose drying solutions that balance performance and lifecycle environmental impact. Our modeling links compliance outcomes to technology choice.
What’s in the full report (operationally actionable)
-
Market sizing and seven‑year forecasts (2026–2032) with scenario sensitivity to energy prices, purge‑air optimization, and tariff escalation.
-
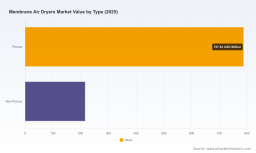
Detailed segmentation by region, product type, and application with time‑series datasets and heat maps for prioritization (note: segment tables are available in the main report only).
-
Competitive benchmarking including capability matrices, route‑to‑market analysis, and near‑term product roadmaps for leading vendors.
-
Supply‑chain risk analysis focused on membrane substrates, housing components, and filtration media; includes tariff stress tests and mitigation options (dual sourcing, relocation economics, and inventory strategies).
-
Commercial playbooks for OEMs and distributors: pricing levers, service bundling, SLAs, and retrofit economics to accelerate aftermarket revenue.
-
Technical annexes covering performance trade‑offs: dew‑point achievement, purge‑air consumption ranges, and pre‑filtration design criteria for hollow‑fiber membranes.
-
Executive decision tools: NPV calculators, capex vs. opex frameworks, and an implementation checklist for plant engineers and procurement leads.
Competitive landscape — who is shaping product and go‑to‑market moves
The market features a mix of large industrial systems suppliers and specialized niche manufacturers. Leading names to watch are:
-
Atlas Copco (Stockholm) — strong push on integrating membrane dryers into IoT and predictive maintenance ecosystems. Their SDM/SMD lines illustrate a strategy of higher‑value, integrated offerings that target energy optimization and compact installation footprints.
-
Parker Hannifin (Cleveland) — combines membrane modules with coalescing and filtration to address industrial cleanliness and longevity. Recent product introductions emphasize sustainability and low emissions as differentiators.
-
SMC Corporation (Tokyo) — positions membrane dryers for precision applications (laser processing, instrument air) where very low dew points without power supply are critical. Their product focus highlights the adjacency to pneumatic subsystem OEMs.
-
Hankison, Pentair, Festo, BEKO, Dri‑Air — each brings distinct strengths: compact industrial designs, high‑performance housings, wear‑free operation, and market specialization (e.g., low‑throughput plastics drying). These players are important partners or acquisition targets depending on your entry strategy.
Recent vendor moves underscore two themes: (1) product innovation that reduces lifecycle cost via smarter controls and lower purge rates, and (2) positioning around sustainability credentials. Notable examples include Parker’s sustainability‑focused product launch (2024), Atlas Copco’s IoT‑ready systems (2024) and later SMD announcements (2026), and Dri‑Air’s stainless‑steel MicroDryer for low‑throughput precision applications (2024).
Market dynamics that will dictate near‑term winners
-
Regulatory and quality standards: ISO 8573‑1 moisture classes govern acceptable performance metrics across industrial applications; vendors that deliver certified, verifiable performance will command premium placements.
-
Operational efficiency: membrane systems are attractive because they avoid moving parts, but they trade off purge air consumption—typical ranges must be engineered into plant air balances (purge consumption commonly falls in the 10–20% band for -40°F targets). Executives must optimize system layout and compressor loading to realize promised gains.
-
Supply‑chain pressure: rising tariffs on raw materials and components have materially increased costs for housings, fittings, and membrane substrates. Procurement organizations need near‑term mitigations (contract hedging, local sourcing) to preserve margin while avoiding service disruptions.
-
Pre‑filtration dependency: hollow‑fiber membranes are sensitive to oil and particulate contamination; effective upstream filtration architecture is a prerequisite—not an option—for sustained membrane performance and warranties.
Strategic implications and recommended priorities for 2026
Executives should treat membrane dryer decisions as system‑level choices that affect compressor sizing, plant air economics, and aftercare revenue streams. Key priorities:
-
Embed purge‑air and pre‑filtration metrics into procurement contracts. Negotiate acceptance tests and performance‑based SLAs tied to dew point and purge consumption.
-
Invest selectively in IoT and predictive maintenance capabilities that convert product upgrades into recurring service revenue. Vendors that provide real‑time monitoring reduce total cost of ownership and increase stickiness.
-
Hedge raw‑material exposure through supplier diversification or nearshoring for critical components. The report’s tariff sensitivity scenarios quantify break‑even points for reshoring vs. continued imports.
-
Pursue targeted M&A or distribution partnerships to accelerate penetration in specialized end markets (laser processing, instrument air, medical breathing air), where membrane advantages are most pronounced.
-
Prioritize lifecycle emissions and energy reporting for corporate sustainability programs—membrane solutions can be positioned as low‑energy, low‑maintenance pathways to compliance when lifecycle data is disclosed.
Five high‑impact questions for executives
-
Have we quantified the plant‑level impact of purge‑air consumption on compressor sizing and electricity spend across our sites?
-
Do our procurement terms include performance‑linked acceptance criteria (dew point, purge, uptime) and penalties for underperformance?
-
Is our supplier portfolio diversified enough to withstand tariff shocks and membrane substrate shortages?
-
Can we convert product upgrades (IoT, predictive alerts) into a defended aftermarket subscription business within 18 months?
-
Which end markets in our portfolio demand the unique benefits of membrane drying (size, no power requirement, low dew points) and how should GTM prioritize them?
Conclusion: The membrane air dryer market is mature in engineering but emergent in commercial structures. Technology differentiation, supply‑chain resilience, and aftermarket models will decide which players scale with the mid‑to‑upper single‑digit market growth projected through 2032. This preview sketches the strategic terrain and immediate imperatives; the full PW Consulting report supplies the proprietary segment datasets, supplier scorecards, and implementation tools your team will need to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: Membrane Air Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com