

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: EV Motor Controller Market to Reach USD 1,385M by 2032 at 10.3% CAGR
By pmarketresearch, 2026-07-13
Electric Vehicle Motor Controller Market — Strategic Preview for 2026 Decision-Making
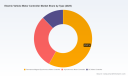
As OEMs, tier suppliers and investors set priorities for 2026, the electric vehicle (EV) motor controller value chain sits at the intersection of power-electronics innovation, materials volatility and fast-evolving regulatory regimes. Our PW Consulting market model — base year 2025 with a historical window from 2020–2025 and a forward forecast covering 2026–2032 — shows a market that expanded from USD 400 Million (2020) to USD 700 Million in 2025, and is projected to grow to approximately USD 1,385 Million by 2032 at a compound annual growth rate (CAGR) of 10.3%. These headline figures capture both the opportunity and the pressure points that will shape strategic choices in 2026.
Electric Vehicle Motor Controller Market
Why this research matters to 2026 strategy
- Timing and investment: The growth trajectory implies near-term urgency to secure technology roadmaps (SiC, 800–1,000V architectures, integrated e-axles) and to time capital expenditures so that scale advantages align with rising vehicle electrification volumes.
- Risk-adjusted sourcing: Material and tariff dynamics mean procurement strategies crafted in 2026 must prioritize multi-sourcing, vertical hedging, and supplier intelligence to avoid single-source shocks that can delay vehicle programs.
- Regulatory alignment: New vehicle electronic control mandates and changing trade measures introduce non-negotiable compliance and localization variables into sourcing, testing and product release schedules.
- Competitive positioning: The differentiated technical bets — high-frequency SiC inverters, axial-flux motors with bespoke controllers, integrated sensor-inverter systems — create asymmetric advantages for suppliers and OEMs who execute early in 2026.
What the PW Consulting report delivers (practical, executable content)
This study is designed as a decision-useful playbook for commercial and technical leaders. It synthesizes market sizing and growth scenarios with operational tools you can apply directly to 2026 planning cycles. Highlights include:
Electric Vehicle Motor Controller Market
- Market sizing and forecast model (2020–2032) in downloadable format — transparent assumptions and sensitivity levers so finance teams can re-run scenarios against different EV uptake and technology-adoption curves.
- Technology deep dives — mechanics and trade-offs for SiC versus silicon MOSFET architectures, 800V and 1,000V system implications, axial‑flux versus radial motor control challenges, and thermal-management pathways for higher power density systems.
- Supplier benchmarking — layered profiles of incumbent and emerging motor-controller suppliers, structured around product roadmaps, capacity, IP positions, manufacturing footprint and risk metrics.
- Procurement & sourcing playbooks — supplier selection frameworks, contract clause templates for performance guarantees, long‑lead components checklist and an actionable supplier-risk heat map.
- Regulatory and trade impact analysis — scenario templates to quantify cost and time impacts from tariffs, safety-rule compliance and evolving standards for vehicle-to-grid (V2G) and over-the‑air control.
- Commercial tools — TCO models for OEMs and fleets, pricing sensitivity dashboards, and GTM modules for tier suppliers entering adjacent domains (inverters, e-axles, integrated motor+control systems).
- M&A and partnership playbooks — screening criteria, valuation sensitivities for strategic acquisitions, and integration checklists that reduce execution risk post-deal.
Note: In keeping with the “trailer” principle of this preview, detailed segment tables and the granular regional & application breakdowns are not included here. The full dataset, with interactive filters and downloadable tables, is available in the full report.
Electric Vehicle Motor Controller Market
Market dynamics shaping 2026 choices
- Voltage and architecture leapfrogging: The commercial introduction of 1,000‑volt platforms in 2025 and the broader adoption of 800‑volt architectures are accelerating controller complexity. Controllers must support higher switching speeds, enhanced insulation requirements and new DC-link and battery management interfaces — all while meeting thermal budgets.
- Semiconductor and SiC adoption: Silicon carbide (SiC) is now a mainstream design lever for traction inverters and controllers. SiC reduces conduction loss and allows higher switching frequencies, but it also concentrates supply‑chain leverage. 2026 sourcing strategies should combine long‑term offtakes with alternative architectures to reduce exposure.
- Material & component volatility: Electrical-steel price swings and lamination supply constraints are cascading into motor assembly timelines. Leaders will privilege designs that either reduce lamination dependency or that can be manufactured flexibly across multiple stamping suppliers.
- Regulatory & trade shocks: New safety-control mandates effective from early 2025 and a layered trade regime in key markets (notably duties affecting imports) are increasing the value of localized supply and pre-certified modules for rapid market access.
- System-level integration: The competitive edge is shifting toward suppliers who combine motor, inverter and control software into compact, high-power-density e-axles, plus those embedding sensing and thermal-management features at the controller level.
Competitive landscape — who matters and why (high-level analysis)
The market exhibits moderate concentration: the top three suppliers control a meaningful share but there remains extensive room for regional specialists and innovative entrants (CR3 ≈ 28.5%, CR5 ≈ 36.2%). That structure favors both partnership-driven scale plays and targeted inorganic moves.
- Bosch / Robert Bosch GmbH — Strong execution on SiC-based inverter platforms and integrated electrical drive control units (EDCU). Bosch’s portfolio emphasis on torque-optimized control and power-module advances positions it as a preferred supplier for performance and durability-sensitive OEM programs.
- Continental AG — Differentiates with sensor integration (temperature and rotor-position sensing) that closes the loop between motor thermal state and inverter control. This creates opportunities to reduce rare-earth dependency through smarter control strategies and to optimize power density.
- Denso — Focused on high power-density inverters for e-axle applications and already tracking adoption in OEM programs, signaling strong OEM alignment and scale-readiness.
- Nidec — Vertical integration across motor, inverter and reducer (E‑Axle) with growing mass‑production capability, including high-volume axial-flux motor production through strategic assets like YASA.
- Hitachi Astemo, ZF, AISIN, Mitsubishi Electric, Siemens — Each brings differentiated strengths in e-drive integration, power-electronics manufacturing and system-level validation. These firms are natural partners for OEMs seeking tested modules and integration support.
- onsemi — A critical semiconductor and intelligent power-module supplier whose portfolio influences inverter design choices and supplier-benchmark rankings.
Recent industry signals to watch: Continental’s motor-heat sensing tied to inverter control, Denso’s inverter adoption in production EVs, AISIN’s trade-show showcases, and Nidec/YASA production milestones are all early indicators of supplier trajectories to monitor in 2026.
Actionable strategic playbook for 2026
- Prioritize modular controller architectures that can be field-upgraded for 800–1,000V systems — this preserves program flexibility as battery architectures diverge.
- Start SiC supply negotiations in 2026 with staggered delivery milestones and conditional pricing caps to smooth cost curves and secure capacity.
- Build or buy thermal-management IP: higher power density won’t scale without advanced cooling and sensor fusion at the controller level.
- Design procurement tender templates that include regulatory compliance checkpoints (FMVSS and regional equivalents) and tariff-mitigation clauses.
- Implement a supplier-risk scorecard that integrates geopolitical, material and capacity risk metrics so procurement can trade off cost versus reliability at bid time.
- Run pilot V2G and vehicle-level integration tests with a small number of OEM partners to validate grid-interaction requirements and to capture early learning for controller firmware and cybersecurity.
- Screen acquisition targets using a capability-first lens: prioritize firms with unique power-electronics IP, validated OEM programs, or manufacturing scale in low-cost regions with favorable trade treatment.
- Lock in OEM co-development agreements for e‑axle systems where suppliers can amortize fixed costs across multiple programs.
Conclusion — the decision window in 2026
2026 is a pivot year: the market’s growth path requires investments that balance speed-to-market with supply-chain prudence. The PW Consulting report pairs quantitative market foresight (base year 2025; forecast 2026–2032) with operational playbooks, supplier benchmarking and scenario models that let leadership teams stress-test capital plans and product roadmaps against tariff regimes, material shocks and architecture shifts.
This preview highlights our approach and directional findings. For the complete, interactive dataset, supplier-score spreadsheets, and the full suite of procurement and M&A templates, consult the full Electric Vehicle Motor Controller Market report. The detailed segment tables and granular regional/application breakouts are available there for licensed subscribers and corporate clients who require transaction-ready intelligence.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Motor Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CO Alarm Market to hit USD 343.5M by 2032, driven by 7.12% CAGR
By pmarketresearch, 2026-07-09
Carbon Monoxide Alarms Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our Carbon Monoxide (CO) Alarms Market research—designed to equip C-suite leaders, product teams, channel managers, and investors with the strategic context they need for 2026. This piece synthesizes the market’s macro trajectory, regulatory inflection points, competitive dynamics, and practical use-cases for corporate decision-making. Consider it a concise “trailer”: rigorous in insight, directional in findings, and intentionally selective in proprietary detail to invite a deeper review of the full report.
Carbon Monoxide Alarms Market
Market at a glance: pace and scale
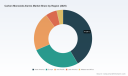
Our baseline analysis (base year 2025) shows a market that has recovered from short-term volatility and is set on a multi-year expansion path. From 2020 through 2025 the market rebalanced amid supply chain frictions and shifting consumption patterns; by the end of the base year the global market size stood at USD 213.5 Million. Under conservative-to-midcase assumptions and incorporating known regulatory drivers and technology adoption curves, our forecast to 2032 anticipates steady growth to USD 343.5 Million—reflecting a compound annual growth rate of roughly 7.12% across the 2026–2032 projection window.
Carbon Monoxide Alarms Market
Why does this matter for 2026? Two features distinguish the coming year: (1) demand is no longer limited to replacement cycles and new builds—compliance and retrofit programs are driving incremental volume—and (2) product differentiation (connectivity, sensor type, low-nuisance detection, and voice/UI improvements) is widening margins for winners. For firms planning 2026 budgets, these macro numbers create a quantitative anchor for capital allocation, product roadmap timing, and channel investments.
Carbon Monoxide Alarms Market
Why 2026 is a strategic hinge year
- Regulatory tightening: New requirements that took effect on January 1, 2026—mandating CO alarms on every storey and adjacent to sleeping areas under specific conditions—immediately convert latent need into near-term addressable demand for many homeowners and multi-dwelling units. Compliance-driven adoption creates predictable uplift for retrofit-focused channels (electricians, HVAC, and professional installers) and subscription-based monitoring services.
- Standards evolution: Updates to UL 2034 in 2025 introduced new display and voice-alert criteria and reinforced performance testing across low- and high-level CO exposures. Products that fail to quickly align will face reduced shelf access in major markets and increased liability exposure—while compliant, differentiated products enjoy preferential procurement by institutions and municipal programs.
- Technology convergence: The market is shifting from single-point, low-innovation hardware to systems that combine electrochemical sensing, smarter algorithms for nuisance reduction, and networked notification (Wi‑Fi/low-power wireless). This enables new commercial models—sensor-as-a-service, professional monitoring addons, and bundled safety platforms from smart-home incumbents.
Strategic implications by stakeholder
- Manufacturers: Prioritize UL-compliant upgrades, voice/display enhancements, and modular electronics that permit sensor or connectivity swaps without full product requalification. Invest selectively in electrochemical sensor supply resilience and long-life battery chemistry to reduce warranty exposure and differentiate on Total Cost of Ownership.
- Channel partners & installers: Retrofit programs and code-driven requirements translate into recurring revenue opportunities through inspection, replacement, and monitoring subscriptions. Upsell programs (combo devices, smart monitoring) and installer certification will be decisive competitive advantages.
- Distributors & retailers: Curate assortments that balance price-entry up to premium smart alarms; plan inventory around regulatory-driven replacement spikes, not just seasonality. Invest in salesperson training on compliance messaging—confidence in code knowledge materially lowers purchase friction.
- Insurers & large property managers: Use the forecast horizon to model loss-ratio impacts from increased CO detection penetration and to negotiate programmatic discounts or mandatory retrofit timelines tied to risk mitigation clauses.
- Smart-home and professional monitoring players: The expansion in regulatory units creates a distribution channel for monitoring services. Recent product launches introducing 24/7 monitoring compatibility validate plug-in opportunities to bundle CO alarm listeners into subscription stacks.
Competitive landscape: evolution, not revolution
The market exhibits moderate concentration—our concentration metrics indicate that the top three suppliers control a meaningful plurality of revenue, and the top five approach majority share. This structure favors established brands that combine national distribution, recognized safety certifications, and broad channel reach.
Profiles worth watching:
- First Alert continues to leverage strong brand equity and a product portfolio that spans battery, hardwire, combo, and sealed-10-year offerings with smart alert capabilities. Their advantage lies in consumer trust and deep retail placement.
- Kidde competes on breadth—hardwired, plug-in, long-life battery options and voice-enabled combos—while pushing towards indoor air quality differentiation. Their emphasis on digital displays and voice alerts aligns with UL updates and consumer expectations for clearer status communication.
- BRK Electronics focuses on precision detection and low-nuisance sensing, which will be increasingly important as regulations codify detection thresholds and as installers emphasize false-alarm reduction in multi-unit dwellings.
- Gentex Corporation plays to the commercial and institutional market with 120VAC solutions, electrochemical sensor technologies, and models that integrate programmable relays—equipment features that appeal to building management and fire protection integrators.
Emerging dynamics: non-traditional entrants and smart-home incumbents are accelerating product-service convergence. Notably, a 2025 new product that enables 24/7 professional monitoring for legacy detectors demonstrates the potential to monetize installed bases without wholesale device replacement. Similarly, corporate product launches that combine room-specific detection, Wi‑Fi connectivity, and localized voice cues underscore the market’s tilt toward smarter, serviceable platforms.
Where near-term value will concentrate
- Regulatory retrofits: Municipal and state-level code updates create concentrated demand pockets; companies that can rapidly mobilize compliance-focused SKU bundles and installer programs will capture disproportionate share.
- Service-enabled hardware: Lower hardware margins can be offset by recurring revenue—monitoring, maintenance subscriptions, sensor replacement plans, and certification services for landlords.
- Low-nuisance algorithms and UX: Reducing false positives in mixed-use and high-traffic locations materially lowers churn and installer callbacks, improving brand economics.
- Institutional integrations: Products with programmable relays, interoperable protocols, and clear UL performance marks will be selected for schools, multifamily, and commercial retrofits—segments where purchase cycles are longer but ASPs and-scale economics are favorable.
What the full PW Consulting report delivers (practical, actionable content)
Our full report is constructed to move leaders from insight to decision execution. It includes:
- Detailed market-sizing back to 2020 and a granular forecast through 2032 with scenario sensitivity to regulatory and supply-side shocks.
- Segmentation frameworks by product type, application, and region (note: proprietary split tables and revenue curves are reserved for the full report).
- Competitive profiles and feature-mapping across sensor technology, power architecture, connectivity, and compliance status for leading suppliers.
- Channel and route-to-market playbooks for retailers, distributors, professional installers, and integrators—complete with SKU rationalization recommendations and margin simulations.
- Regulatory and standards playbook: a checklist for compliance, a timeline for UL and code adoption, and recommended product requalification strategies to minimize time-to-shelf.
- Go-to-market and M&A heat maps identifying profitable niches, white-space opportunities for subscription-bundles, and candidate criteria for bolt-on acquisitions—supported by valuation multiples and integration risk checklists.
- Implementation templates: a 90‑180 day roadmap for product upgrades, an installer recruitment and certification program, and a monitoring-service commercial model with unit economics and churn sensitivities.
How to use this insight in 2026 planning
- Scenario-budget alignment: Use our CAGR-backed forecast as the baseline for capital planning. Stress-test product and channel investments against a regulated-adoption upside and a more conservative, consumer-led replacement scenario.
- Product prioritization: Defer low-margin updates that do not materially affect UL compliance; accelerate investments in features that reduce installer callbacks and enable professional monitoring.
- Channel incentives: Design retrofit programs for high-propensity installers with clear rebates, training, and co-marketing to capture code-driven waves.
- M&A & partnerships: Target bolt-on acquisitions that add connectivity, monitoring capability, or installer networks rather than purely incremental manufacturing capacity.
- Regulatory readiness: Ensure all SKUs meet the updated UL display and voice requirements and develop an evidence package for procurement teams and municipal programs.
Final perspective: timing, not just sizing
The CO alarms market is no longer a pure hardware commodity; 2026 will crystallize winners through a combination of timely regulatory execution, service-enabled monetization, and product differentiation that addresses real-world nuisance and installation pain points. The macro numbers—from a stable base in 2025 growing at mid-single digits into the next decade—offer both a growth runway and a deadline: firms who ready compliant, connected, and serviceable solutions in the next 12 months will capture the early share and establish pricing and channel norms.
PW Consulting’s full Carbon Monoxide Alarms Market report provides the granular revenue splits, supplier scorecards, and implementation tools necessary to translate these strategic conclusions into executable plans. For executives who must decide budgets, M&A targets, or product launches in 2026, the report is engineered to reduce uncertainty and accelerate time-to-value.
Next steps
- Contact PW Consulting to obtain the full report package for comprehensive segmentation, supplier KPIs, and tactical playbooks.
- Use the enclosed executive implementation templates to begin a 90-day readiness program aligned with UL and code timelines.
PW Consulting stands ready to support scenario modeling, M&A diligence, and go-to-market execution to convert the forecasted upside into realized growth.
For detailed analysis of this topic, please visit the official page: Carbon Monoxide Alarms Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Geothermal Power Market to Reach USD 678.5 Million by 2032 (5.6% CAGR)
By pmarketresearch, 2026-07-09
Geothermal Power Market: Strategic Imperatives for 2026 Decision‑Makers
Executive summary
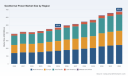
As companies set strategy for 2026 and beyond, geothermal power is shifting from a niche baseload resource toward a scalable, investible segment of the clean‑energy portfolio. Our new PW Consulting market study (base year 2025, historical 2020–2025, forecast 2026–2032; USD, revenue unit: Million) traces that transition with a combination of longitudinal market sizing, technology roadmaps and actionable commercial playbooks. The global market reached USD 470.8 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.6% through the forecast window — reflecting consistent demand for carbon‑free baseload, reductions in exploration and drilling cost curves, and growing commercial interest in enhanced geothermal systems (EGS).
Geothermal Power Market
Why this matters for 2026 decisions
-
Timing of capital: Geothermal projects are capital‑intensive and long‑lead. A 2026 investment decision needs to account for a market that is growing steadily but concentrated: the top three players control a substantial share and the top five an even larger share of capacity. That concentration affects pricing power, supply chains, and M&A dynamics.
Geothermal Power Market -
Technology inflection: The economics of EGS, standardised ORC (Organic Rankine Cycle) modules and modular plant designs are improving rapidly. These technology shifts change project execution risk profiles and create opportunities for industrial scale‑up or partnership strategies in 2026.
Geothermal Power Market -
Policy and demand signals: Recent public funding calls and a wave of long‑term PPAs supporting large consumers — notably data centers — are unlocking predictable revenue streams. Strategic players must align commercial negotiations, permitting timelines and supply‑chain commitments with these contracting windows.
Market trajectory and key dynamics
The market’s ascent to USD 470.8 Million in 2025 and the forecasted step‑up at a 5.6% CAGR through 2032 are not accidental. Three structural forces are driving growth: (1) the reliability premium for baseload, carbon‑free power increasingly sought by utilities and hyperscalers; (2) technology and drilling cost improvements that compress levelized cost trajectories; and (3) a favorable regulatory and funding environment that de‑risks early‑stage exploration and pilot deployments.
Notable contemporaneous developments underpin these forces: government funding initiatives for field‑scale testing, an active project finance market for PPAs, an uptick in equipment supply contracts for standardized ORC plants, and several high‑profile corporate moves — from IPOs for EGS developers to large PPAs tied to data center procurement. Collectively these validate geothermal as an investible option for 2026 capital allocation conversations.
What PW Consulting’s report delivers (practical, decision‑ready content)
-
Robust market sizing and scenario modelling (base year 2025; historical 2020–2025; forecast 2026–2032), with alternate macroeconomic and policy pathways to stress test investment cases.
-
Levelized cost and unit‑economics templates that reflect updated drilling cost curves and ORC standardisation impacts — usable as inputs to developer and investor financial models.
-
Procurement and supplier playbooks, including negotiation checklists and timing guidance for long‑lead items such as turboexpanders and generator sets.
-
Risk matrices and mitigation strategies specific to exploration, permitting, reservoir performance and construction scheduling, with recommended contract structures to allocate subsurface risk.
-
Competitor and partner intelligence: profiles of incumbent operators, emerging EGS players, and critical equipment vendors — plus scenario‑based guidance on how to craft JV and M&A approaches.
-
Project pipeline analytics and go‑to‑market playbooks for developers, utilities and corporate offtakers — designed to convert PPA interest into shovel‑ready projects.
Competitive landscape — strategic reads on core players
The market is defined by a mix of vertically integrated incumbents, national champions, equipment specialists and a new wave of EGS innovators. Understanding each archetype’s strategic advantage is essential for 2026 planning:
-
Vertically integrated developers/owners: Firms with end‑to‑end capabilities (from resource development to plant operation) can capture more margin but face higher capital exposure. Their ability to sign long‑term PPAs and finance pipelines gives them leverage in capacity markets and corporate procurement negotiations.
-
Large baseload operators: Companies that manage significant geothermal baseload portfolios are prioritising efficiency and incremental capacity additions to serve utility and data‑center off‑takers.
-
EGS and tech‑first entrants: These players are bringing seismic imaging, reservoir stimulation and standardised ORC modules to bear. Successful commercialisation could materially expand addressable resource base and change project timelines.
-
Equipment and engineering suppliers: Turboexpander and ORC OEMs are moving from bespoke builds to framework agreements and repeatable modules, accelerating build‑out cadence and reducing execution risk for developers.
Recent market events underscore these dynamics: contracts for large ORC deployments, multi‑project framework agreements between tech suppliers and EGS developers, a high‑profile EGS IPO that expanded access to public capital, and direct government funding opportunities targeted at exploration and field‑scale testing. These signals should be treated as inflection points in strategic planning for 2026.
Strategic implications and recommended actions for 2026
-
Developers: Prioritise modular plant designs and standardised procurement to reduce EPC lead times. Use staged development to preserve optionality until reservoir performance is proven. Target PPAs with creditworthy offtakers and explore public funding to de‑risk early exploration.
-
Equipment suppliers: Move to framework contracts and scale manufacturing capacity for ORC modules and turboexpanders. Offer integrated service contracts to capture aftermarket revenue and strengthen customer relationships.
-
Utilities and IPPs: Reassess portfolio allocation to include firm, dispatchable geothermal capacity as a hedge against renewable intermittency. Use long‑term PPAs and hybrid plant designs to balance supply security and cost.
-
Investors and financiers: Incorporate improved drilling cost curves and EGS learning rates into underwriting. Evaluate opportunities to finance early‑stage exploration alongside public grants and to back developers with proven asset portfolios.
-
Corporate offtakers (e.g., data centers): Lock in long‑dated PPAs while flexibility is available, and consider co‑funding exploration to align supply reliability with sustainability goals.
-
Governments and regulators: Fast‑track permitting pathways, align incentives with staged commercialisation, and coordinate funding to bridge the “valley of death” for EGS pilots.
How to use this study in a 2026 planning cycle
Make the report a tactical tool, not just reference material. Practical use cases include: (1) integrating the report’s levelized cost templates into your internal capital allocation model; (2) using supplier playbooks during RFPs to reduce procurement friction and cost overruns; (3) benchmarking potential JV partners against the competitive archetypes we outline; and (4) modelling policy scenarios to stress test expected returns under different incentive regimes. Our proprietary datasets and scenario models are built to plug into board‑level investment memoranda and lender due diligence.
What this preview does — and where to find the details
This introduction synthesises market direction, strategic choices and the types of executable guidance our full analysis provides. It intentionally highlights trends, competitive dynamics and the practical frameworks you need for 2026 without disclosing the full granular segmentation and project‑level datasets that are central to transactional decisions. For the complete breakdown — including regional and technology‑type segmentation, project‑level pipeline, vendor scorecards and downloadable financial templates — please visit our full report page.
Closing perspective
Geothermal’s profile has risen into boardroom conversations because the technology now intersects with reliable corporate demand, improved drilling economics, and active policy support. The market scale in 2025 and the steady CAGR through 2032 create a compelling runway for those who move early with disciplined project execution, smart supplier strategies and closely structured offtake contracts. PW Consulting’s full market study transforms these strategic opportunities into operational steps — enabling executives to make confident, evidence‑based decisions in 2026.
For detailed analysis of this topic, please visit the official page: Geothermal Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
ZLD Market to Reach USD 344.8 Million by 2032, Growing at 8.52% CAGR - PW Consulting
By pmarketresearch, 2026-07-09
Zero Liquid Discharge Systems: Strategic Intelligence for 2026 Decision‑Makers
Executive summary
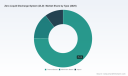
As PW Consulting’s lead industry analyst, I present an executive primer on the Zero Liquid Discharge (ZLD) systems market that frames the strategic choices corporate leaders must make in 2026. Our proprietary market model — calibrated across the historical period 2020–2025 (base year 2025) and extended through a 2026–2032 forecast window — shows the global ZLD market growing from approximately USD 163.15 Million in 2020 to USD 215.0 Million in 2025, and projecting to roughly USD 344.8 Million by 2032. That trajectory implies a compound annual growth rate of 8.52% across the forecast period. These headline figures capture demand expansion driven by regulatory tightening, industrial water-stress management, and technology-led cost compression; they are the guardrails for any capital planning, M&A, or R&D allocation in 2026.
Zero Liquid Discharge System (ZLD) Market
Why this research matters now
Three converging forces make ZLD strategy urgent in 2026. First, regulation has shifted from encouragement to enforcement in core end markets: recent rule‑making (notably in the steam‑electric and power sectors) tightens effluent limits and expands compliance obligations. Second, competitive pressure in water‑intensive industries (power generation, petrochemicals, mining, textiles and electronics manufacturing) is driving material reductions in freshwater withdrawal, creating both the mandate and the economic case for ZLD adoption. Third, technology and process advances — from higher‑pressure reverse osmosis elements to energy recovery and modular crystallization systems — are reshaping project economics so that previously marginal ZLD solutions are now viable for a wider set of sites.
Zero Liquid Discharge System (ZLD) Market
Of particular operational note: pretreatment spending ahead of membrane and heat‑exchange stages is forecast to grow faster than the system market itself (projected at about 9.35% annual growth). This is a leading indicator: operators are prioritizing fouling control and robustness to protect membrane and thermal assets, and capital allocation that neglects pretreatment risk will produce underperforming installations.
Zero Liquid Discharge System (ZLD) Market
What the full PW Consulting report delivers (practical elements)
- Actionable market sizing and scenario models — transparent methodology, downloadable templates, and sensitivity levers for energy prices, chemical costs, and capital intensity so teams can run site‑level economics under multiple regulatory outcomes.
- Decision frameworks for build vs. buy vs. partner — including procurement scorecards, contract structures (EPC, EPC‑O, O&M performance guarantees), and sample commercial clauses for brine disposal and product recovery.
- Technology selection playbooks — stepwise process maps for integrating pretreatment, membrane trains, mechanical vapor recompression (MVR), thermal evaporation/crystallization, and emerging approaches (freeze crystallization, eutectic processes) to fit plant constraints and recovery targets.
- Investment due diligence kits — CAPEX/OPEX benchmarking, lifecycle energy accounting, and a stress‑testing matrix for common failure modes (membrane fouling, scaling, heat exchanger degradation).
- Vendor shortlists and negotiation playbooks — competitive positioning, capability gaps, and recommended sourcing strategies for modular versus greenfield implementations.
- Regulatory and environmental risk heatmaps — mapping new and pending regulations to capital timelines and compliance windows so executives can prioritize projects with the steepest business risk reduction per dollar spent.
Competitive landscape — who to watch and why
The market structure remains dispersed: the leading three suppliers capture a minority share, producing a low‑to‑moderate concentration environment (CR3 and CR5 measures reflect a market where specialized equipment providers and engineering firms coexist with agile technology start‑ups). This fragmentation creates opportunity for buyers to leverage competitive tension but also raises the bar on vendor selection rigor.
- Veolia Water Technologies (Paris) — strong in EPC and large integrated projects. Their approach couples high‑performance evaporation/crystallization with membrane trains to deliver near‑zero discharge targets on complex industrial sites. Recent large project awards in petrochemical clusters demonstrate their ability to deploy end‑to‑end solutions at scale.
- Aquatech International (Pittsburgh) — known for custom integrated ZLD plants and retrofits achieving very high recoveries in power, petrochemical and mining applications. Their recent strategic acquisitions and project completions emphasize energy efficiency and brine valorization pathways.
- Alfa Laval (Lund) — competes with compact, energy‑efficient evaporator packages that appeal to footprint‑constrained industrial users. Their plate‑heat‑exchanger centric designs are compelling where reliability and serviceability are priorities.
- GEA Group (Düsseldorf) — positions around process integration and industrial effluent systems, with strengths in delivering distilled return streams to upstream processes and minimizing process interruption risk.
- Thermax (Pune) — an important regional player with modular MVR‑based ZLD units aimed at textiles, electronics and food processing. Their recent strategic alliances accelerate access to regional EPC channels across Southeast Asia.
- IDE Technologies (Lod) — focused on integrated RO/NF and brine management systems for high‑duty industrial and municipal projects; strength lies in process engineering and turnkey delivery models.
- Saltworks Technologies (Vancouver) — a technology innovator with skid‑based solutions and niche crystallization approaches (including freeze crystallization) targeted at mining and difficult brines.
- DuPont (Wilmington) — a materials play: advanced RO membrane elements that enable higher brine concentrations and push membrane‑based approaches into more challenging salinity regimes.
- ENCON Evaporators (Albuquerque) — thermal evaporator specialists offering staged ZLD architectures that can be cost‑effective on high‑TDS streams.
- Energy Recovery (San Leandro) — provides pressure‑exchange technologies that materially reduce energy intensity in membrane‑centric ZLD and MLD configurations.
Recent moves that change the playing field
- Large EPC wins in petrochemical hubs and high‑profile retrofits at power stations are accelerating institutional comfort with ZLD as a compliance tool and water‑security strategy.
- Strategic partnerships and joint ventures are emerging to combine modular manufacturing scale with partner EPC networks — an acceleration that shortens time‑to‑pilot and lowers deployment risk for industrial clients.
- Materials and membrane innovation is expanding the operating envelope of RO systems, allowing hybrid RO‑thermal architectures that optimize lifecycle cost for a broader set of brines.
Strategic implications and recommended actions for 2026
Executives deciding on ZLD exposure in 2026 should prioritize three correlated moves:
- Fast‑track pretreatment and piloting: Allocate budget to pretreatment robustness and run at least one site‑level pilot that stress‑tests fouling and scaling scenarios. Success at this stage de‑risks larger rollouts and preserves membrane life — the single biggest operational cost lever.
- Adopt a modular + EPC‑O procurement mindset: Favor modular, skid‑based units for brownfield retrofits to compress implementation timelines and reduce cost overruns; couple this with performance‑based EPC‑O contracts where vendors share energy and recovery performance risk.
- Pursue strategic partnerships for brine valorization: Treat brine as a potential feedstock (mineral recovery, salt products) rather than a waste stream to offset OPEX and improve project IRR. Where internal capability is limited, co‑invest with technology specialists or take minority stakes in emerging brine‑mining technology providers.
How PW Consulting’s report supports your 2026 decision cycle
The full PW Consulting ZLD market study translates the directional market growth (and the 8.52% CAGR embedded in our forecast) into executable investment priorities. Clients receive not only the headline market curves but a suite of operational tools: unit‑level CAPEX/OPEX models, procurement templates calibrated to vendor archetypes, scenario analyses that quantify regulatory timing risk, and a prioritized pipeline of high‑impact projects tailored to your asset base. We deliberately structure the output to be plug‑and‑play into 2026 budgeting cycles and board-level investment committees.
Conclusion — what to do next
For companies exposed to industrial wastewater risk, 2026 is a year to move from conceptual planning to demonstrable action. The market expansion reflected in our forecast is not uniform — it is concentrated where regulation, water stress, and cost improvements intersect. Use this window to pilot, to standardize procurement, and to capture value from brine streams before competitors do. For executives preparing capital requests and strategic roadmaps this year, the PW Consulting ZLD report supplies the empirical underpinnings, vendor intelligence, and implementation blueprints needed to convert compliance obligation into competitive advantage.
To access the complete analysis, granular modeling tools, and vendor scorecards that accompany this executive primer, please refer to the source report and contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Zero Liquid Discharge System (ZLD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PV Junction Box Market to Reach USD 2,236M by 2032 at 6.53% CAGR
By pmarketresearch, 2026-07-09
PV Junction Box Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Brief
As solar project owners, EPCs, module manufacturers, and component suppliers map their 2026 investment plans, PV junction boxes sit at a crossroads of electrical safety, supply-chain dynamics, and product engineering. PW Consulting’s latest PV Junction Box Market study — grounded in historical 2020–2025 analysis and extending through a 2026–2032 forecast horizon — synthesizes commercial, regulatory, and technical drivers that will shape procurement and product decisions next year. The market we assess was valued at approximately USD 1,435 million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of roughly 6.53%, reaching the mid‑2026 threshold near USD 1,578 million and continuing toward a multi‑billion dollar landscape by 2032. This brief outlines the study’s strategic value for 2026 decision-makers while preserving the proprietary, segment-level findings that are detailed in the full report.
PV Junction Box Market
Why 2026 Is a Pivotal Year for Junction Box Strategy
Three converging forces make 2026 a turning point for junction box decision-making. First, evolving safety standards and installation codes — notably the 2026 edition of the NEC clarifications on PV mating connector compatibility and the persistent primacy of UL 3730 for junction box certification — are raising the bar for product qualification and on-site inspection. Second, ongoing changes in trade policy and antidumping/countervailing duty (AD/CVD) activity are reshaping near-term sourcing economics: key tariffs ended early in 2026 for some import flows, while investigations and duties continue to affect others, creating both cost relief and continued uncertainty across supply chains. Third, product-level technical trends — higher system voltages, tighter ingress protection needs (IP68 and higher in many utility/industrial applications), and enhanced thermal stability for bypass diodes — are redefining specification checklists for renewables projects of all scales.
PV Junction Box Market
What Our Report Delivers (Operationally Actionable)
PW Consulting’s report is designed as a practical playbook for procurement, product, and corporate strategy teams. It goes beyond market sizing to deliver tools you can use this quarter and next year:
PV Junction Box Market
- Market framework and validated topline projections (2020–2025 historical, 2026–2032 forecast) to align executive planning horizons with expected demand trajectories.
- Supply‑chain mapping and cost-impact scenarios that model outcomes under alternate trade policy and freight-cost assumptions.
- Technical requirements matrix linking installation codes (NEC, IEC, UL) to product features and validation tests you should require from suppliers.
- Procurement playbooks: RFP templates, supplier qualification checklists, factory audit guides, and recommended KPIs for junction-box vendors.
- Competitive supplier shortlists and candidate profiles, triaged by capability (high-volume manufacturing, IP-rated solutions, high-voltage tolerance, certification competence).
- Scenario-based cash-flow impact models and a risk heatmap for supply disruptions, quality recalls, and regulatory shifts.
- M&A and partnership thesis including target archetypes, diligence checklists, and integration risks for companies pursuing verticalization or scale gains.
Competitive Landscape: Core Players and Strategic Positions
The PV junction box space remains moderately concentrated, with the combined top-three holding under half of the market and the top-five approaching half — a structure that favors nimble consolidation and vertical partnerships. Our analysis profiles manufacturers and channel players across North America, Europe, APAC, and specialized OEM suppliers. Highlights include:
- Amphenol Industrial Operations (US): A high‑volume, ISO‑9001 certified producer with established manufacturing footprints and branded solutions. Their Mesa, Arizona operations and productized offerings are oriented toward customers prioritizing scale, traceability, and compliance.
- Raychem RPG (India): Focused on higher‑specification solutions — notably IP68-rated split-type junction boxes with double-trench bypass diodes and 1500 V DC thermal performance — making them a competitive choice for utility-scale and high-voltage projects.
- China-based manufacturers (multiple firms): A cluster of suppliers offers end‑to‑end junction box ecosystems (waterproof enclosures, MC4-compatible connectors, in-line fusing and harness assemblies) at competitive price points and flexible volume options for module makers and EPCs.
- Regional specialists and component suppliers (Japan, Germany, Canada, UK): These firms differentiate on certification pedigree, reliability in harsh climates, and integration with module assembly lines or cable-harness systems.
- Channel and distributor players: Independent distributors play a critical role in bridging utility-scale procurement and aftermarket service needs; their inventory strategies will be a key lever for project timelines in 2026.
Recent market activity further underscores product and route‑to‑market evolution: leading vendors have launched higher‑IP connectors and split‑type junction boxes rated to 1500 V DC, trade show participation continues to be a driver of specification uptake in target geographies, and related material innovation (for example, encapsulants optimized for busbar and junction box insulation) is starting to influence product roadmaps.
Regulatory and Standards Signals That Should Drive Procurement Specs
Standards and regulatory updates will be decisive in supplier evaluation and product selection in 2026. Key items covered in the report and that should be embedded into RFPs include:
- NEC 2026 clarifications on connector mating compatibility — mandate cross‑brand compatibility testing and sealing verification for any connector pairs.
- UL 3730 as the central safety benchmark for junction box evaluation — require supplier test dossiers and factory-level certification evidence.
- IEC 60364‑7‑712 requirements in Europe and Asia — ensure environmental and electrical compliance for installations subject to these standards.
- Trade policy watch: monitor the exit of certain tariff measures and concurrent AD/CVD investigations that will alter landed cost assumptions; build dual-source options where margin impacts are material.
Five Tactical Moves for 2026 (How to Use This Report)
- Revise supplier qualification standards now. Incorporate IP‑rating verification, 1500 V DC thermal stability tests, and connector-compatibility evidence into any new vendor on‑boarding checklists.
- Stress‑test your supply chain under at least three trade-policy scenarios. The shifting balance between tariff relief and AD/CVD risk means procurement teams should have rapid-switch plans for alternate origins and validated secondary suppliers.
- Prioritize modularity and replaceability in specification documents. Design-for-service features (e.g., easily replaceable diode assemblies, standardized harness connectors) reduce O&M exposure and can be a competitive differentiator for module OEMs and EPCs.
- Embed standards-driven acceptance tests into field commissioning. Require third-party verification on key projects to mitigate warranty and safety liabilities tied to connector mismatch or ingress failures.
- Advance targeted partnerships or bolt-on acquisitions to secure critical components or certification capabilities, particularly in geographies where project pipelines are concentrated.
Where the Report Intentionally Holds Back — and Why That’s Strategic
In accordance with our “preview” approach, this introduction demonstrates the analytical depth and practical orientation of PW Consulting’s study while intentionally reserving granular, segment‑level tables and supplier scorecards for the full report. The report contains proprietary breakdowns (detailed regional and application splits, type-level volumes, supplier market shares and pricing curves) that are intentionally withheld here to preserve competitive value. If you are preparing 2026 budgets, procurement cycles or product roadmaps, gaining access to those segment tables will materially shorten your due-diligence cycle and sharpen supplier negotiation positions.
Final Synthesis: The Strategic Value Proposition for 2026
For executives making 2026 commitments, the strategic calculus for junction boxes centers on three imperatives: lock in compliant, serviceable product specifications that reflect updated codes; rebalance sourcing to reflect the new trade map and AD/CVD exposures; and invest selectively in products and partners that meet the durability and high-voltage performance thresholds emerging in utility-scale deployments. PW Consulting’s PV Junction Box Market study packages forecast clarity (with the market growing at ~6.53% CAGR from the 2025 base), supplier intelligence, and operational tools into a single decision‑support resource. It is designed to reduce procurement lead times, avert compliance surprises, and identify consolidative or partnership opportunities that deliver near-term risk reduction and long-term margin capture.
To convert these strategic insights into executable plans for 2026, access the full report for detailed segment tables, supplier benchmarking, downloadable RFP templates, and scenario models that tie directly to capital and O&M line items. PW Consulting’s analysts remain available for tailored briefings and bespoke scenario modeling to help your organization act with confidence in the year ahead.
For detailed analysis of this topic, please visit the official page: PV Junction Box Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Screwdriver Market to Hit USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-09
Electric Screwdriver Market 2026 — Strategic Imperatives for Executives
Executive summary
As companies plan investments and product strategies for 2026, the electric screwdriver market presents a measured yet compelling growth story anchored in electrification, ergonomics and digitalization. Our analysis shows the global market expanded from a measured base in 2020 to a base-year size of USD 215.0 Million in 2025, and is expected to grow at a compound annual growth rate (CAGR) of roughly 6.98% over the 2026–2032 forecast window — reaching an estimated USD 344.8 Million by 2032. The numbers point to a market that is large enough to attract scale players but sufficiently fragmented to reward focused strategies, differentiation through product systems and aftermarket services, and bold channel plays.
Electric Screwdriver Market
Why this report matters for 2026 decisions
Business leaders must decide where to allocate limited capital and management bandwidth in a market that combines hardware, batteries, software and services. The decision horizon for 2026 is short: procurement cycles, OEM sourcing windows and new-regulation compliance timelines compress the time to value. This market is characterized by steady volume growth, accelerating feature adoption (e.g., brushless motors, transducerized control, smart feedback), and rising non-recurring engineering (NRE) investments to meet ergonomic and safety regulations. Strategic choices in 2026 — whether to invest in an advanced cordless platform, deepen aftermarket service capabilities, or pursue M&A to consolidate capability gaps — will determine share and margin trajectories for the rest of the decade.
Electric Screwdriver Market
Market trajectory — the numbers you need to anchor decisions
-
Base year and historical context: Base year 2025 (USD 215.0 Million). The market has consistently expanded from 2020 through 2025, reflecting recovery and modernization in industrial and assembly sectors.
Electric Screwdriver Market -
Near- to mid-term outlook: Forecast period 2026–2032. At a projected CAGR of ~6.98%, the market scales to an estimated USD 344.8 Million by 2032 — indicating both volume expansion and incremental ASP (average selling price) uplift driven by tech upgrades and services.
-
Structure and concentration: The market remains relatively unconsolidated: the top-3 players account for under a quarter of the market, and the top-5 only edge above that. This low concentration (CR3 ~24.6%; CR5 ~26.2%) signals opportunity for specialist entrants and M&A for those seeking rapid footprint gains.
Key strategic implications for 2026
-
Prioritize battery and powertrain roadmaps. Cordless variants are the innovation vector: investments in higher-energy-density lithium-ion packs, Nuron-style platforms and battery-integrated services materially increase product stickiness. Expect raw-material price sensitivity (notably lithium and cobalt inputs) to remain a margin pressure point despite supply stabilization efforts.
-
Make ergonomics and vibration control a minimum spec. Regulation and end-user demand — especially in Europe and North America — are pushing vibration exposure limits and ergonomic mandates into procurement criteria. Tools that demonstrably reduce operator fatigue will command pricing power in industrial channels.
-
Move from product features to system solutions. Value migrates to systems that combine hardware, fastening intelligence (transducerized control, current-sense feedback), software telemetry and service contracts. OEMs and contract manufacturers increasingly buy into closed-loop maintenance and calibration services, not just tools.
-
Design the go-to-market for dual channels. Successful players will run differentiated propositions for industrial OEMs and for professional/commercial channels. A single SKU strategy underperforms; channel-tailored bundles and financing/leasing options accelerate adoption in capital-constrained facilities.
-
Factor regulation into product roadmaps. Compliance with EU Machinery Directive, EMC standards and updated harmonized standards is table stakes. Additionally, regional workplace safety rules (e.g., vibration exposure limits) directly impact product acceptance curves.
Competitive landscape — what incumbents are signaling
The competitive set combines legacy power-tool majors, electrification specialists and industrial fastening system providers. Each archetype signals a different playbook for 2026:
-
Bosch Power Tools — industrial ergonomics and broad-market reach: Recent product iterations emphasize dual-activation modes and clutch sophistication for delicate applications, underscoring Bosch’s strategy of packaging ergonomics with mass-market distribution.
-
Milwaukee Tool — modular battery ecosystems and high torque performance: Heavy focus on brushless motors and battery-platform lock-in suggests a path to recurring revenue via accessory ecosystems and platform-exclusive battery economics.
-
DEWALT — professional assembly productivity: DEWALT’s compact kits and multi-stage torque control target assembly applications where throughput and ease-of-use directly influence buyer decisions.
-
Makita — precision and configurability: Advanced clutch settings and auto-stop features appeal to applications where consistent torque control reduces rework and warranty exposure.
-
Ingersoll Rand — intelligent fastening: The IQi Series and transducerized offerings point to a differentiated segment: smart fastening for traceability and closed-loop quality control in manufacturing lines.
-
Hilti — premium systems and platform-driven revenues: Hilti’s high-torque, battery-platformed devices pair with strong field service and replacement-battery models, ideal for customers accepting higher TCO for uptime benefits.
-
Atlas Copco — industrial-grade control and integration: With roots in industrial tooling, their emphasis is on torque accuracy and integration into assembly-line PLCs and MES systems.
Taken together, incumbents are bifurcating into (1) high-performance industrial systems with integrated feedback and services, and (2) broad consumer/professional cordless portfolios optimized for ease-of-use and cost. New entrants should decide which lane to contest — and with what assets (software, battery platform, distribution).
Regulation, materials and channel dynamics — immediate execution risks
-
Regulatory compliance is non-negotiable. Compliance with EU Machinery and EMC directives and with harmonized IEC standards is a gating item for entry into key markets. Recent updates to vibration exposure limits increase the compliance burden and create a feature differentiation axis.
-
Batteries remain the principal commodity risk. Lithium and cobalt pricing dynamics continue to influence both cost and sourcing strategies — vertical integration and long-term offtake agreements are defensible levers for margin protection.
-
Service and calibration supply chain matters. Precision fastening tools require calibrated servicing; building a field-service network or partnering with certified distributors accelerates installations in regulated industrial settings.
Opportunities and white spaces to pursue in 2026
-
Smart fastening as a service: Offer transducerized tools plus analytics subscriptions for manufacturers that demand traceability and reduction in rework costs.
-
Battery-as-a-service and rental models: For cost-sensitive buyers, leasing battery packs or offering tool rental with maintenance increases penetration without upfront capex burdens.
-
Ergonomic differentiation for labor-constrained markets: Target ergonomically optimized products to reduce MSD (musculoskeletal disorders) risk and meet new vibration-exposure rules.
-
Channel engineering and embedded finance: Structure channel incentives and embedded financing to accelerate fleet swaps in SMEs and assembly shops.
What PW Consulting’s full report delivers — the practical toolkit
Our Electric Screwdriver Market research is designed for immediate operationalization in 2026 planning cycles. The full report provides:
-
Granular market sizing and validated 2020–2025 historicals with line-item methodology and primary-source reconciliation.
-
Scenario-based forecasts for 2026–2032 including sensitivity runs on battery-cost trajectories, regulatory shocks and channel-disruption scenarios.
-
Detailed competitive benchmarking covering product roadmaps, go-to-market models, pricing strategies, and service economics for leading incumbents.
-
Commercial playbooks for product launches, B2B sales, distribution redesign and aftermarket monetization with case studies and go/no-go decision trees.
-
Supply-chain risk maps and mitigations, including raw-material exposure heatmaps and sourcing contracting templates.
-
Regulatory and compliance tracker with implementation timelines and verification checklists for major markets.
-
Financial templates: build-your-own LCV/NPV models for platform investments, rental schemes and M&A scenarios.
-
Primary research appendices: interview transcripts, procurement tenders, and channel partner surveys that underpin our qualitative conclusions.
How to use this intelligence in 2026
-
Fast-track product-spec decisions: Use the report’s scenario outputs to prioritize battery platform investments and ergonomic features tied to regulatory timelines.
-
Align commercial metrics to service economics: Re-evaluate sales targets on a units-plus-service basis rather than hardware alone.
-
Prioritize M&A targets where they close capability gaps: Identify tuck-ins that accelerate entry into smart fastening or provide immediate channel access.
-
Negotiate upstream: Use our supply-chain heatmaps to secure long-term material offtake and lock favorable battery pricing structures.
Closing — why PW Consulting
The roadmap to leadership in the electric screwdriver market is a mix of disciplined product investment, channel orchestration and operational muscle on batteries and services. Our report marries quantitative market sizing with executable commercial playbooks and risk mitigations crafted for 2026 decision cycles. We intentionally withhold granular segmentation tables in this brief to preserve the high-value insights that reside in our full dataset and client deliverables; those datasets contain the tactical splits, regional and application-level detail, and the downloadable financial models that procurement, R&D and corporate development teams will use to convert strategy into outcomes.
Next steps
To access the full dataset, segmentation detail and the executable playbooks referenced here, visit the PW Consulting Electric Screwdriver Market overview page or contact our industry practice for a tailored briefing. For leaders who must decide where to invest in 2026, the right intelligence at this stage is not optional — it is a competitive advantage.
For detailed analysis of this topic, please visit the official page: Electric Screwdriver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Quantum Dot Market to Reach USD 10.03B by 2032 at 16.5% CAGR
By pmarketresearch, 2026-07-09
Quantum Dot Market 2026 Strategic Primer — PW Consulting
As companies prepare capital allocation, product roadmaps, and M&A strategies for 2026, understanding the quantum dot market’s trajectory and the levers that will determine winners is table-stakes. This strategic primer synthesizes PW Consulting’s latest research (base year 2025) to show where opportunity and risk are concentrating, why near-term regulatory and supply-chain shifts matter, and the practical choices executives must make in 2026. Consider this a guided preview: we surface the actionable perspective and analytical architecture underpinning the full study while intentionally withholding detailed segment-level breakouts to preserve the report’s proprietary value.
Quantum Dot Market
Market trajectory: a data-driven snapshot
The quantum dot market has moved beyond early-adopter economics into a phase of sustained commercial scale-up. Our topline sizing shows steady expansion from an estimated market value in 2020 through the base year (2025), and a strong forecast path across the 2026–2032 window. The model embeds a 16.5% CAGR for the forecast period and produces a clear implication: businesses that align manufacturing, regulation, and downstream channel strategies by 2026 position themselves to capture disproportionately larger shares of an expanding pie.
Quantum Dot Market
Two structural characteristics are especially notable. First, growth is compounding: historical adoption in displays and emerging uptake in energy, sensing, and healthcare create a multi-wave demand profile rather than a single-use spike. Second, the market is concentrated—our competitive concentration metrics indicate that the top three players command a meaningful majority of vendor revenues, and the top five further consolidate that position—creating a landscape where scale, IP depth, and supply-chain footprint materially influence bargaining power.
Quantum Dot Market
Why 2026 is an inflection year
-
Regulatory tipping points: Policy shifts in major markets are accelerating technology choices. Sustainability-oriented rules in Europe and new chemicals approvals in the U.S. are changing which material chemistries are commercially viable at scale. These regulations compress technical validation timelines and favor suppliers with compliance-ready, cadmium-free solutions.
-
Supply-chain rebalancing: Export-control actions and raw-material policy moves from major producers are creating pockets of supply risk for specific metals and precursors. Firms that proactively hedged sourcing or invested in alternative chemistries in 2024–25 will enter 2026 with a clear competitive advantage.
-
Industrialization milestones: Regulatory authorizations permitting higher-volume manufacture—combined with foundry investments—are transitioning quantum dots from component scarcity to component standardization for multiple system OEMs. This is a moment where manufacturing scale, yield improvement, and downstream integration become the dominant value levers.
What PW Consulting’s report delivers (practical modules)
-
Market sizing and scenario engine — deterministic and probabilistic forecasts across adoption curves with adjustable assumptions for regulatory regimes, material availability, and downstream adoption rates.
-
Supply-chain maps and risk heatmaps — node-level visibility into precursor sourcing, concentration risk, logistic chokepoints, and mitigation playbooks including dual-sourcing and nearshoring scenarios.
-
Technology readiness and cost-curves — comparative TRL (technology readiness level) assessments, cost-per-unit projections by production pathway, and sensitivity analysis on yield, passivation, and encapsulation improvements.
-
Commercial go-to-market playbooks — partner archetypes, channel economics, qualification timelines for displays, sensors and energy applications, and templates for OEM qualification contracts.
-
Regulatory and compliance toolkit — jurisdictional timelines, product approval checklists, RoHS/REACH alignment matrices, and an actionable compliance budget estimator for 2026 planning cycles.
-
Competitive and M&A intelligence — scorecards for incumbent foundries and specialist suppliers, strategic-fit screening for tuck-in targets, and valuation heuristics tuned to early-stage materials players.
-
Executive briefing materials — investor-ready slides, board memos, and negotiation play scripts for supply agreements and licensing deals.
Competitive landscape — signals that matter to strategy
The competitive field blends vertically integrated foundries, material specialists spun out of national labs, and a cohort of regional producers with differentiated chemistries. A few patterns crystallize from our company-level review and recent industry moves:
-
Foundry-scale incumbents: Players with end-to-end foundry capabilities are capturing the integration premium—offering scalable production, functionalizing services, and broad application portfolios. Regulatory approvals that enable higher permitted output further cement their cost-leadership trajectory.
-
Lab-origin innovators: Companies commercializing licensed technology from national laboratories combine credible IP with targeted product strategies (e.g., agriculture, security inks, or B2B drop-in solutions). Their speed to market relies on partnerships with system OEMs rather than in-house channel development.
-
Specialists and regional players: Firms focused on specific chemistries (infrared-capable dots, carbon-based variants, or core-shell dispersions) compete on technical differentiation and tight relationships with vertical customers like sensors, medical imaging, or specialty lighting.
Recent ecosystem activity reinforces these themes. Conferences and industry forums in 2025 brought the community together to accelerate commercialization and cross-pollinate use cases; product announcements validating Pb-free and SWIR sensing capabilities signal where R&D is converging toward commercial readiness; and regulatory milestones in the U.S. and Europe materially change scale economics and allowable production practices.
Strategic implications for decision-makers in 2026
-
Prioritize regulatory-aligned product roadmaps: Given tightening sustainability and dual-use controls, prioritize cadmium-free and compliance-ready variants in product pipelines. This reduces time-to-market risk in Europe and eases procurement for global OEMs.
-
De-risk supply chains with layered sourcing: Build multi-tiered supplier strategies (primary foundry + qualified specialist backup). For critical precursors, secure long-term offtakes or strategic equity stakes where price volatility and export controls pose asymmetric downside.
-
Invest in qualification and systems integration: Quantum dots move from component to system differentiator when integrated under stable qualification cycles. Allocate resources to co-development with key OEMs and to pilot lines that shorten the commercialization time from validation to production.
-
Adopt an acquisition-for-capability playbook: Use bolt-on acquisitions to fill gaps in chemistry, IP, or regional manufacturing footprint rather than as primary routes for scale. Smaller technology acquisitions can yield outsized returns if paired with manufacturing or channel capacity.
-
Embed scenario planning in capital decisions: Capital investments should be hedged across material scenarios—run the PW Consulting scenario engine to stress-test CapEx under different export-control and regulatory regimes before board approval.
-
Negotiate supplier agreements with volatility clauses: Given upstream concentration risk, craft contracts with mechanisms for pass-through costs, capacity reservation, and rapid qualification of alternative suppliers.
How to use PW Consulting’s models in your 2026 playbook
The full PW Consulting deliverable is built for immediate operationalization. It includes dynamic spreadsheets and dashboards where executives can:
-
Toggle regulatory outcomes and observe the impact on TAM and unit economics;
-
Run supplier-failure scenarios to prioritize investment in redundancy;
-
Calibrate R&D runway and qualification timelines against commercial milestones for prioritized applications;
-
Filter potential M&A targets by strategic fit, integration risk, and runway-to-revenue.
We also provide a structured workshop agenda to convert insights into a 90-day action plan: stakeholder alignment, sourcing decisions, pilot milestones, and a 12–24 month investment map tied to key regulatory events. The intent is to move leadership from analysis to decisive action with minimum friction and measurable KPIs.
Next steps — where the full intelligence lives
This primer intentionally highlights strategic direction and the practical frameworks you need for 2026 without reproducing the granular segmentation tables, regional allocations, and application-level dollar breakdowns that are the core monetizable outputs of our study. The PW Consulting report contains those granular datasets, supplier scorecards, and downloadable modelling assets that will let you run bespoke scenarios for your business units or investment thesis.
For boards, corporate strategy teams, or private-equity sponsors preparing 2026 plans, leveraging the full PW Consulting dataset is the most efficient way to reconcile technical choices, regulatory timelines, and capital allocation under a single, auditable model. Engage with our team to schedule a briefing and receive the complete toolkit, including the interactive forecast engine and the supplier diligence pack that underlies our recommendations.
For detailed analysis of this topic, please visit the official page: Quantum Dot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Night-Vision Goggles Market to reach USD 269.75M by 2032
By pmarketresearch, 2026-07-09
Night‑Vision Goggles Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this concise, decision‑centric preview of our forthcoming Night‑vision Goggles Market study. The aim here is to equip senior executives, procurement chiefs, defense program managers, and investors with the strategic context they need to frame 2026 planning — while reserving detailed segment tables and scenario modeling for the full report.
Night-vision Goggles Market
Why this study matters in 2026
The night‑vision sector is transitioning from incremental capability improvements to system‑level modernization. After a steady expansion through the 2020–2025 period, the market registered meaningful scale expansion up to the 2025 base year, and our forecast projects continued, compound growth through 2032 at a mid‑single‑digit-plus pace (CAGR 7.46% for the forecast window). By understanding the market trajectory, technology inflection points, procurement pipelines, and regulatory constraints, executives can prioritize R&D allocations, shape production footprints, and structure go‑to‑market partnerships to capture rising demand without overcommitting capital.
Night-vision Goggles Market
Market trajectory — headline numbers and interpretation
-
Historical momentum: The market grew consistently from 2020 to 2025, reflecting sustained defense spending, law enforcement modernization, and commercial adoption of advanced imaging solutions.
Night-vision Goggles Market -
Near‑term inflection: 2026 marks the beginning of our forecast window when procurement programs and next‑generation device rollouts accelerate; expect an observable uptick in program awards and production ramp activity.
-
Longer horizon: By the end of the 2026–2032 forecast horizon the market size is projected to be materially larger than the 2025 base, reinforcing the view that night‑vision systems are a durable growth category rather than a short‑cycle procurement spike.
Taken together, these macro figures signal a market where strategic timing, supply‑chain agility, and regulatory navigation will materially influence winners and losers.
What’s driving growth — three converging forces
-
Operational demand modernization: Armed forces and security agencies are replacing legacy monocular systems with integrated binocular and sensor‑fusion solutions that enhance situational awareness and reduce cognitive load for operators.
-
Technology maturation: Improvements in thermal sensitivity, image intensifier performance and digital augmentation (including augmented reality overlays and networked video) are expanding use cases beyond traditional night ops into persistent surveillance and allied commercial applications.
-
Procurement programs and industrial policy: Large, multi‑year procurement vehicles and national technology policies (including incentives to localize key components) are creating multi‑year production backlogs and predictable revenue streams for capable suppliers.
Regulatory and supply‑chain dynamics that will shape 2026 decisions
-
Export controls: Night‑vision devices remain dual‑use and subject to export controls—ITAR classifications, Wassenaar Arrangement updates, and national review processes impose licensing lead times and constrain market access. Practically, licensing can add months to delivery timelines and inflate compliance costs, which we quantify in the full report.
-
Performance thresholds and component restrictions: Recent multilateral updates limit the export of thermal cores below specific NETD thresholds, effectively creating technology tiers that favor domestically produced or licensed cores in certain allied procurements.
-
Cost of compliance: Our industry interviews and supplier financial models indicate that regulatory compliance (licensing, classification, and record keeping) is a non‑trivial cost line for manufacturers and assemblers and must be treated as part of product cost‑to‑serve rather than an overhead afterthought.
Competitive landscape — positioning and implications
The market exhibits moderate concentration; the top three and top five suppliers together command a substantial share of revenue, indicating that prime contractors and established defense OEMs retain strong program access and scale advantages. For 2026 strategic planning, understanding incumbent strengths and program ties matters as much as product performance.
-
Prime systems integrators: Established defense primes with prime contractor status on major programs continue to win multi‑year awards and maintain close programmatic relationships with government customers. Their advantage is not just product performance but integration capability, logistics support, and compliance infrastructure.
-
Specialist component and optics firms: Niche suppliers that produce high‑FOM image intensifier tubes, thermal cores, or specialized optics remain pivotal. Market entry for new players without protected IP or licensed production capacity is constrained by both technology and trade controls.
-
Commercial entrants and value variants: Manufacturers offering ruggedized commercial‑grade devices, clip‑on thermal modules, or cost‑efficient monoculars are expanding presence in non‑major defense channels (law enforcement, security services, outdoor markets). Their growth is complementary to prime systems, opening aftermarket and secondary channel revenue pools.
Representative competitive moves in early 2026 illustrate these dynamics: prime contractors have been selected for next‑generation binocular programs and multiple qualified suppliers are under IDIQ vehicles for development and production support. These selections are restructuring program award pipelines and will be decisive for capacity planning through the latter half of the decade.
Risks and mitigations for 2026 planning
-
Program schedule risk: Procurement timelines subject to licensing delays can cascade into production and delivery slippage. Mitigation: build regulatory cycle time into program plans and qualify alternate assembly sites or licensed suppliers as contingencies.
-
Supply bottlenecks for high‑FOM components: Restricted component export regimes can create localized scarcity. Mitigation: diversify supplier base, invest in second sources, or pursue licensed production agreements in allied countries.
-
Concentration and competitive pressure: The combined market share of leading suppliers creates a barrier to disruptive entry. Mitigation: focus on adjacent value streams (thermal clip‑ons, digital augmentation, software subscriptions, retrofit kits) and pursue fast follow or partnership strategies instead of head‑on competition for prime awards.
Practical, 2026‑ready recommendations
-
Procurement strategy: For defense buyers, align budgeting and contracting strategies with expected licensing timelines; use IDIQ and OTA vehicles to maintain program momentum while preserving competition.
-
Manufacturers and OEMs: Prioritize investments in thermal core mitigation strategies (localization, licensed manufacturing agreements) and accelerate certification paths for allied markets to reduce friction in exports.
-
Investors and M&A teams: Target companies that combine niche component IP (high‑performance tubes, thermal engines) with scalable assembly and compliance capabilities; assets that can be integrated into prime contractors’ supply chains typically command premium valuations.
-
Service providers and aftermarket entrants: Capitalize on retrofit and augmentation demand by offering modular clip‑ons, software upgrades, and lifecycle services—these are higher‑margin, lower‑capex opportunities relative to securing prime production contracts.
What the full PW Consulting report delivers (operational depth)
Our comprehensive study goes well beyond this preview. Key deliverables include:
-
Granular market forecasts across the 2026–2032 horizon by product architecture, application class, and major geographic markets; scenario analysis that quantifies upside and downside outcomes under alternative policy and procurement assumptions.
-
Supply‑chain heat maps identifying single‑point‑of‑failure components, lead times, and recommended supplier diversification strategies tailored to different risk appetites.
-
Regulatory playbook: a practical guide to ITAR/Wassenaar/DTSA classification, typical licensing timelines, and compliance cost modeling to incorporate into program bids and pricing.
-
Competitive intelligence dossiers for the leading suppliers and fast followers—product portfolios, program awards, manufacturing footprint, and partner ecosystems—paired with win/loss drivers and recommended counter‑strategies.
-
Commercialization toolkit: product‑market fit matrices for military, law‑enforcement, and commercial channels; go‑to‑market sequencing recommendations; and a financial model for business case testing of new product introductions or capacity investments.
Final word — how to use this insight for 2026
2026 is a pivotal planning year. Organizations that treat night‑vision merely as a hardware commodity risk being outmaneuvered by integrated systems providers and regulatory‑savvy competitors. Conversely, leaders who pair capability investments with supply‑chain resilience and export strategy will capture enduring value as the market scales through the forecast period.
This briefing surfaces the strategic contours and near‑term actions; the full PW Consulting report supplies the segmented forecasts, procurement pipelines, and vendor‑level analytics required to convert insight into decisive action. For procurement planners, product strategists, and investors preparing 2026 budgets, the full dataset and scenario tools will be indispensable.
Next steps
-
Contact PW Consulting for the full report and proprietary models if you need: detailed regional and application breakdowns, supplier scorecards, scenario testing, or bespoke advisory support to translate market projections into procurement or investment decisions.
-
Short on time? Request an executive workshop focused on program risk mitigation, supplier qualification strategies, and a 90‑day tactical plan aligned to your 2026 milestones.
For detailed analysis of this topic, please visit the official page: Night-vision Goggles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerant Leak Detectors Market to hit USD 1,658M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-09
Refrigerant Leak Detectors Market — Strategic Outlook for 2026 Decisions (PW Consulting)
As regulatory pressure, refrigerant chemistry transitions, and digital monitoring converge, the refrigerant leak detectors market is entering a phase of sustained, engineered growth. PW Consulting’s latest study—anchored on a 2025 base year and providing a forward view to 2032—models this market expanding at a compound annual growth rate (CAGR) of 6.8%. That trajectory implies a step-change in addressable revenue and investment opportunity between 2026 and the end of the forecast horizon. This article summarizes the strategic value of the research for executives preparing 2026 budgets, product roadmaps, compliance programs, and M&A pipelines, while preserving the detailed segment-level datasets and financial breakdowns for subscribers to the full report.
Refrigerant Leak Detectors Market
Why this study is essential for 2026 strategic planning
-
Regulatory compliance is now a procurement driver: new requirements effective from 2026 accelerate replacement, retrofit, and monitoring investments across regulated equipment classes.
Refrigerant Leak Detectors Market -
Technology differentiation matters: sensor chemistry, detection methodology (infrared, heated-diode, ultrasonic, solid-state), and connectivity options are reshaping product roadmaps and pricing power.
Refrigerant Leak Detectors Market -
Service-led monetization is maturing: remote monitoring, subscription models, and centralized alarm management convert hardware sales into recurring revenue.
-
Channel and aftermarket playbooks require refresh: contractors, OEMs, and facility managers are altering buying behavior in response to compliance deadlines and technician certification requirements.
Market trajectory and macro context
Our top-line model shows the market already beyond the billion-dollar threshold in the 2025 base year, with a steady expansion through 2032 driven by replacement cycles, retrofits for lower-GWP refrigerants, and mandated monitoring for high-charge installations. The CAGR of 6.8% encapsulates both organic growth in serviceable equipment populations and the premium captured by higher-value fixed-monitoring and remote-supervision solutions. Importantly for 2026 planning, the next 12–18 months represent a compressive period in which regulation, standards adoption, and product rollouts converge — creating windows for first-mover advantage.
Key dynamics shaping supplier and buyer decisions (2026–2027)
-
Regulatory acceleration: Expanded refrigerant management rules that took effect in early 2026 increase the number of appliances subject to formal leak management. Further, mandates requiring automatic leak detection for very large HFC-charged systems create near-term demand spikes for fixed and centralized monitoring platforms.
-
Standards harmonization: New and updated standards for electronic probe detectors and certification protocols (including SAE updates and state-level calibration requirements) are moving buyers toward certified, traceable devices — raising the bar for market entry and second-source qualification.
-
Refrigerant transitions: Growing adoption of mildly flammable A2L refrigerants, CO2 systems, and low-GWP blends drives demand for detector technologies validated across a broader chemistry set and for devices rated to specific safety standards.
-
Digital and remote monitoring: Product launches and trade-show previews in late 2025 and early 2026 highlight embedded connectivity, cloud platforms, and 24/7 remote alarm management as differentiators — particularly for commercial and industrial accounts.
-
Workforce competency: Expanded certification requirements for technicians introduce a practical barrier that favors suppliers offering simple-to-use, low-calibration, or maintenance-free instruments, as well as training partnerships with distributors.
Competitive landscape — implication for positioning and partnerships
The competitive map is a mix of legacy test-equipment OEMs, specialized sensor innovators, industrial monitoring firms, and a growing set of manufacturers from Asia focused on cost-competitive units. The market exhibits a moderate concentration: the top three providers control roughly half of the market by revenue, and the top five approach the upper half‑decile. This structure creates room both for scale players to protect share through certification and channel depth, and for focused specialists to win premium niches through technology leadership.
-
Technology and product leaders: Firms with proven multi-chemistry detectors (including infrared and heated-diode platforms), long-life sensors, and validated A2L solutions are best positioned to command premium margins in regulated commercial and industrial segments. Recent new-product introductions highlight an industry pivot toward higher sensitivity, better pump performance, and extended sensor life.
-
Connectivity and systems players: Suppliers integrating cloud connectivity and centralized supervision systems are converting one-time hardware sales into managed services. Remote-monitoring capabilities displayed at industry events in 2026 indicate substantial interest from end-users seeking continuous compliance and analytics.
-
Standards and certification differentiators: Companies that quickly certify to updated SAE procedures and to region-specific calibration standards gain a practical advantage in procurement processes where traceability is required.
-
Regional and cost-focused competitors: Competitive pressure from lower-cost manufacturers persists for handheld and portable models. These suppliers can gain volume share in less-regulated markets or in price-sensitive service channels.
Recent product and industry moves to watch
-
Late‑2025/early‑2026 product rollouts and trade-show reveals emphasize three trends: improved sensitivity and pump designs for handhelds, maintenance-free infrared options for A2L chemistries, and centralized remote monitoring systems suited to large commercial portfolios.
-
Certifications against updated SAE test procedures and other standards materially change buying criteria for contractors and facility operators—making certification timetables a critical part of go‑to‑market planning.
What the full PW Consulting report contains (operational detail)
-
Transparent market-sizing and forecasting methodology (base year 2025, historic review 2020–2025, forecast 2026–2032), with downloadable model files for scenario stress-testing.
-
Segment-level analyses across product types, application verticals, and regions, with adoption curves, addressable market estimates, and sensitivity testing (note: detailed segment tables are reserved for report subscribers).
-
Competitive profiles for the industry’s leading and fast-emerging players, including product portfolios, differentiating IP, channel strategies, and comparative capability matrices.
-
Regulatory impact mapping that aligns rules, standards, and compliance dates to procurement windows and retrofit cycles — enabling compliance-first prioritization in capital planning.
-
Technology evaluation framework that scores detector technologies against sensitivity, cross-refrigerant compatibility, lifecycle cost, certification readiness, and integration potential with building/plant supervisory systems.
-
Commercial playbooks: pricing elasticity models, service and SaaS packaging options, distributor engagement strategies, and pilot-to-scale roadmaps for SaaS-enabled monitoring offerings.
-
M&A and investment scorecards, identifying acquisition archetypes (sensor providers, cloud-platform vendors, regional channel consolidators) and valuation sensitivities informed by recurring revenue potential.
How to use this intelligence to shape 2026 decisions
-
Prioritize compliance-driven demand: Align R&D and inventory investments to the equipment classes and installation profiles that are first impacted by regulation. Time product certifications to precede procurement cycles.
-
Bundle hardware with managed services: Pilot remote-monitoring subscriptions with strategic customers to demonstrate recurring revenue economics and to shorten sales cycles for larger fixed-monitoring deployments.
-
Certify early, market loudly: Attaining updated SAE standards and regional calibration approvals should be treated as commercial milestones — factor certification timelines into launch calendars and channel incentives.
-
Optimize channel economics: Re-calibrate distributor margins and field‑technician incentives to accelerate adoption among service contractors, who are often the de facto buyers of handheld and portable solutions.
-
Screen M&A targets by tech defensibility and service attach potential: Prioritize assets that complement an existing monitoring stack or that accelerate access to certified sensors and cloud telemetry.
Final observations — urgency and opportunity
For executives mapping 2026 spend and strategic initiatives, the refrigerant leak detectors market presents a predictable, regulation‑anchored growth environment with clear levers for value creation. Hardware sales remain the foundation, but the real upside is in certified, multi-chemistry solutions and in converting monitoring into recurring services. The market’s moderate concentration enables both scale consolidation plays and specialist premium niches; success will depend on moving quickly on certification, connectivity, and channel alignment.
PW Consulting’s full report provides the underlying data, segment-level revenue tables, regional breakouts, and actionable model workbooks required to justify capital allocations, prioritize R&D, and select acquisition targets. The summary above outlines the strategic contours — the report itself is the operational map senior leaders need to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Refrigerant Leak Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Residential Portable Generators Market at USD 5.51B in 2025; 7% CAGR through 2032
By pmarketresearch, 2026-07-09
Residential Portable Generators Market: Strategic Preview for 2026 Decision-Making
Executive snapshot
As utilities, homeowners and regulators adapt to a more volatile climate and changing air-quality expectations, the residential portable generators market is entering a phase of steady growth and regulatory re‑sculpting. PW Consulting’s forthcoming market study, grounded on a 2025 base year and a 2026–2032 forecast horizon, quantifies that pathway: after expanding steadily from 2020, the total market continues a compound annual growth trajectory near 7.0% and is projected to move meaningfully higher through 2032. For executives planning product portfolios, channel investments or M&A in 2026, the core value of this research lies in translating that topline momentum into defensible, executable choices under heightened safety and emissions scrutiny.
Residential Portable Generators Market
Why this matters for 2026 strategies
- Timing of regulatory inflections: 2025–2026 is a crystallization point. New safety standards and state-level certification requirements that came into effect or were clarified in 2025 are materially reshaping which SKUs can be commercialized and where. Decisions made in 2026 about certifications, model rationalization, and inventory allocation will determine near‑term market access and long‑term brand positioning.
- Predictable topline, disruptive tail risks: The market’s baseline growth provides a reliable backdrop for investment planning. However, episodic shocks—severe weather events prompting surges in replacement demand, or accelerated policy actions on emissions and CO mitigation—create asymmetric upside and downside that must be scenario‑modeled into 2026 budgets.
- Investment prioritization under limited capital: With product and compliance investments competing for the same capital, 2026 will be the year to prioritize certified models, CO‑sensing technologies, and inverter efficiencies that unlock premium pricing and broader market access.
Industry dynamics shaping 2026 choices
Several interlocking trends are influencing demand, supply and strategic posture:
Residential Portable Generators Market
- Safety and emissions standards are shifting from guidance to gatekeepers. The ANSI/PGMA G300 revision that took force in 2025 tightened CO‑shutoff expectations and performance testing for residential models. At the same time, state enforcement of emissions certification—most notably in California—has been clarified and, in some cases, temporarily adjusted in response to supply constraints. These regulatory dynamics convert what were previously market‑access niceties into hard prerequisites in many sales channels.
- Product differentiation is consolidating around multi‑fuel flexibility and intelligent safety systems. Tri‑fuel and dual‑fuel capabilities, advanced CO‑sensing/shutoff, and inverter architectures that deliver cleaner power and quieter operation are now central to competitive differentiation. Firms that delay integrating these features risk margin pressure as consumers and channel partners increasingly prefer certified, safer models.
- Supply‑side frictions create tactical opportunities. Temporary policy adjustments aimed at mitigating shortages have demonstrated that manufacturers who maintain flexible production and certification pipelines capture transient demand spikes. However, these are stopgaps—persistent compliance and certification will be the differentiator for full market participation over the medium term.
Competitive landscape: what the leaders are doing
The market exhibits concentrated leadership: a handful of incumbents set technology, channel and safety benchmarks. Our full report offers in‑depth profiles and strategic scorecards; below are high‑level observations that should inform 2026 playbooks.
Residential Portable Generators Market
- Generac Power Systems, Inc. — Strategy centers on a broad portable and inverter portfolio that spans homeowner to contractor use. Their investment in CO‑sensing safety features and multi‑fuel models has positioned them to defend premium channels. For rivals, Generac’s scale in distribution and brand equity means that any premium technological leap must be coupled with compelling channel incentives to shift shelf space.
- DuroMax Power Equipment — DuroMax competes by combining fuel flexibility with aggressive channel pricing and a focus on residential backup compliance. Their certified dual‑fuel offerings make them a natural competitor in markets where regulatory clarity favors certified SKUs; incumbents should expect focused competition in value channels and DIY retail.
- Champion Power Equipment — Champion’s emphasis on safety technologies such as CO mitigation and its product breadth across dual/tri‑fuel space make it a resilient challenger in both emergency backup and recreational segments. Their playbook demonstrates how consistent safety messaging plus selective product innovation can win shelf position without scale parity.
- Westinghouse Electric Corporation — Westinghouse’s approach contrasts with pure portable specialists through brand leverage and competitive inverter offerings for residential and leisure applications. For strategic planners, Westinghouse’s moves underscore the importance of cross‑category branding and distribution partnerships when pursuing rapid share gains.
Recent regulatory and standardization developments you must factor into 2026 plans
- ANSI/PGMA G300 (revised, effective 2025) established tighter CO‑shutoff and performance testing—manufacturers should assume this is the baseline for residential acceptance and for demonstrating due diligence to regulators and retailers.
- California’s emergency policy in mid‑2025 temporarily allowed continued sale/import of EPA‑certified units to relieve supply constraints; however, state certification remains the durable requirement for long‑term access. Firms must treat temporary waivers as tactical relief, not strategic pathways.
- Industry association inputs to consumer safety agencies in 2025 demonstrate active regulatory engagement; companies that proactively engage standards bodies will have a voice in shaping implementable requirements and in managing compliance costs.
What the PW Consulting report provides (practical deliverables)
The full study is structured to convert market intelligence into immediate decision tools for 2026:
- Topline market sizing and a transparent forecasting model (2026–2032) with scenario toggles for regulatory tightening, accelerated electrification and extreme-weather demand shocks.
- Regulatory impact matrix that quantifies time‑to‑market and cost implications of ANSI/PGMA and state certification pathways, with prioritized certification roadmaps for North America and export markets.
- Product strategy playbooks—feature prioritization (CO safety, inverter tech, fuel flexibility), price‑to‑feature benchmarking, and SKU rationalization templates optimized for retail and e‑commerce channels.
- Competitive scorecards and acquisition target screens—financial proxies, technology fit, and integration risk measures to accelerate inorganic growth decisions.
- Channel and inventory playbooks that align certification timing, production cadence and trade promotions to minimize out‑of‑stock exposure during demand surges.
- Hands‑on M&A and partnership scenarios that show when to buy product‑technology vs. buy distribution, with modeled payback periods under the report’s baseline growth assumption.
- Operational risk heatmap and mitigation playbook covering emissions compliance, recalls, CO‑safety incidents and supply chain disruption.
Actionable recommendations for 2026 planning
- Prioritize certification spend by market value and access risk. Allocate certification budgets to secure access in high‑value jurisdictions first; use temporary policy relaxations only to smooth short‑term revenue, not to replace long‑term compliance.
- Defend and extend safety leadership. Embed CO‑shutoff and tamper‑resistant testing in next‑generation SKUs; safety leadership reduces channel resistance and supports pricing power.
- Product rationalization and SKU simplification. Reduce complexity by focusing on modular platforms that support both inverter and conventional variants; this shortens lead times to certify and reduces inventory burdens.
- Channel segmentation and dynamic inventory allocation. Implement differentiated assortments for certified vs. non‑certified channels and use predictive analytics to allocate certified stock to the most enforcement‑sensitive markets.
- Strategic collaboration with industry bodies. Engage with standards associations and consumer safety agencies to both influence the timing of new requirements and to earn recognition for voluntary compliance efforts.
- Scenario testing and liquidity planning. Build financial plans that stress test 2026 P&Ls under sudden spikes in demand and sudden tightening of state requirements to ensure resilient working capital and production flexibility.
Where this preview leaves you—and what to do next
The residential portable generators market offers a mix of predictable growth and regulatory inflection points. For leaders making 2026 choices, the strategic imperative is clear: move quickly to align product roadmaps and certifications with emerging standards, optimize SKU footprints to reduce compliance and inventory costs, and position brand and channel strategies to monetize safety and multi‑fuel differentiation.
PW Consulting’s complete report provides the empirical backbone—detailed forecast models, competitive benchmarking, certification cost estimates and playbooks—to convert these strategic priorities into executable 2026 plans. This preview illustrates our approach and the types of decisions you will need to take; for the full data tables, granular segmentation, and the operational templates that enable immediate action, consult the full study on our website.
For detailed analysis of this topic, please visit the official page: Residential Portable Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com