

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Geothermal Power Market to Reach USD 678.5 Million by 2032 (5.6% CAGR)

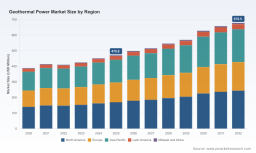
Geothermal Power Market: Strategic Imperatives for 2026 Decision‑Makers
Executive summary
As companies set strategy for 2026 and beyond, geothermal power is shifting from a niche baseload resource toward a scalable, investible segment of the clean‑energy portfolio. Our new PW Consulting market study (base year 2025, historical 2020–2025, forecast 2026–2032; USD, revenue unit: Million) traces that transition with a combination of longitudinal market sizing, technology roadmaps and actionable commercial playbooks. The global market reached USD 470.8 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.6% through the forecast window — reflecting consistent demand for carbon‑free baseload, reductions in exploration and drilling cost curves, and growing commercial interest in enhanced geothermal systems (EGS).
Geothermal Power Market
Why this matters for 2026 decisions
-
Timing of capital: Geothermal projects are capital‑intensive and long‑lead. A 2026 investment decision needs to account for a market that is growing steadily but concentrated: the top three players control a substantial share and the top five an even larger share of capacity. That concentration affects pricing power, supply chains, and M&A dynamics.
Geothermal Power Market -
Technology inflection: The economics of EGS, standardised ORC (Organic Rankine Cycle) modules and modular plant designs are improving rapidly. These technology shifts change project execution risk profiles and create opportunities for industrial scale‑up or partnership strategies in 2026.
Geothermal Power Market -
Policy and demand signals: Recent public funding calls and a wave of long‑term PPAs supporting large consumers — notably data centers — are unlocking predictable revenue streams. Strategic players must align commercial negotiations, permitting timelines and supply‑chain commitments with these contracting windows.
Market trajectory and key dynamics
The market’s ascent to USD 470.8 Million in 2025 and the forecasted step‑up at a 5.6% CAGR through 2032 are not accidental. Three structural forces are driving growth: (1) the reliability premium for baseload, carbon‑free power increasingly sought by utilities and hyperscalers; (2) technology and drilling cost improvements that compress levelized cost trajectories; and (3) a favorable regulatory and funding environment that de‑risks early‑stage exploration and pilot deployments.
Notable contemporaneous developments underpin these forces: government funding initiatives for field‑scale testing, an active project finance market for PPAs, an uptick in equipment supply contracts for standardized ORC plants, and several high‑profile corporate moves — from IPOs for EGS developers to large PPAs tied to data center procurement. Collectively these validate geothermal as an investible option for 2026 capital allocation conversations.
What PW Consulting’s report delivers (practical, decision‑ready content)
-
Robust market sizing and scenario modelling (base year 2025; historical 2020–2025; forecast 2026–2032), with alternate macroeconomic and policy pathways to stress test investment cases.
-
Levelized cost and unit‑economics templates that reflect updated drilling cost curves and ORC standardisation impacts — usable as inputs to developer and investor financial models.
-
Procurement and supplier playbooks, including negotiation checklists and timing guidance for long‑lead items such as turboexpanders and generator sets.
-
Risk matrices and mitigation strategies specific to exploration, permitting, reservoir performance and construction scheduling, with recommended contract structures to allocate subsurface risk.
-
Competitor and partner intelligence: profiles of incumbent operators, emerging EGS players, and critical equipment vendors — plus scenario‑based guidance on how to craft JV and M&A approaches.
-
Project pipeline analytics and go‑to‑market playbooks for developers, utilities and corporate offtakers — designed to convert PPA interest into shovel‑ready projects.
Competitive landscape — strategic reads on core players
The market is defined by a mix of vertically integrated incumbents, national champions, equipment specialists and a new wave of EGS innovators. Understanding each archetype’s strategic advantage is essential for 2026 planning:
-
Vertically integrated developers/owners: Firms with end‑to‑end capabilities (from resource development to plant operation) can capture more margin but face higher capital exposure. Their ability to sign long‑term PPAs and finance pipelines gives them leverage in capacity markets and corporate procurement negotiations.
-
Large baseload operators: Companies that manage significant geothermal baseload portfolios are prioritising efficiency and incremental capacity additions to serve utility and data‑center off‑takers.
-
EGS and tech‑first entrants: These players are bringing seismic imaging, reservoir stimulation and standardised ORC modules to bear. Successful commercialisation could materially expand addressable resource base and change project timelines.
-
Equipment and engineering suppliers: Turboexpander and ORC OEMs are moving from bespoke builds to framework agreements and repeatable modules, accelerating build‑out cadence and reducing execution risk for developers.
Recent market events underscore these dynamics: contracts for large ORC deployments, multi‑project framework agreements between tech suppliers and EGS developers, a high‑profile EGS IPO that expanded access to public capital, and direct government funding opportunities targeted at exploration and field‑scale testing. These signals should be treated as inflection points in strategic planning for 2026.
Strategic implications and recommended actions for 2026
-
Developers: Prioritise modular plant designs and standardised procurement to reduce EPC lead times. Use staged development to preserve optionality until reservoir performance is proven. Target PPAs with creditworthy offtakers and explore public funding to de‑risk early exploration.
-
Equipment suppliers: Move to framework contracts and scale manufacturing capacity for ORC modules and turboexpanders. Offer integrated service contracts to capture aftermarket revenue and strengthen customer relationships.
-
Utilities and IPPs: Reassess portfolio allocation to include firm, dispatchable geothermal capacity as a hedge against renewable intermittency. Use long‑term PPAs and hybrid plant designs to balance supply security and cost.
-
Investors and financiers: Incorporate improved drilling cost curves and EGS learning rates into underwriting. Evaluate opportunities to finance early‑stage exploration alongside public grants and to back developers with proven asset portfolios.
-
Corporate offtakers (e.g., data centers): Lock in long‑dated PPAs while flexibility is available, and consider co‑funding exploration to align supply reliability with sustainability goals.
-
Governments and regulators: Fast‑track permitting pathways, align incentives with staged commercialisation, and coordinate funding to bridge the “valley of death” for EGS pilots.
How to use this study in a 2026 planning cycle
Make the report a tactical tool, not just reference material. Practical use cases include: (1) integrating the report’s levelized cost templates into your internal capital allocation model; (2) using supplier playbooks during RFPs to reduce procurement friction and cost overruns; (3) benchmarking potential JV partners against the competitive archetypes we outline; and (4) modelling policy scenarios to stress test expected returns under different incentive regimes. Our proprietary datasets and scenario models are built to plug into board‑level investment memoranda and lender due diligence.
What this preview does — and where to find the details
This introduction synthesises market direction, strategic choices and the types of executable guidance our full analysis provides. It intentionally highlights trends, competitive dynamics and the practical frameworks you need for 2026 without disclosing the full granular segmentation and project‑level datasets that are central to transactional decisions. For the complete breakdown — including regional and technology‑type segmentation, project‑level pipeline, vendor scorecards and downloadable financial templates — please visit our full report page.
Closing perspective
Geothermal’s profile has risen into boardroom conversations because the technology now intersects with reliable corporate demand, improved drilling economics, and active policy support. The market scale in 2025 and the steady CAGR through 2032 create a compelling runway for those who move early with disciplined project execution, smart supplier strategies and closely structured offtake contracts. PW Consulting’s full market study transforms these strategic opportunities into operational steps — enabling executives to make confident, evidence‑based decisions in 2026.
For detailed analysis of this topic, please visit the official page: Geothermal Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com