

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Night-Vision Goggles Market to reach USD 269.75M by 2032

Night‑Vision Goggles Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this concise, decision‑centric preview of our forthcoming Night‑vision Goggles Market study. The aim here is to equip senior executives, procurement chiefs, defense program managers, and investors with the strategic context they need to frame 2026 planning — while reserving detailed segment tables and scenario modeling for the full report.
Night-vision Goggles Market
Why this study matters in 2026
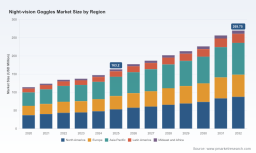
The night‑vision sector is transitioning from incremental capability improvements to system‑level modernization. After a steady expansion through the 2020–2025 period, the market registered meaningful scale expansion up to the 2025 base year, and our forecast projects continued, compound growth through 2032 at a mid‑single‑digit-plus pace (CAGR 7.46% for the forecast window). By understanding the market trajectory, technology inflection points, procurement pipelines, and regulatory constraints, executives can prioritize R&D allocations, shape production footprints, and structure go‑to‑market partnerships to capture rising demand without overcommitting capital.
Night-vision Goggles Market
Market trajectory — headline numbers and interpretation
-
Historical momentum: The market grew consistently from 2020 to 2025, reflecting sustained defense spending, law enforcement modernization, and commercial adoption of advanced imaging solutions.
Night-vision Goggles Market -
Near‑term inflection: 2026 marks the beginning of our forecast window when procurement programs and next‑generation device rollouts accelerate; expect an observable uptick in program awards and production ramp activity.
-
Longer horizon: By the end of the 2026–2032 forecast horizon the market size is projected to be materially larger than the 2025 base, reinforcing the view that night‑vision systems are a durable growth category rather than a short‑cycle procurement spike.
Taken together, these macro figures signal a market where strategic timing, supply‑chain agility, and regulatory navigation will materially influence winners and losers.
What’s driving growth — three converging forces
-
Operational demand modernization: Armed forces and security agencies are replacing legacy monocular systems with integrated binocular and sensor‑fusion solutions that enhance situational awareness and reduce cognitive load for operators.
-
Technology maturation: Improvements in thermal sensitivity, image intensifier performance and digital augmentation (including augmented reality overlays and networked video) are expanding use cases beyond traditional night ops into persistent surveillance and allied commercial applications.
-
Procurement programs and industrial policy: Large, multi‑year procurement vehicles and national technology policies (including incentives to localize key components) are creating multi‑year production backlogs and predictable revenue streams for capable suppliers.
Regulatory and supply‑chain dynamics that will shape 2026 decisions
-
Export controls: Night‑vision devices remain dual‑use and subject to export controls—ITAR classifications, Wassenaar Arrangement updates, and national review processes impose licensing lead times and constrain market access. Practically, licensing can add months to delivery timelines and inflate compliance costs, which we quantify in the full report.
-
Performance thresholds and component restrictions: Recent multilateral updates limit the export of thermal cores below specific NETD thresholds, effectively creating technology tiers that favor domestically produced or licensed cores in certain allied procurements.
-
Cost of compliance: Our industry interviews and supplier financial models indicate that regulatory compliance (licensing, classification, and record keeping) is a non‑trivial cost line for manufacturers and assemblers and must be treated as part of product cost‑to‑serve rather than an overhead afterthought.
Competitive landscape — positioning and implications
The market exhibits moderate concentration; the top three and top five suppliers together command a substantial share of revenue, indicating that prime contractors and established defense OEMs retain strong program access and scale advantages. For 2026 strategic planning, understanding incumbent strengths and program ties matters as much as product performance.
-
Prime systems integrators: Established defense primes with prime contractor status on major programs continue to win multi‑year awards and maintain close programmatic relationships with government customers. Their advantage is not just product performance but integration capability, logistics support, and compliance infrastructure.
-
Specialist component and optics firms: Niche suppliers that produce high‑FOM image intensifier tubes, thermal cores, or specialized optics remain pivotal. Market entry for new players without protected IP or licensed production capacity is constrained by both technology and trade controls.
-
Commercial entrants and value variants: Manufacturers offering ruggedized commercial‑grade devices, clip‑on thermal modules, or cost‑efficient monoculars are expanding presence in non‑major defense channels (law enforcement, security services, outdoor markets). Their growth is complementary to prime systems, opening aftermarket and secondary channel revenue pools.
Representative competitive moves in early 2026 illustrate these dynamics: prime contractors have been selected for next‑generation binocular programs and multiple qualified suppliers are under IDIQ vehicles for development and production support. These selections are restructuring program award pipelines and will be decisive for capacity planning through the latter half of the decade.
Risks and mitigations for 2026 planning
-
Program schedule risk: Procurement timelines subject to licensing delays can cascade into production and delivery slippage. Mitigation: build regulatory cycle time into program plans and qualify alternate assembly sites or licensed suppliers as contingencies.
-
Supply bottlenecks for high‑FOM components: Restricted component export regimes can create localized scarcity. Mitigation: diversify supplier base, invest in second sources, or pursue licensed production agreements in allied countries.
-
Concentration and competitive pressure: The combined market share of leading suppliers creates a barrier to disruptive entry. Mitigation: focus on adjacent value streams (thermal clip‑ons, digital augmentation, software subscriptions, retrofit kits) and pursue fast follow or partnership strategies instead of head‑on competition for prime awards.
Practical, 2026‑ready recommendations
-
Procurement strategy: For defense buyers, align budgeting and contracting strategies with expected licensing timelines; use IDIQ and OTA vehicles to maintain program momentum while preserving competition.
-
Manufacturers and OEMs: Prioritize investments in thermal core mitigation strategies (localization, licensed manufacturing agreements) and accelerate certification paths for allied markets to reduce friction in exports.
-
Investors and M&A teams: Target companies that combine niche component IP (high‑performance tubes, thermal engines) with scalable assembly and compliance capabilities; assets that can be integrated into prime contractors’ supply chains typically command premium valuations.
-
Service providers and aftermarket entrants: Capitalize on retrofit and augmentation demand by offering modular clip‑ons, software upgrades, and lifecycle services—these are higher‑margin, lower‑capex opportunities relative to securing prime production contracts.
What the full PW Consulting report delivers (operational depth)
Our comprehensive study goes well beyond this preview. Key deliverables include:
-
Granular market forecasts across the 2026–2032 horizon by product architecture, application class, and major geographic markets; scenario analysis that quantifies upside and downside outcomes under alternative policy and procurement assumptions.
-
Supply‑chain heat maps identifying single‑point‑of‑failure components, lead times, and recommended supplier diversification strategies tailored to different risk appetites.
-
Regulatory playbook: a practical guide to ITAR/Wassenaar/DTSA classification, typical licensing timelines, and compliance cost modeling to incorporate into program bids and pricing.
-
Competitive intelligence dossiers for the leading suppliers and fast followers—product portfolios, program awards, manufacturing footprint, and partner ecosystems—paired with win/loss drivers and recommended counter‑strategies.
-
Commercialization toolkit: product‑market fit matrices for military, law‑enforcement, and commercial channels; go‑to‑market sequencing recommendations; and a financial model for business case testing of new product introductions or capacity investments.
Final word — how to use this insight for 2026
2026 is a pivotal planning year. Organizations that treat night‑vision merely as a hardware commodity risk being outmaneuvered by integrated systems providers and regulatory‑savvy competitors. Conversely, leaders who pair capability investments with supply‑chain resilience and export strategy will capture enduring value as the market scales through the forecast period.
This briefing surfaces the strategic contours and near‑term actions; the full PW Consulting report supplies the segmented forecasts, procurement pipelines, and vendor‑level analytics required to convert insight into decisive action. For procurement planners, product strategists, and investors preparing 2026 budgets, the full dataset and scenario tools will be indispensable.
Next steps
-
Contact PW Consulting for the full report and proprietary models if you need: detailed regional and application breakdowns, supplier scorecards, scenario testing, or bespoke advisory support to translate market projections into procurement or investment decisions.
-
Short on time? Request an executive workshop focused on program risk mitigation, supplier qualification strategies, and a 90‑day tactical plan aligned to your 2026 milestones.
For detailed analysis of this topic, please visit the official page: Night-vision Goggles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com