

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Screwdriver Market to Hit USD 344.8M by 2032 at 6.98% CAGR

Electric Screwdriver Market 2026 — Strategic Imperatives for Executives
Executive summary
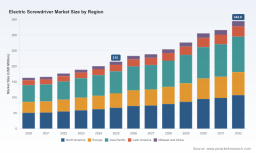
As companies plan investments and product strategies for 2026, the electric screwdriver market presents a measured yet compelling growth story anchored in electrification, ergonomics and digitalization. Our analysis shows the global market expanded from a measured base in 2020 to a base-year size of USD 215.0 Million in 2025, and is expected to grow at a compound annual growth rate (CAGR) of roughly 6.98% over the 2026–2032 forecast window — reaching an estimated USD 344.8 Million by 2032. The numbers point to a market that is large enough to attract scale players but sufficiently fragmented to reward focused strategies, differentiation through product systems and aftermarket services, and bold channel plays.
Electric Screwdriver Market
Why this report matters for 2026 decisions
Business leaders must decide where to allocate limited capital and management bandwidth in a market that combines hardware, batteries, software and services. The decision horizon for 2026 is short: procurement cycles, OEM sourcing windows and new-regulation compliance timelines compress the time to value. This market is characterized by steady volume growth, accelerating feature adoption (e.g., brushless motors, transducerized control, smart feedback), and rising non-recurring engineering (NRE) investments to meet ergonomic and safety regulations. Strategic choices in 2026 — whether to invest in an advanced cordless platform, deepen aftermarket service capabilities, or pursue M&A to consolidate capability gaps — will determine share and margin trajectories for the rest of the decade.
Electric Screwdriver Market
Market trajectory — the numbers you need to anchor decisions
-
Base year and historical context: Base year 2025 (USD 215.0 Million). The market has consistently expanded from 2020 through 2025, reflecting recovery and modernization in industrial and assembly sectors.
Electric Screwdriver Market -
Near- to mid-term outlook: Forecast period 2026–2032. At a projected CAGR of ~6.98%, the market scales to an estimated USD 344.8 Million by 2032 — indicating both volume expansion and incremental ASP (average selling price) uplift driven by tech upgrades and services.
-
Structure and concentration: The market remains relatively unconsolidated: the top-3 players account for under a quarter of the market, and the top-5 only edge above that. This low concentration (CR3 ~24.6%; CR5 ~26.2%) signals opportunity for specialist entrants and M&A for those seeking rapid footprint gains.
Key strategic implications for 2026
-
Prioritize battery and powertrain roadmaps. Cordless variants are the innovation vector: investments in higher-energy-density lithium-ion packs, Nuron-style platforms and battery-integrated services materially increase product stickiness. Expect raw-material price sensitivity (notably lithium and cobalt inputs) to remain a margin pressure point despite supply stabilization efforts.
-
Make ergonomics and vibration control a minimum spec. Regulation and end-user demand — especially in Europe and North America — are pushing vibration exposure limits and ergonomic mandates into procurement criteria. Tools that demonstrably reduce operator fatigue will command pricing power in industrial channels.
-
Move from product features to system solutions. Value migrates to systems that combine hardware, fastening intelligence (transducerized control, current-sense feedback), software telemetry and service contracts. OEMs and contract manufacturers increasingly buy into closed-loop maintenance and calibration services, not just tools.
-
Design the go-to-market for dual channels. Successful players will run differentiated propositions for industrial OEMs and for professional/commercial channels. A single SKU strategy underperforms; channel-tailored bundles and financing/leasing options accelerate adoption in capital-constrained facilities.
-
Factor regulation into product roadmaps. Compliance with EU Machinery Directive, EMC standards and updated harmonized standards is table stakes. Additionally, regional workplace safety rules (e.g., vibration exposure limits) directly impact product acceptance curves.
Competitive landscape — what incumbents are signaling
The competitive set combines legacy power-tool majors, electrification specialists and industrial fastening system providers. Each archetype signals a different playbook for 2026:
-
Bosch Power Tools — industrial ergonomics and broad-market reach: Recent product iterations emphasize dual-activation modes and clutch sophistication for delicate applications, underscoring Bosch’s strategy of packaging ergonomics with mass-market distribution.
-
Milwaukee Tool — modular battery ecosystems and high torque performance: Heavy focus on brushless motors and battery-platform lock-in suggests a path to recurring revenue via accessory ecosystems and platform-exclusive battery economics.
-
DEWALT — professional assembly productivity: DEWALT’s compact kits and multi-stage torque control target assembly applications where throughput and ease-of-use directly influence buyer decisions.
-
Makita — precision and configurability: Advanced clutch settings and auto-stop features appeal to applications where consistent torque control reduces rework and warranty exposure.
-
Ingersoll Rand — intelligent fastening: The IQi Series and transducerized offerings point to a differentiated segment: smart fastening for traceability and closed-loop quality control in manufacturing lines.
-
Hilti — premium systems and platform-driven revenues: Hilti’s high-torque, battery-platformed devices pair with strong field service and replacement-battery models, ideal for customers accepting higher TCO for uptime benefits.
-
Atlas Copco — industrial-grade control and integration: With roots in industrial tooling, their emphasis is on torque accuracy and integration into assembly-line PLCs and MES systems.
Taken together, incumbents are bifurcating into (1) high-performance industrial systems with integrated feedback and services, and (2) broad consumer/professional cordless portfolios optimized for ease-of-use and cost. New entrants should decide which lane to contest — and with what assets (software, battery platform, distribution).
Regulation, materials and channel dynamics — immediate execution risks
-
Regulatory compliance is non-negotiable. Compliance with EU Machinery and EMC directives and with harmonized IEC standards is a gating item for entry into key markets. Recent updates to vibration exposure limits increase the compliance burden and create a feature differentiation axis.
-
Batteries remain the principal commodity risk. Lithium and cobalt pricing dynamics continue to influence both cost and sourcing strategies — vertical integration and long-term offtake agreements are defensible levers for margin protection.
-
Service and calibration supply chain matters. Precision fastening tools require calibrated servicing; building a field-service network or partnering with certified distributors accelerates installations in regulated industrial settings.
Opportunities and white spaces to pursue in 2026
-
Smart fastening as a service: Offer transducerized tools plus analytics subscriptions for manufacturers that demand traceability and reduction in rework costs.
-
Battery-as-a-service and rental models: For cost-sensitive buyers, leasing battery packs or offering tool rental with maintenance increases penetration without upfront capex burdens.
-
Ergonomic differentiation for labor-constrained markets: Target ergonomically optimized products to reduce MSD (musculoskeletal disorders) risk and meet new vibration-exposure rules.
-
Channel engineering and embedded finance: Structure channel incentives and embedded financing to accelerate fleet swaps in SMEs and assembly shops.
What PW Consulting’s full report delivers — the practical toolkit
Our Electric Screwdriver Market research is designed for immediate operationalization in 2026 planning cycles. The full report provides:
-
Granular market sizing and validated 2020–2025 historicals with line-item methodology and primary-source reconciliation.
-
Scenario-based forecasts for 2026–2032 including sensitivity runs on battery-cost trajectories, regulatory shocks and channel-disruption scenarios.
-
Detailed competitive benchmarking covering product roadmaps, go-to-market models, pricing strategies, and service economics for leading incumbents.
-
Commercial playbooks for product launches, B2B sales, distribution redesign and aftermarket monetization with case studies and go/no-go decision trees.
-
Supply-chain risk maps and mitigations, including raw-material exposure heatmaps and sourcing contracting templates.
-
Regulatory and compliance tracker with implementation timelines and verification checklists for major markets.
-
Financial templates: build-your-own LCV/NPV models for platform investments, rental schemes and M&A scenarios.
-
Primary research appendices: interview transcripts, procurement tenders, and channel partner surveys that underpin our qualitative conclusions.
How to use this intelligence in 2026
-
Fast-track product-spec decisions: Use the report’s scenario outputs to prioritize battery platform investments and ergonomic features tied to regulatory timelines.
-
Align commercial metrics to service economics: Re-evaluate sales targets on a units-plus-service basis rather than hardware alone.
-
Prioritize M&A targets where they close capability gaps: Identify tuck-ins that accelerate entry into smart fastening or provide immediate channel access.
-
Negotiate upstream: Use our supply-chain heatmaps to secure long-term material offtake and lock favorable battery pricing structures.
Closing — why PW Consulting
The roadmap to leadership in the electric screwdriver market is a mix of disciplined product investment, channel orchestration and operational muscle on batteries and services. Our report marries quantitative market sizing with executable commercial playbooks and risk mitigations crafted for 2026 decision cycles. We intentionally withhold granular segmentation tables in this brief to preserve the high-value insights that reside in our full dataset and client deliverables; those datasets contain the tactical splits, regional and application-level detail, and the downloadable financial models that procurement, R&D and corporate development teams will use to convert strategy into outcomes.
Next steps
To access the full dataset, segmentation detail and the executable playbooks referenced here, visit the PW Consulting Electric Screwdriver Market overview page or contact our industry practice for a tailored briefing. For leaders who must decide where to invest in 2026, the right intelligence at this stage is not optional — it is a competitive advantage.
For detailed analysis of this topic, please visit the official page: Electric Screwdriver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com