

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CO Alarm Market to hit USD 343.5M by 2032, driven by 7.12% CAGR

Carbon Monoxide Alarms Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our Carbon Monoxide (CO) Alarms Market research—designed to equip C-suite leaders, product teams, channel managers, and investors with the strategic context they need for 2026. This piece synthesizes the market’s macro trajectory, regulatory inflection points, competitive dynamics, and practical use-cases for corporate decision-making. Consider it a concise “trailer”: rigorous in insight, directional in findings, and intentionally selective in proprietary detail to invite a deeper review of the full report.
Carbon Monoxide Alarms Market
Market at a glance: pace and scale
Our baseline analysis (base year 2025) shows a market that has recovered from short-term volatility and is set on a multi-year expansion path. From 2020 through 2025 the market rebalanced amid supply chain frictions and shifting consumption patterns; by the end of the base year the global market size stood at USD 213.5 Million. Under conservative-to-midcase assumptions and incorporating known regulatory drivers and technology adoption curves, our forecast to 2032 anticipates steady growth to USD 343.5 Million—reflecting a compound annual growth rate of roughly 7.12% across the 2026–2032 projection window.
Carbon Monoxide Alarms Market
Why does this matter for 2026? Two features distinguish the coming year: (1) demand is no longer limited to replacement cycles and new builds—compliance and retrofit programs are driving incremental volume—and (2) product differentiation (connectivity, sensor type, low-nuisance detection, and voice/UI improvements) is widening margins for winners. For firms planning 2026 budgets, these macro numbers create a quantitative anchor for capital allocation, product roadmap timing, and channel investments.
Carbon Monoxide Alarms Market
Why 2026 is a strategic hinge year
- Regulatory tightening: New requirements that took effect on January 1, 2026—mandating CO alarms on every storey and adjacent to sleeping areas under specific conditions—immediately convert latent need into near-term addressable demand for many homeowners and multi-dwelling units. Compliance-driven adoption creates predictable uplift for retrofit-focused channels (electricians, HVAC, and professional installers) and subscription-based monitoring services.
- Standards evolution: Updates to UL 2034 in 2025 introduced new display and voice-alert criteria and reinforced performance testing across low- and high-level CO exposures. Products that fail to quickly align will face reduced shelf access in major markets and increased liability exposure—while compliant, differentiated products enjoy preferential procurement by institutions and municipal programs.
- Technology convergence: The market is shifting from single-point, low-innovation hardware to systems that combine electrochemical sensing, smarter algorithms for nuisance reduction, and networked notification (Wi‑Fi/low-power wireless). This enables new commercial models—sensor-as-a-service, professional monitoring addons, and bundled safety platforms from smart-home incumbents.
Strategic implications by stakeholder
- Manufacturers: Prioritize UL-compliant upgrades, voice/display enhancements, and modular electronics that permit sensor or connectivity swaps without full product requalification. Invest selectively in electrochemical sensor supply resilience and long-life battery chemistry to reduce warranty exposure and differentiate on Total Cost of Ownership.
- Channel partners & installers: Retrofit programs and code-driven requirements translate into recurring revenue opportunities through inspection, replacement, and monitoring subscriptions. Upsell programs (combo devices, smart monitoring) and installer certification will be decisive competitive advantages.
- Distributors & retailers: Curate assortments that balance price-entry up to premium smart alarms; plan inventory around regulatory-driven replacement spikes, not just seasonality. Invest in salesperson training on compliance messaging—confidence in code knowledge materially lowers purchase friction.
- Insurers & large property managers: Use the forecast horizon to model loss-ratio impacts from increased CO detection penetration and to negotiate programmatic discounts or mandatory retrofit timelines tied to risk mitigation clauses.
- Smart-home and professional monitoring players: The expansion in regulatory units creates a distribution channel for monitoring services. Recent product launches introducing 24/7 monitoring compatibility validate plug-in opportunities to bundle CO alarm listeners into subscription stacks.
Competitive landscape: evolution, not revolution
The market exhibits moderate concentration—our concentration metrics indicate that the top three suppliers control a meaningful plurality of revenue, and the top five approach majority share. This structure favors established brands that combine national distribution, recognized safety certifications, and broad channel reach.
Profiles worth watching:
- First Alert continues to leverage strong brand equity and a product portfolio that spans battery, hardwire, combo, and sealed-10-year offerings with smart alert capabilities. Their advantage lies in consumer trust and deep retail placement.
- Kidde competes on breadth—hardwired, plug-in, long-life battery options and voice-enabled combos—while pushing towards indoor air quality differentiation. Their emphasis on digital displays and voice alerts aligns with UL updates and consumer expectations for clearer status communication.
- BRK Electronics focuses on precision detection and low-nuisance sensing, which will be increasingly important as regulations codify detection thresholds and as installers emphasize false-alarm reduction in multi-unit dwellings.
- Gentex Corporation plays to the commercial and institutional market with 120VAC solutions, electrochemical sensor technologies, and models that integrate programmable relays—equipment features that appeal to building management and fire protection integrators.
Emerging dynamics: non-traditional entrants and smart-home incumbents are accelerating product-service convergence. Notably, a 2025 new product that enables 24/7 professional monitoring for legacy detectors demonstrates the potential to monetize installed bases without wholesale device replacement. Similarly, corporate product launches that combine room-specific detection, Wi‑Fi connectivity, and localized voice cues underscore the market’s tilt toward smarter, serviceable platforms.
Where near-term value will concentrate
- Regulatory retrofits: Municipal and state-level code updates create concentrated demand pockets; companies that can rapidly mobilize compliance-focused SKU bundles and installer programs will capture disproportionate share.
- Service-enabled hardware: Lower hardware margins can be offset by recurring revenue—monitoring, maintenance subscriptions, sensor replacement plans, and certification services for landlords.
- Low-nuisance algorithms and UX: Reducing false positives in mixed-use and high-traffic locations materially lowers churn and installer callbacks, improving brand economics.
- Institutional integrations: Products with programmable relays, interoperable protocols, and clear UL performance marks will be selected for schools, multifamily, and commercial retrofits—segments where purchase cycles are longer but ASPs and-scale economics are favorable.
What the full PW Consulting report delivers (practical, actionable content)
Our full report is constructed to move leaders from insight to decision execution. It includes:
- Detailed market-sizing back to 2020 and a granular forecast through 2032 with scenario sensitivity to regulatory and supply-side shocks.
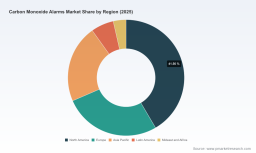
- Segmentation frameworks by product type, application, and region (note: proprietary split tables and revenue curves are reserved for the full report).
- Competitive profiles and feature-mapping across sensor technology, power architecture, connectivity, and compliance status for leading suppliers.
- Channel and route-to-market playbooks for retailers, distributors, professional installers, and integrators—complete with SKU rationalization recommendations and margin simulations.
- Regulatory and standards playbook: a checklist for compliance, a timeline for UL and code adoption, and recommended product requalification strategies to minimize time-to-shelf.
- Go-to-market and M&A heat maps identifying profitable niches, white-space opportunities for subscription-bundles, and candidate criteria for bolt-on acquisitions—supported by valuation multiples and integration risk checklists.
- Implementation templates: a 90‑180 day roadmap for product upgrades, an installer recruitment and certification program, and a monitoring-service commercial model with unit economics and churn sensitivities.
How to use this insight in 2026 planning
- Scenario-budget alignment: Use our CAGR-backed forecast as the baseline for capital planning. Stress-test product and channel investments against a regulated-adoption upside and a more conservative, consumer-led replacement scenario.
- Product prioritization: Defer low-margin updates that do not materially affect UL compliance; accelerate investments in features that reduce installer callbacks and enable professional monitoring.
- Channel incentives: Design retrofit programs for high-propensity installers with clear rebates, training, and co-marketing to capture code-driven waves.
- M&A & partnerships: Target bolt-on acquisitions that add connectivity, monitoring capability, or installer networks rather than purely incremental manufacturing capacity.
- Regulatory readiness: Ensure all SKUs meet the updated UL display and voice requirements and develop an evidence package for procurement teams and municipal programs.
Final perspective: timing, not just sizing
The CO alarms market is no longer a pure hardware commodity; 2026 will crystallize winners through a combination of timely regulatory execution, service-enabled monetization, and product differentiation that addresses real-world nuisance and installation pain points. The macro numbers—from a stable base in 2025 growing at mid-single digits into the next decade—offer both a growth runway and a deadline: firms who ready compliant, connected, and serviceable solutions in the next 12 months will capture the early share and establish pricing and channel norms.
PW Consulting’s full Carbon Monoxide Alarms Market report provides the granular revenue splits, supplier scorecards, and implementation tools necessary to translate these strategic conclusions into executable plans. For executives who must decide budgets, M&A targets, or product launches in 2026, the report is engineered to reduce uncertainty and accelerate time-to-value.
Next steps
- Contact PW Consulting to obtain the full report package for comprehensive segmentation, supplier KPIs, and tactical playbooks.
- Use the enclosed executive implementation templates to begin a 90-day readiness program aligned with UL and code timelines.
PW Consulting stands ready to support scenario modeling, M&A diligence, and go-to-market execution to convert the forecasted upside into realized growth.
For detailed analysis of this topic, please visit the official page: Carbon Monoxide Alarms Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com