

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Grain Combine Harvester Market Poised for 4.85% CAGR Through 2032

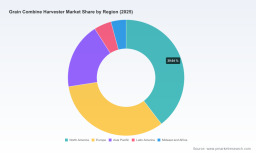
Grain Combine Harvester Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this executive preview of our Grain Combine Harvester Market study to outline the decisions that will define competitive positions in 2026. The market narrative below combines our proprietary modeling, public signals, and on‑the‑ground commercial intelligence to show where value will be created — while reserving the detailed segment tables and proprietary forecasts for the full report.
Grain Combine Harvester Market
Market snapshot: what the numbers tell us
After a steady recovery and reinvestment cycle across advanced agriculture markets, the global grain combine harvester market reached an estimated USD 165 million in our base year (2025). Our model projects a mid‑single‑digit compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window, culminating in a market near USD 235 million by 2032. Historical dynamics between 2020 and 2025 show a clear structural rebound driven by capacity upgrades, technology adoption, and replacement demand in mature markets, coupled with accelerated mechanization in select growth geographies.
Grain Combine Harvester Market
These topline dynamics matter because they change the calculus for capital allocation, product roadmaps, and aftermarket strategies: growth is steady but selective, meaning firms that target profitable segments and operationalize service economics will outperform those competing on volume alone.
Grain Combine Harvester Market
What the report delivers — practical, transaction‑ready insights
- Validated market sizing and scenario‑based forecasts (base year 2025; forecast period 2026–2032) with transparent methodology and sensitivity testing.
- Segment playbooks (by type, application and geography) designed for priority setting — note: granular split tables are included in the full report.
- Competitor value‑chain maps, including product portfolios, pricing ladders, and go‑to‑market channels.
- Strategic frameworks for R&D prioritization, aftermarket expansion, and dealer network optimisation.
- Supply‑chain stress tests and sourcing redesign options to de‑risk critical components and spare parts availability.
- M&A screening templates and synergy calculators to assess bolt‑on targets or vertical plays.
- Commercial playbooks for pricing, leasing, and operator training to accelerate adoption of higher‑value configurations.
Key market dynamics shaping 2026 choices
- Technology is the differentiator. Automation (harvest settings automation, predictive ground‑speed control), advanced headers, and telematics are moving from premium differentiators to near‑table stakes for enterprise customers seeking throughput and reduced operator variability. Recent OEM updates — for example, John Deere’s 2026 enhancements to X9 and S7 series and New Holland’s 2026 model updates — underscore this push.
- Aftermarket economics are mission critical. With replacement cycles stretching and capital expenditure constrained for many operators, parts, service contracts, and upgrades are the principal lever to preserve margin. Firms that systematize spare parts logistics and remote diagnostics will capture recurring revenue and raise switching costs.
- Regulatory and sustainability pressures are intensifying. Emissions compliance for diesel powertrains is not optional. OEMs are already integrating third‑generation SCR systems and optimizing engine architectures (as seen with manufacturer programs), which affects cost structures, supplier selection, and R&D timetables.
- Market concentration creates strategic opportunity and risk. The market exhibits meaningful concentration at the top end: a small set of global incumbents command a disproportionate share of value. That creates scale advantages in R&D and distribution but also opens niches for specialized or lower‑cost entrants in segments where service and price sensitivity dominate.
- Geography and crop mix matter — but selectively. Growth pockets are uneven. The implication for manufacturers and investors is to avoid blanket geographic expansion; instead, apply a targeted market‑entry play that aligns product configuration, dealer capability, and financing models to local operator economics.
- Macro forecasts vary by source. While some industry sources projected modest growth into 2026, our model — which incorporates machine economics, adoption lags, and parts monetization — points to stronger medium‑term expansion, reinforcing the case for action rather than wait‑and‑see.
Competitive landscape: how to think about rivals in 2026
Leading OEMs maintain differentiated positions based on technology stacks, distribution breadth, and brand trust. Global incumbents emphasize automation, capacity, and integrated precision solutions; legacy European and North American players typically combine premium R&D with deep dealer networks, while select Asian manufacturers compete on cost‑performance and export agility.
- Technology leaders continue to push automation and operator aids to compress harvest windows and improve throughput — features that enterprise customers prize during tight harvests.
- Volume players secure share through localized manufacturing, aggressive component sourcing, and competitive price points for standardized configurations.
- Service specialists differentiate on uptime guarantees, rapid parts fulfilment, and tailored financing/leasing models that lower adoption friction for mid‑tier operators.
Our competitive dossiers include tactical intelligence on each major OEM’s product roadmap, channel economics, and recent developments. As examples, John Deere’s 2026 product updates add tighter automation controls and operator aids to defend premium positions, while New Holland’s 2026 model refreshes emphasize header performance and adjustability that appeal to high‑output operators. At the same time, export‑focused manufacturers from other regions prioritize cost, parts availability, and regulatory compliance to expand footholds.
Strategic playbook: recommended actions for 2026
- Reprioritize R&D dollars: Shift investment toward modular automation features and remote diagnostics that are monetizable through subscription or retrofit programs.
- Double down on aftermarket capabilities: Build regional spare‑parts hubs, digitize inventory management, and create service SLA tiers that capture willingness to pay for uptime.
- Rethink channel economics: Move from transactional distribution to partnership models with dealers that include shared KPIs, outcome‑based pricing, and co‑funded training for operators.
- Embed emissions roadmaps into product strategy: Prioritize engine and after‑treatment investments now to avoid late‑cycle compliance cost shocks and to position products as future‑proof.
- Use M&A tactically: Target acquisitions or alliances that close capability gaps in telematics, headers, or local service infrastructure rather than pursuing only scale buys.
- Apply scenario‑based capital planning: Stress test CapEx and inventory policies under multiple harvest pricing and supply‑chain disruption scenarios before committing to factory expansions.
- Launch pilot commercialization models: Experiment with short‑term leasing, operator training bundles, and yield‑linked contracts to accelerate adoption among risk‑averse customers.
How PW Consulting’s study accelerates execution
Our full study goes beyond narrative to provide transaction‑ready tools: a calibrated financial model you can plug into your internal planning, dealer profitability matrices, a prioritized R&D roadmap with estimated ROI windows, and a deal‑sourcing list for inorganic options. We validate market assumptions against primary interviews, trade flows, and OEM announcements so that your 2026 roadmaps are grounded in market reality rather than optimistic guesses.
Importantly, while this preview shares high‑level conclusions and the strategic lens you need for 2026, detailed segment tables, regional breakdowns, and the full set of proprietary unit‑price curves are intentionally excluded here. Those elements are included in the published report and the interactive models we deliver to clients.
Immediate next steps for senior leaders
- Commission a rapid 60‑day audit of your aftermarket operations and parts inventory to identify quick win margin improvements.
- Run an R&D reallocation workshop using our scenario templates to quantify payback timelines for automation and emissions projects.
- Engage in disciplined channel segmentation: identify top dealers for strategic investment and a second tier for performance improvement programs.
- Secure a shortlist of M&A targets that fill capability gaps (telematics, headers, regional service hubs) and run preliminary valuation stress tests using our synergy model.
- Schedule a briefing with PW Consulting to receive the interactive forecast model and a bespoke 90‑day action plan tailored to your portfolio.
In short: 2026 will be a year for choices that compound. Firms that convert the macro growth tailwinds into differentiated, service‑driven revenue streams — while hardening their product and regulatory roadmaps — will capture disproportionate value. Those that continue to compete on price alone will find margins compressed as service and technology become the primary battlegrounds.
For the complete data tables, regional and application splits, and the interactive forecast model, schedule a briefing with PW Consulting or visit our Grain Combine Harvester Market report page to unlock the full intelligence package and bespoke strategy options for 2026.
For detailed analysis of this topic, please visit the official page: Grain Combine Harvester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com