

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laser Drilling for Aerospace to Reach USD 344.8 Million by 2032

Laser Drilling Machine for Aerospace Market: Strategic Insights for 2026 Decision-Makers
As aerospace programs push for higher thermal efficiency, lighter architectures, and tighter tolerances, laser drilling has evolved from a specialized capability into a strategic enabler across turbine manufacturing, hot-section component repair, and complex composite processing. This briefing previews PW Consulting’s upcoming market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—designed to inform board-level capital allocation, manufacturing modernization roadmaps, and supplier selection in 2026.
Laser Drilling Machine for Aerospace Market
Executive snapshot
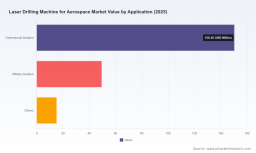
The global market for laser drilling machines applied to aerospace is on a sustained growth path. Our topline measures show the market expanding from about USD 163 million in 2020 to roughly USD 215 million in 2025, and continuing to grow at a compound annual growth rate (CAGR) of 6.98% through the forecast window to reach an estimated USD 345 million by 2032. Importantly, market composition remains fragmented (CR3 ~24.6%, CR5 ~26.2%), a dynamic that shapes competitive positioning and partner strategies.
Laser Drilling Machine for Aerospace Market
Why this research matters for 2026 decisions
-
Timing of investment: Procurement and CAPEX cycles for specialty laser equipment require lead times of 6–24 months when considering NADCAP/OEM qualification, fixture design, and automation integration. The 2026 planning year is therefore the decisive window for firms that want equipment operational for the mid-decade rise in aero engine MRO and new engine ramp-ups.
Laser Drilling Machine for Aerospace Market -
Risk calibration: Aerospace customers now demand certified process chains (NADCAP, OEM approvals). Our analysis quantifies the incremental time and cost to achieve those approvals and models break-even timelines for systems deployed in high-throughput effusion cooling hole production versus low-volume repair use cases.
-
Technology match: Different laser architectures (fiber, YAG, CO2) and multi-axis kinematics deliver distinct trade-offs in throughput, hole quality, and material scope. Choosing the wrong class of machine can constrain future product lines or force costly retrofits—this report maps those trade-offs against real-world aero alloy and composite use cases.
Market trajectory and strategic implications
The market’s near-term growth is driven by three converging forces: accelerating demand for high-efficiency turbine engines and their tighter cooling requirements; the expanding scope of additive and hybrid manufacturing where laser drilling is a finishing step; and an increase in aero MRO volumes as global aircraft utilization normalizes. Given the near-7% CAGR, executives can expect a meaningful enlargement of the addressable market over the next six years, but with continued heterogeneity by use case—production drilling for OEMs, repair/overhaul, and service bureau models.
For CFOs and strategy teams, the implication is clear: allocate capital where unit economics are validated for certification-heavy aerospace pathways (payback periods differ materially between high-volume effusion hole production and low-volume repair lines). For procurement and operations, prioritize systems that minimize qualification cycles and can be integrated into multi-stage automation cells.
Technology & process dynamics
-
Precision and speed: State-of-the-art multi-axis platforms deliver micro-hole precision down to 0.05 mm and positioning accuracy on the order of single-digit micrometers—examples include 5-axis systems reporting 9 µm positioning and process rates reaching hundreds of bores per second in optimized setups. These performance envelopes unlock high-density cooling patterns and enable consistent blade/airfoil production at scale.
-
Certification and standards: Success in aerospace requires more than a capable laser source. NADCAP accreditation for non-conventional machining (e.g., Laser Beam Machining) and OEM approvals (GE, Rolls-Royce, Pratt & Whitney, Honeywell) are de facto entry barriers. Our report quantifies certification pathways, average lead times, and typical rework/loss rates encountered during initial qualification.
-
Material & process breadth: Fiber lasers dominate new system deployments due to beam quality, reliability, and maintenance profiles, but YAG and other architectures retain niche roles (e.g., certain repair or ceramic applications). Multi-axis kinematics (5–7 axes) and moving-beam concepts reduce fixturing complexity and enable trepanning and helical drilling approaches needed for specific aero geometries.
Competitive landscape — who matters and why
Market fragmentation presents both challenge and opportunity. Our competitive module profiles the installed- and emerging-base players that matter to OEMs, MROs, and service providers.
-
DMG MORI — Positioned with a 5-axis LASERTEC PowerDrill family that emphasizes precision drilling for turbine blades and vanes. Their product differentiation stems from integrated process control (PowerShape and LASERSOFT stack), which eases qualification and supports advanced cooling-hole patterns in high-value aero components.
-
Prima Power — Known for multi-axis LASERDYNE-class systems delivering micro-hole accuracy and low heat-affected zones. Prima’s strength lies in CNC monitoring and a focus on minimizing collateral metallurgical effects—an important consideration for OEMs designing thin-wall cooling passages.
-
EBTEC Corporation — A U.S.-based provider combining Nd:YAG and fiber options across a range of power classes. Their aerospace-aligned credentials (AS9100, NADCAP) and OEM approvals make them a go-to for both production and certified repair workflows, particularly within North America.
-
Corry Laser Technology — Specializes in moving-beam, multi-axis systems and holds multiple OEM certifications. Their architecture is optimized for complex 3D geometries and trepanning techniques common in hot-section components.
-
Lenox Laser and Accumet Engineering — Represent service-focused players and niche-system integrators that excel in calibrated micro-hole work, small-leak and flow-control components, and secondary processing services—critical for shops that prefer outsourcing over heavy capital investment.
Recent industry activity—trade-show rollouts, new smart drilling modules, and concentrated industry forums—underscores a cycle of continuous incremental innovation rather than a disruptive technology replacement. In short: expect performance and integration improvements, not wholesale architectural shifts, over the 2026 planning horizon.
Strategic options for different stakeholders
-
OEMs scaling production: Invest in multi-axis fiber laser assets with integrated process control and plan for staggered qualification to avoid production bottlenecks. Consider co-investment or long-term supply agreements with equipment vendors that offer shared validation support.
-
MRO and repair networks: Evaluate a mixed strategy—retain a limited in-house certified capability for high-value, time-sensitive repairs, and contract out overflow to specialized service providers. Prioritize systems that minimize setup time for diverse component portfolios.
-
Component suppliers & bureaus: Differentiate via certifications and throughput economics. NA/EMEA supply chain dynamics favor service providers with quick certification turnarounds and repeatable quality metrics documented for OEM audits.
-
Investors & private equity: Low market concentration and the capital intensity of certification create consolidation opportunities. Targets with proven NADCAP workflows, sticky OEM relationships, and scalable automation have the most attractive exit pathways.
What’s inside the full report (practical deliverables)
-
Proprietary market-sizing model with bottom-up demand drivers, scenario-based forecasts to 2032, and sensitivity analysis around engine program cycles and MRO utilization.
-
Decision-grade capex and TCO calculators tailored to common deployment models (high-volume OEM line, repair cell, and contract-service bureau).
-
Regulatory and certification playbook that maps NADCAP requirements, OEM audit expectations, and a stepwise timeline to achieve end-client approvals.
-
Supplier heatmaps and vendor profiles with comparative matrices on precision, throughput, service capability, and integration maturity for automation and Industry 4.0 data exchange.
-
Use-case templates: validated process plans for effusion cooling hole production, hybrid additively manufactured surfaces finishing, and repair workflows that reduce cycle time while preserving metallurgical integrity.
-
Negotiation levers for procurement: recommended contract terms, performance-based acceptance criteria, and warranty/maintenance structures geared to aerospace customers.
How to use this research in 2026 planning cycles
Leaders should use the study as a decision-support tool across three planning pillars: where to commit capital, how to structure supplier partnerships, and what capabilities to certify in-house. The market’s projected expansion and continued fragmentation mean that timing, certification readiness, and supplier selection will drive both operational performance and program risk. The report provides the analytics to weight those choices objectively.
Final note — preview, not a substitute for the full study
This briefing showcases the strategic contours and operational levers relevant to laser drilling adoption in aerospace but intentionally omits detailed regional and application-level breakouts, unit economics for specific machine classes, and proprietary segmentation that underpin our forecasting model. Those datasets and the interactive tools described above are available only in the full PW Consulting report, which is essential for transaction-level decisions and program-specific investment cases in 2026.
For detailed analysis of this topic, please visit the official page: Laser Drilling Machine for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com