

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
Air Sampling Pumps Market: Why 4.53% CAGR and Asia Pacific Demand Redefine Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Air Sampling Pumps Market
Market Trajectory and Structural Pressures
The global air sampling pumps market has established a consistent growth trajectory, with revenue reaching approximately USD 59.34 million in 2025 and projected to climb to USD 80.4 million by 2032. This expansion reflects a compound annual growth rate of 4.53 percent across the 2026 to 2032 forecast period, signaling steady demand evolution rather than speculative boom cycles. Historical performance from 2020 through 2025 shows incremental gains, with year-over-year increases ranging from modest to moderate, reinforcing a market driven by regulatory compliance, occupational health priorities, and environmental monitoring requirements rather than volatile consumer behavior.
Within this landscape, regional concentration patterns reveal distinct maturity levels. Asia Pacific currently commands the largest revenue share, followed by North America and Europe, while Latin America and the Mideast and Africa represent smaller but developing footprints. The geographic distribution aligns closely with industrial activity density, regulatory enforcement intensity, and the spread of occupational hygiene programs. Product segmentation remains balanced between personal air sampling pumps and area air sampling pumps, each serving distinct monitoring requirements. Application-wise, industrial manufacturing, health industry, and environment industry collectively anchor demand, though their relative weight shifts as regional compliance priorities mature.
Key Challenges and Inflection Points
Despite the predictable growth path, the market faces structural challenges that will test vendor positioning and buyer decision-making in the coming years. The first challenge centers on regulatory alignment across jurisdictions. Monitoring standards increasingly demand tighter control over flow stability, pulsation limits, and post-calibration verification. Equipment that previously met baseline requirements may now fall short when deployed in regions adopting upgraded directives or stricter interpretation of existing standards. Manufacturers must balance compliance readiness with cost accessibility, particularly when serving multi-regional clients with divergent enforcement timelines.
The second challenge involves the tension between precision and portability. Occupational and environmental monitoring teams increasingly require devices that maintain laboratory-grade accuracy while fitting into confined workspaces, mobile monitoring setups, or rapid-deployment scenarios. Engineering teams must navigate competing design priorities: smaller form factors, extended battery performance, and reduced weight must not compromise calibration consistency or flow reliability. Buyers evaluating procurement options often face trade-offs between ruggedized configurations for heavy industrial settings and compact units optimized for indoor air quality or healthcare environments.
A third inflection point relates to market concentration and buyer leverage. The market remains moderately consolidated among established manufacturers, which creates both stability and pricing pressure. While leading vendors benefit from brand recognition, service networks, and long-standing compliance credentials, buyers are increasingly equipped with more information and alternative sourcing options. This dynamic pressures incumbents to justify premium positioning through demonstrable performance advantages, service quality, and integrated support ecosystems rather than heritage alone.
Core Growth Drivers Reshaping Demand
Technology Innovation and Performance Evolution
Product development is shifting from basic flow delivery toward smarter monitoring capability. Recent catalog updates and product introductions signal a clear direction: manufacturers are refining pump platforms to address flow stability, pulsation control, calibration ease, and connectivity for workflow integration. For example, updated personal sampling pump catalogs have introduced refined model specifications that emphasize usability, calibration verification, and application-specific configurations. Meanwhile, new portable air sampling pump additions reflect demand for lighter, more adaptable equipment in indoor air quality and environmental monitoring contexts.
This innovation trajectory matters because it connects directly to operator efficiency and data confidence. Devices that simplify calibration, reduce setup time, and maintain stable flow characteristics under variable conditions reduce the risk of non-compliant sampling results. In practical terms, engineering improvements are not merely product features; they are risk mitigation tools for industrial hygienists, safety managers, and environmental consultants who must produce defensible monitoring records.
Active Air Sampler Market
Regulatory and Standards Pressure as Compliance Catalyst
Regulatory frameworks continue to act as one of the strongest demand drivers. Occupational exposure monitoring depends on methods that require calibrated air sampling pumps with stable flow performance, and several standards reinforce this expectation. ISO 13137:2019, for instance, requires personal sampling pumps to maintain pulsation not exceeding 10 percent of the flow rate to support accurate workplace exposure monitoring. NIOSH NMAM methods reinforce the need for constant flow in analyses involving asbestos, lead, and crystalline silica. OSHA sampling methods further specify flow ranges and post-calibration verification expectations for personal air sampling pumps.
At the regional level, the EU Worker Exposure Directive revision has strengthened pulsation and flow stability requirements across member states, raising the compliance bar for organizations operating in Europe or supplying equipment into that market. These regulatory dynamics create a structural pull for equipment that can demonstrably meet evolving requirements. They also raise the stakes for buyers who must ensure that monitoring programs remain defensible during audits, incident investigations, or internal compliance reviews.
Demand-Side Shifts in Occupational Health and Environmental Monitoring
Demand is increasingly shaped by a broader interpretation of exposure risk. Industrial operations continue to represent a major application base, but health industry and environment industry usage is expanding as organizations broaden monitoring beyond traditional manufacturing floors. Healthcare settings, public facilities, and indoor air quality programs are driving interest in portable and area monitoring equipment that can support indoor environments, infection control-related airflow assessments, and general environmental surveillance.
Simultaneously, workplace safety culture is becoming more data-oriented. Safety teams are placing higher value on repeatable measurements, documented calibration, and equipment that integrates smoothly into field workflows. This shift favors vendors that can support not only the hardware but also the operational discipline surrounding sampling programs. In effect, the market is rewarding solutions that make compliance easier to execute consistently rather than only occasionally.
Supply Chain Realities and Cost Structure Considerations
Cost structures remain an important factor in procurement decisions, especially as organizations balance compliance budgets against broader operational spending. While the market is not experiencing volatile commodity shocks as a dominant narrative, equipment durability, service availability, and replacement part accessibility still influence total cost of ownership. Procurement teams increasingly evaluate pumps not as isolated instruments but as part of a monitoring system that includes calibration equipment, maintenance support, and training.
This broader purchasing lens benefits manufacturers with strong service networks and transparent support models. It also elevates the importance of product longevity and maintainability. In segments where buyers deploy equipment across multiple sites or rotating crews, reliability and service responsiveness can outweigh marginal price differences. As a result, suppliers that can deliver consistent field performance and predictable upkeep gain an advantage in multi-year purchasing decisions.
Competitive Landscape and Strategic Positioning
Established Players and Differentiating Strengths
The market features a set of well-known manufacturers with distinct product and service orientations. SKC Inc. has built recognition around personal air sampling pumps used in occupational exposure monitoring, with pump families designed for field sampling workflows. Sensidyne LP is associated with Gilian personal and high-flow air sampling pumps, along with calibrators supporting industrial hygiene and area sampling, which positions the company at the intersection of sampling and calibration equipment. Zefon International, Inc. offers personal and area environmental monitoring pumps, expanding its relevance across both occupational and environmental use cases. Casella USA provides personal air sampling pumps with connectivity features aimed at workplace exposure assessments, reflecting a strong emphasis on usability and field integration.
These companies differentiate not only through product specifications but also through how they support compliance workflows. Some compete on pump performance and pulsation control. Others emphasize calibration tools, training, documentation support, and field-ready design. The practical distinction for buyers often lies in whether the vendor can reduce the operational burden of sampling programs through integrated hardware, calibration consistency, and reliable after-sales support.
Recent Developments as Indicators of Strategic Focus
Recent company activities provide insight into how incumbents are navigating the market. Trade show participation by major pump and calibrator suppliers has continued through 2025, with exhibition activity at industry events highlighting ongoing engagement with occupational hygiene communities. These appearances are not mere marketing exercises; they function as channels for demonstrating flow performance, calibration practices, and equipment reliability to audiences that evaluate compliance-critical tools.
Product catalog updates have also underscored incremental innovation. Updated pump catalogs have introduced refined model details, while newer portable pump additions have broadened portfolios for indoor and environmental monitoring applications. Such moves suggest that established manufacturers are pursuing portfolio expansion and specification refinement rather than disruptive product replacement. This measured approach aligns with a market where compliance acceptance, service history, and user familiarity carry significant weight.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive structure appears likely to evolve through a combination of consolidation and targeted differentiation. Moderate market concentration gives leading firms room to defend positions through service networks and compliance credentials, but it also leaves space for specialized entrants in subsegments such as compact indoor air quality monitoring, improved connectivity for field data workflows, or region-specific compliance configurations. Potential consolidation may occur where service coverage, calibration support, and geographic reach become decisive purchase factors.
At the same time, fragmentation remains possible in application-specific niches. Buyers in healthcare environments, environmental consulting, or specialized industrial processes may prioritize features that larger generalist portfolios do not fully optimize. This creates opportunity for companies that can deliver focused solutions, provided they can also meet the compliance and reliability expectations associated with sampling instrumentation.
Forward-Looking Trends and Commercial Implications
Trend 1: Compliance-Driven Product Specifications Will Become a Baseline Expectation
Over the next three to five years, flow stability, pulsation control, and calibration verification are likely to transition from desirable features to baseline requirements in many procurement processes. As regional directives and occupational hygiene methods continue to reinforce consistent sampling performance, equipment that cannot document stable performance will face increasing friction in regulated environments. The commercial implication is clear: manufacturers that proactively align product design and documentation with evolving standards will reduce adoption barriers for compliance-focused buyers.
For procurement teams, this trend increases the importance of verification. Purchasing decisions will need to account not only for flow range and portability but also for how easily a pump can be calibrated, verified, and documented in routine use. Equipment that simplifies compliance workflows will likely command stronger preference in competitive bids.
Trend 2: Connectivity and Field Workflow Integration Will Gain Commercial Weight
As monitoring programs become more data-driven, devices with Bluetooth connectivity, streamlined field setup, and better integration into exposure assessment workflows will become more relevant. Connectivity does not replace measurement accuracy, but it can reduce administrative burden, improve record-keeping consistency, and support faster field decisions. In practical terms, the market is moving toward tools that help teams manage sampling programs more efficiently, not just collect samples more accurately.
Microbial Air Samplers Market
This trend opens commercial opportunities for vendors that can link hardware performance with workflow convenience. It also creates a differentiation path for companies that can demonstrate tangible improvements in setup time, calibration tracking, and exposure assessment documentation. The risk for buyers is overvaluing connectivity without confirming that core sampling performance still meets required standards.
PW Consulting Automotive & Machinery Research Center
Trend 3: Application Diversification Will Redefine Competitive Priorities
Industrial manufacturing will remain a core demand base, but growth in health industry and environment industry applications will encourage product strategies that address a wider range of monitoring contexts. Portable equipment for indoor environments, area sampling for environmental programs, and adaptable configurations for varying flow requirements will become more commercially important. Companies that can serve multiple application profiles without sacrificing compliance credibility will gain broader market relevance.
The corresponding risk is portfolio over-extension. Manufacturers expanding into new application areas must ensure that product claims, calibration support, and service models remain credible for each use case. Buyers in specialized settings will quickly distinguish between equipment that is genuinely suited to their environment and equipment that is merely marketed into it.
Strategic Recommendations for Decision-Makers
For Manufacturers and Suppliers
Prioritize compliance documentation and performance verifiability as core product assets. In a market where regulatory expectations continue to tighten, spec sheets alone are insufficient. Suppliers should ensure that product platforms clearly support flow stability, pulsation control, and calibration verification, and that this support is easy for customers to demonstrate in audits and field use. Equally important is service and calibration support; in compliance-driven purchasing, reliable after-sales infrastructure can be as influential as the instrument itself. Companies should also evaluate whether portfolio expansion into indoor air quality, environmental monitoring, or connectivity-enabled workflows creates genuine differentiation or merely broadens exposure without sufficient support depth.
For Investors
Assess exposure to regulatory-driven demand rather than relying solely on end-market growth narratives. Companies with strong positions in occupational hygiene, industrial hygiene, and compliance-related monitoring are better positioned to benefit from sustained standards pressure. Investment due diligence should examine calibration support, service networks, product acceptance in regulated environments, and the ability to maintain performance claims across multiple jurisdictions. Growth potential is likely to be strongest where vendors can combine product reliability with workflow-relevant features and credible documentation. At the same time, investors should monitor whether expansion into lower-margin application areas dilutes margin stability or operational focus.
For Procurement and Operations Leaders
Evaluate sampling pumps as part of a compliance system rather than as standalone hardware purchases. Total value should account for calibration consistency, field usability, service availability, and the ease of maintaining documentation across multiple sites or rotating crews. Where monitoring programs span different environments, consider whether standardized equipment reduces training burden and audit risk, or whether application-specific tools offer better performance despite increased procurement complexity. It is also prudent to confirm that any connectivity or workflow features do not distract from the fundamental requirement of stable, verifiable flow performance.
Closing Perspective
The air sampling pumps market is moving through a phase where regulatory expectations, workflow efficiency, and application diversification are reshaping purchasing logic. Growth is steady and structurally supported, but competitive advantage will increasingly depend on how well manufacturers translate performance and compliance readiness into practical field value. For buyers, the most effective decisions will come from evaluating equipment against both measurement integrity and operational burden. For suppliers and investors, the opportunity lies in aligning product strategy with the compliance-intensive, workflow-sensitive nature of modern exposure monitoring. Detailed segment-level data, regional breakdowns, and customized scenario analysis can further sharpen these decisions for organizations seeking a more precise path through the market's next phase of development.
For detailed analysis of this topic, please visit the official page: Air Sampling Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Enclosure Market: Why 7.5% CAGR and Strategic Shifts Reshape the Industry by 2032
By pmarketresearch, 2026-09-21
Navigating the Electric Enclosure Market: Strategic Trends and Commercial Opportunities
Market Overview and Pressing Challenges
The electric enclosure market has entered a phase of sustained expansion, with revenue projected to grow from approximately $5.5 billion in 2020 to just over $12.2 billion by 2032. This translates to a compound annual growth rate of 7.5 percent over the forecast period, signaling a market that is outpacing broader industrial equipment segments. The trajectory reflects more than cyclical demand; it is being reshaped by fundamental shifts in how electrical infrastructure is designed, deployed, and protected across multiple end-use ecosystems. Growth has been consistent across recent years, with revenue climbing through 2025 and accelerating into the mid-2030s as new infrastructure build-outs and modernization programs scale globally.
Despite the positive outlook, the industry faces structural friction that will separate agile participants from those relying on legacy operating models. First, the widening gap between standardized protection requirements and increasingly demanding environmental conditions is forcing rapid product adaptation. Enclosures must now accommodate submersion-level ingress protection, extreme thermal cycling, and corrosive exposure while maintaining accessibility for maintenance and compliance verification. Second, regulatory complexity is intensifying across jurisdictions. Compliance frameworks around environmental sealing, installation marking, and voltage-specific safety considerations are becoming more prescriptive, raising the cost of non-compliance and narrowing the window for generic solutions. Third, supply chain volatility and input cost fluctuations continue to pressure margins, particularly for manufacturers balancing metallic and non-metallic material portfolios against fluctuating steel, polymer, and casting costs. These dynamics are not isolated headwinds; they are reshaping competitive criteria and forcing a reevaluation of where value is created in the enclosure value chain.
PW Consulting Automotive & Machinery Research Center
Key Drivers Reshaping Market Trajectory
Technological Innovation and Performance Thresholds
Performance expectations for electric enclosures have evolved beyond basic containment. The integration of advanced sealing architectures, corrosion-resistant material formulations, and pre-engineered mounting interfaces is enabling faster deployment in environments that previously required custom engineering. Die-cast and rigid enclosure platforms are increasingly being offered with expanded ingress protection ratings and surface-mount options, reducing on-site fabrication time and improving consistency across installations. Simultaneously, climate control integration and thermal management features are becoming standard considerations for enclosures deployed in energy distribution, industrial automation, and data center-adjacent applications. This shift is moving enclosures from passive housings toward integrated protection systems, where reliability, serviceability, and environmental resilience directly influence procurement decisions.
Electronic Plastic Enclosure Market
Policy, Standards, and Compliance-Driven Demand
Regulatory and standards-based requirements are becoming a decisive filter in procurement. Enclosures used in electrical installations must align with recognized environmental protection classifications, installation marking directives, and safety considerations for systems operating up to higher voltage thresholds. In parallel, underground utility enclosures and power distribution assets are subject to specifications that address longevity, accessibility, and environmental safety. These requirements are not static; they are tightening in sectors where failure costs are high, such as EV infrastructure and data center power ecosystems. As a result, compliance capability is increasingly a market entry condition rather than a differentiator, pushing manufacturers to standardize certification pathways and design products that can satisfy multiple jurisdictional expectations without costly customization.
Demand-Side Shifts Across Industrial, Energy, and Utility Applications
Demand is being pulled from multiple directions. Industrial control systems continue to represent a substantial share of consumption, but growth is increasingly linked to modernization programs that replace aging enclosures with more durable, modular, and service-friendly alternatives. Energy and power applications are expanding as grid hardening, distributed generation, and EV charging infrastructure accelerate deployment cycles. At the same time, non-metallic conduit and enclosure accessories are gaining traction in applications where weight, corrosion resistance, and installation flexibility matter more than traditional metallic form factors. This diversification is broadening the addressable market while also fragmenting buying criteria, since project owners now weigh environmental exposure, maintenance access, longevity, and installation speed alongside base pricing.
Supply Chain and Cost Structure Evolution
Material availability and pricing dynamics remain central to margin management. Manufacturers with diversified material strategies—spanning steel, stainless steel, fiberglass, and polymer solutions—are better positioned to adapt to regional cost shifts and lead-time disruptions. Procurement teams are also placing greater emphasis on component standardization and interchangeability to reduce inventory complexity and streamline replacement cycles. The competitive advantage is increasingly tied to design efficiency, manufacturing scalability, and the ability to maintain certified product lines without sacrificing responsiveness. Companies that can align material selection with application-specific performance requirements while preserving cost predictability are capturing outsized share in a market where price competition alone is insufficient.
Competitive Landscape and Leading Strategies
Established Players and Strategic Positioning
The market remains moderately concentrated, with the largest players holding meaningful but not dominant shares, leaving room for specialized and regional competitors to thrive through application focus and service capabilities. Leading manufacturers are differentiating through a combination of material breadth, certification maturity, and application-specific engineering rather than volume pricing alone. For example, some firms emphasize rugged die-cast platforms with expanded ingress protection and flexible mounting configurations, targeting environments where reliability and installation simplicity are paramount. Others focus on enclosures designed for harsh conditions, pairing protection with climate control and EV-related inverter solutions to address integrated deployment needs. Utility and underground-focused manufacturers are leaning into below-ground and fiber-reinforced solutions for power distribution, while large industrial suppliers are expanding standard and non-metallic enclosure ranges to serve commercial and industrial projects at scale. Modular, freestanding, and hygienic-design offerings further illustrate how product families are being shaped around maintenance, sanitation, and configuration flexibility. Universal enclosure ranges that span metal, plastic, and polyester options are also being positioned for indoor and outdoor power distribution use, reflecting a push toward cross-environment applicability.
Recent Signals from the Market
Recent product and commercial activity underscores how companies are translating these strategies into executable moves. A major die-cast enclosure supplier introduced an IP68-rated flanged variant with added surface-mount options, extending the versatility of a rugged series for applications requiring higher environmental protection and easier installation alignment. In parallel, a non-metallic conduit specialist expanded its portfolio with new conduit bodies and gang boxes, reinforcing the shift toward lightweight, corrosion-resistant protection solutions for electrical installations. On the commercial side, a diversified enclosures and electrification player reported record first-quarter sales, orders, and backlog while raising full-year guidance, reflecting sustained demand across enclosure-adjacent segments and the confidence of customers in continued infrastructure investment. These developments point to a market where capability expansion, certification readiness, and demand visibility are reinforcing each other.
Market Structure Evolution
The competitive map is evolving along three axes. Consolidation is likely to continue among mid-tier players seeking scale in certification, distribution, and material procurement, while fragmentation will persist where regional compliance nuances, specialized materials, or niche application requirements create barriers to one-size-fits-all offerings. New entrants and adjacent players are finding opportunities in modular design, integrated thermal management, and non-metallic alternatives that lower installation friction. The broader trend is toward portfolios that balance standardized, certifiable platforms with configurable options that reduce custom engineering without sacrificing performance. Companies that can navigate this balance while maintaining regulatory alignment and supply chain resilience are best positioned to capture share as procurement teams increasingly prioritize lifecycle value over upfront cost.
Future Outlook: Trends and Commercial Implications
Higher Protection Standards as a Baseline Expectation
Over the next three to five years, stronger environmental protection and safety alignment will become baseline expectations rather than premium features. This will accelerate adoption of enclosures that already meet rigorous ingress and durability criteria, especially in EV infrastructure, data center power environments, and utility deployments where downtime and exposure risks carry significant financial consequences. The commercial opportunity lies in standardizing certified, high-protection platforms that reduce project risk and accelerate approval timelines. Manufacturers and solution providers that can offer repeatable compliance across multiple environments will see stronger demand pull, while late movers may face rising rejection rates and retrofit costs.
Modular and Configurable Designs as a Growth Multiplier
Configurability is emerging as a powerful growth lever. Modular enclosure systems, interchangeable mounting options, and pre-engineered accessories allow end users to adapt solutions to changing site conditions without redesigning from scratch. This modularity also supports maintenance, expansion, and replacement cycles, aligning product economics with long-term asset management priorities. The opportunity here is not simply offering more parts, but designing families that balance standardization with flexibility, enabling faster specification, reduced inventory burden, and lower field error rates. Solutions that make specification easier and retrofit less disruptive will gain preference in recurring industrial and energy projects.
Material Diversification and Non-Metallic Expansion
Material strategy will increasingly define competitive relevance. As installation environments become more varied and corrosive-resistance requirements rise, non-metallic and hybrid material solutions will capture additional share in specific applications, while stainless steel and fiber-reinforced options continue to serve harsh or sanitary-use conditions. Manufacturers that maintain disciplined material-to-application mapping, supported by reliable sourcing and clear certification documentation, will be better equipped to manage cost swings and meet project-specific constraints. The risk lies in over-indexing on any single material category without adequate application validation, which can create exposure to substitution pressure and regional cost volatility.
Actions for Decision-Makers
For Manufacturers and Solution Providers
Invest in platform-level design that supports multiple protection ratings, mounting configurations, and material options without fragmenting the core product architecture. Prioritize certification readiness and documentation as core capabilities, since compliance now functions as a procurement prerequisite in many sectors. Expand application-specific accessory ecosystems to reduce field customization, and align supply planning with material variability so that lead times and cost structures remain stable as demand scales.
Electric Control Cabinet Market
For Investors and Strategic Buyers
Evaluate exposure to segments where protection requirements are tightening fastest and where backlog visibility suggests durable demand. Look for companies that combine modular design, material flexibility, and strong compliance footprints, since these attributes support both share gain and margin resilience. Assess supply chain and sourcing strategies as indicators of future cost control, and consider how well-positioned a company is to serve energy distribution, industrial modernization, and infrastructure build-outs rather than relying on single-sector cyclicality.
For Procurement and End-User Teams
Shift evaluation criteria toward lifecycle protection, installation efficiency, and compliance certainty rather than lowest initial unit cost. Standardize on enclosure platforms that can be specified across multiple sites and environmental conditions to reduce specification errors and replacement complexity. Where possible, prioritize solutions with clear certification alignment and modular accessory support, since these reduce project risk and improve long-term maintainability as installations evolve.
For decision-makers seeking deeper segmentation, company-level performance benchmarks, regional deployment patterns, and application-specific sizing, a comprehensive market report can provide the granularity needed to translate these trends into precise commercial plans. Detailed breakdowns of product families, end-use demand, competitive positioning, and forward demand scenarios help shorten the path from insight to execution, especially when paired with tailored assessments of where to prioritize investment, sourcing, and specification strategy.
For detailed analysis of this topic, please visit the official page: Electric Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
HDTV Antennas Market: Why 7.12% CAGR and Residential Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the HDTV Antennas Market
1. Market Snapshot and Core Challenges
The over-the-air antenna sector has navigated a decade of steady expansion, driven by renewed interest in broadcast television, cord-cutting momentum, and incremental product innovation. Historical data from 2020 through 2025 reflects consistent top-line growth, with the market reaching a baseline valuation in the mid-$180 million range by 2025. Forward projections from 2026 to 2032 point toward continued expansion at a compound annual growth rate of approximately 7.12 percent, positioning the category as a resilient niche within the broader broadcast reception ecosystem. This trajectory suggests that antennas are no longer relegated to a legacy accessory but have evolved into a strategic hardware component for households and businesses seeking reliable, low-cost access to local television signals.
Several structural challenges now define the market's inflection points. First, the shift toward next-generation broadcast standards creates uncertainty around legacy hardware compatibility. As broadcasters explore voluntary transitions to enhanced digital formats, manufacturers and consumers must balance near-term purchasing decisions against the risk of premature standardization. Second, housing and installation dynamics remain a persistent friction point. Over-the-air reception depends heavily on line-of-sight placement, building materials, and outdoor mounting conditions. Regulatory protections exist to prevent unreasonable restrictions on antenna installation, yet enforcement variability and design constraints continue to complicate residential deployments in multi-unit buildings and dense urban environments. Third, consumer perception lags behind actual signal quality improvements. Many households still associate antennas with outdated image quality and limited channel access, creating an education gap that slows conversion among cord-cutters who have not yet tested modern reception hardware.
These challenges do not undermine the market's fundamentals, but they shape the pace and direction of adoption. In markets where digital transition momentum accelerates, antenna relevance grows alongside broadcast availability. In contexts where infrastructure, housing density, or regulatory clarity lag, demand remains fragmented and more sensitive to product performance and ease of installation.
2. Key Demand Drivers Reshaping the Category
The market's evolution is shaped by a mix of technological, regulatory, demand-side, and supply-side forces. Each driver interacts with the others, creating a dynamic environment where product performance, policy clarity, and user behavior converge.
Technology Innovation and Hardware Differentiation
Modern antenna designs have moved well beyond the basic antenna shapes of earlier decades. Amplified and non-amplified configurations now serve different use cases, while directional models address scenarios where signal strength and source alignment matter most. Amplification circuits help households overcome weak signal environments, but they also require careful tuning to avoid overdriving reception or amplifying noise. Directional designs, while representing a narrower portion of the installed base, provide specialized value for long-range reception and targeted signal capture. Beyond form factors, improvements in signal processing, weather-resistant materials, and streamlined mounting systems contribute to higher user confidence and lower installation friction. Manufacturers that combine clearer signal capture with intuitive setup experiences gain an advantage in a market where ease of use strongly influences repeat purchase and word-of-mouth adoption.
Mobile Phone Antenna Market
Policy and Regulatory Momentum
Regulatory activity has become a meaningful catalyst for market direction. The Federal Communications Commission advanced rulemaking in late 2025 to authorize permissive use of the next-generation broadcast television standard, supporting a voluntary broadcaster transition. Around the same timeframe, legislative attention intensified, with a broad group of lawmakers urging regulators to accelerate the transition so households could access the full benefits of enhanced broadcast capabilities. Alongside these developments, the Over-the-Air Reception Devices rule continues to protect consumer access by limiting unreasonable restrictions on antenna installation by homeowners' associations and similar bodies. Together, these forces create a policy environment that supports broadcast reception while leaving transition pace largely dependent on broadcaster willingness and market readiness. The practical effect is a market that benefits from enabling rules but must still contend with staggered adoption across regions and stations.
PW Consulting Automotive & Machinery Research Center
Consumer and Enterprise Behavior Shifts
Demand-side behavior has shifted as households and businesses reassess how they access video content. Cord-cutting continues to motivate consumers to explore free local broadcast options, especially in markets where streaming subscriptions accumulate costs or where internet reliability fluctuates. Residential use remains the dominant application context, reflecting the core pull of household entertainment, local news, and emergency broadcast access. At the same time, commercial use cases have expanded in more specialized scenarios, including hospitality, shared living facilities, and mobile or recreational settings where reliable off-network reception adds value. In both cases, the strategic appeal of antennas lies in cost efficiency and independence from recurring subscription fees, provided the hardware can deliver consistent signal quality and user-friendly setup.
Supply Chain and Cost Structure Considerations
Cost dynamics in manufacturing, components, and distribution influence both pricing strategy and margin management. The antenna category benefits from relatively modular production compared with more complex electronics categories, yet material costs, logistics variability, and the performance requirements of outdoor-rated hardware still shape product economics. Suppliers that can standardize reliable internal components while maintaining outdoor durability, weather resistance, and low noise amplification are better positioned to manage cost volatility. Distribution has also become more complex as customers expect both direct purchasing options and retail availability to compare products. For manufacturers, balancing channel strategy with product consistency and regional support can determine how efficiently growth translates into profitability.
3. Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with no single company dominating the category and room for differentiated positioning across product families, use cases, and distribution models. Core players illustrate how manufacturers compete on performance, brand trust, and specialization rather than scale alone.
Antennas Direct has built its identity around digital and HDTV antenna systems for over-the-air reception, with indoor and outdoor models aimed at households seeking free local HDTV channels. Its market narrative emphasizes cord-cutting and access to local broadcast without recurring fees, aligning product positioning with the broader consumer shift away from traditional pay television. Winegard Company competes with a focus on outdoor and indoor reception solutions and long-range VHF/UHF performance, including models designed for residential and recreational vehicle use. This dual emphasis allows the company to address both stationary home reception and mobile or semi-mobile use cases where signal range and durability matter. ANTOP Antenna operates with a broader portfolio spanning indoor, outdoor, and marine HDTV antennas, alongside signal distribution products. Its export-oriented approach and wider application coverage give it a distinct footprint in both consumer and specialized environments where multi-channel distribution and reception resilience are priorities.
These companies illustrate three strategic advantages that matter in this market. First, product clarity helps reduce purchase hesitation; customers often compare amplified versus non-amplified options and need guidance that matches their signal environment. Second, installation and usability are competitive differentiators, since a well-performing antenna that is difficult to mount or configure can underperform in real-world adoption. Third, brand trust in over-the-air reception depends on consistent signal claims, support resources, and realistic expectations around range and channel availability.
Market evolution is likely to continue along both consolidating and fragmenting paths. Larger electronics and accessory players may seek adjacency to expand their home entertainment portfolios, while specialized antenna manufacturers may deepen their lead in particular use cases such as long-range reception, marine settings, or streamlined indoor designs. New entrants can still find room by targeting underserved scenarios, including properties with challenging signal environments or users who need compact, aesthetics-conscious designs. The result is a competitive landscape that rewards focused engineering, credible product claims, and channel alignment rather than pure scale.
4. Forward-Looking Trends and Commercial Implications
Looking ahead, several trends are likely to shape the market over the next three to five years, with clear implications for product strategy and commercial positioning.
One important trend is the gradual influence of next-generation broadcast standards on hardware expectations. As broadcasters evaluate voluntary transitions, the market will likely see a dual-track environment in which legacy-compatible antennas remain relevant for the near term while enhanced-format compatibility becomes a more prominent question over time. The commercial implication is that manufacturers and retailers should avoid overcommitting to a single transition assumption too early, while still preparing product messaging and engineering roadmaps for evolving signal environments. The uncertainty here is not whether broadcast technology will continue evolving, but how quickly-station-by-station and region-by-region adoption will occur.
A second trend is the growing importance of installation experience and signal predictability. As customers compare antennas against streaming alternatives, the decision often comes down to whether the antenna will reliably deliver local channels with minimal setup hassle. Products that simplify placement, improve signal capture consistency, and provide practical guidance for different housing types can reduce the gap between purchase intent and satisfied use. The opportunity lies in transforming antennas from a technically variable purchase into a more predictable home entertainment solution. The risk is that overpromising on range or channel counts can undermine trust if real-world results vary by location.
A third trend is the continued expansion of specialized and niche applications. While residential use dominates overall demand, commerical and specialized deployments create higher-value scenarios where durability, distribution, and long-range performance are especially important. Marine, recreational, and shared-facility contexts can benefit from products designed for specific environmental or operational needs. The related risk is that these niches remain small in aggregate and require targeted support, documentation, and channel relationships to scale efficiently.
Across these trends, the common thread is that antennas are increasingly judged not as isolated hardware, but as part of a broader home and commercial connectivity experience. That framing creates opportunities for manufacturers, distributors, and buyers who treat reception quality, ease of installation, and compatibility planning as core value drivers rather than secondary features.
5. Strategic Recommendations for Decision Makers
Different stakeholders face different priorities, but several actionable themes apply across the board.
For manufacturers and product leaders, engineering focus should prioritize real-world signal performance and installation simplicity alongside feature differentiation. Clear guidance on when amplified, non-amplified, or directional designs make sense can reduce returns and improve customer satisfaction. In addition, positioning products with credible expectations around range, signal conditions, and compatibility helps build trust in a category where user disappointment often stems from mismatched assumptions rather than product failure. Companies should also monitor broadcast transition developments closely and align product roadmaps to maintain flexibility without making premature bets on a single standard path.
For investors and market observers, the category offers a stable growth profile with a moderate growth rate and multiple expansion levers, including product segmentation, specialized applications, and distribution optimization. The more important question is not whether the market will grow, but which players capture value through better product-market fit, stronger channel execution, and credible transition readiness. Investment theses should account for the fact that competitive advantage in this space tends to come from specialization and customer experience as much as from scale.
For procurement teams and commercial buyers, selection should depend on site conditions, signal environment, and intended use rather than on headline specifications alone. Residential buyers should weigh mounting constraints, indoor versus outdoor needs, and the practical benefits of amplification based on local reception quality. Commercial and specialized buyers should assess durability, distribution requirements, and long-term maintenance considerations. In both cases, documented performance expectations and support resources can be as valuable as hardware cost when evaluating total value.
Automobile Antenna Market
For organizations seeking a deeper, segment-level view of revenue splits, regional dynamics, application breakdowns, and concentration patterns, a more detailed research package can provide the refined data needed to support planning, pricing, and competitive benchmarking. PW Consulting offers tailored market intelligence that translates category-level trends into targeted decisions, with the option to access full segmentation, company profiles, and scenario-based analysis through the complete HDTV Antennas Market research report.
For detailed analysis of this topic, please visit the official page: HDTV Antennas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Combustion Analyzer Market: Why Asia-Pacific’s Surge Drives 6.49% CAGR Through 2032
By pmarketresearch, 2026-09-21
Combustion Analyzer Market: Strategic Trends & Commercial Opportunities Through 2032
The combustion analyzer market has entered a phase of steady, structurally supported expansion. From a baseline of approximately $897 million in 2020, the sector has consistently grown to reach $1,175 million by 2025, with projections pointing toward $1,823 million by 2032. This trajectory, supported by a compound annual growth rate of roughly 6.49 percent during the forecast window, reflects a market that is no longer reacting to short-term fluctuations but is instead being shaped by enduring regulatory, technological, and operational shifts. For executives, investors, and procurement teams, the question is no longer whether the market will grow, but where value will concentrate and how to position operations ahead of the next inflection point.
Market Snapshot: Scale, Momentum, and Structural Realities
The overall market footprint tells a clear story of incremental but reliable expansion. Historical data from 2020 through 2025 shows a market that absorbed pandemic-era supply disruptions, recovered through operational normalization, and accelerated as environmental compliance became a baseline requirement rather than a voluntary initiative. The forward projection from 2026 to 2032 extends that momentum, with annual valuations climbing steadily and crossing the $1.6 billion threshold by the end of the decade. This is not a speculative boom scenario. It is a demand curve anchored in compliance obligations, equipment modernization cycles, and the steady adoption of precision measurement tools across industrial, commercial, and residential settings.
Beneath the headline numbers, the market exhibits moderate fragmentation. The top three firms account for roughly 27.4 percent of total revenue, while the top five reach approximately 32.6 percent. This concentration pattern suggests a landscape where scale advantages exist but have not yet hardened into an oligopolistic barrier. Regional and application-level demand is distributed across multiple geographies and end-use environments, with industrial operations, HVACR servicing, and building compliance programs forming the core consumption base. The current structure provides room for targeted expansion, precise product positioning, and selective consolidation without forcing a wholesale market reset.
Key Challenges and Inflection Points
Despite the favorable growth trajectory, the market faces structural pressures that will determine which players capture lasting share and which remain stuck in price competition. Three challenges stand out as immediate strategic considerations.
First, regulatory complexity is accelerating faster than product standardization. Emissions verification, technician certification requirements, and device specifications are being updated at the state and municipal level, creating a patchwork of compliance expectations. Manufacturers must navigate differing measurement protocols, documentation requirements, and approval pathways without diluting product usability for field technicians. Companies that design for regulatory adaptability rather than single-market optimization will gain a measurable advantage.
Second, sensor durability and field service economics are becoming a competitive differentiator. Combustion analyzers operate in environments with high particulate loads, temperature fluctuations, and repeated exposure to flue gases. The total cost of ownership now includes calibration intervals, sensor replacement logistics, and downtime during verification cycles. As end-users grow more sophisticated, purchasing decisions are shifting from upfront unit price to lifecycle cost, reliability, and support response times. This raises the stakes for manufacturers that can reduce service friction and maintain measurement integrity over extended deployment periods.
Third, the market is approaching a technology adoption crossroads. Digital integration, wireless connectivity, and automated data capture are moving from premium features to baseline expectations in many commercial and industrial applications. Yet not all product lines are transitioning at the same speed, and the gap between legacy instrumentation and next-generation connected devices is widening. Firms that treat connectivity as a cosmetic upgrade risk losing relevance, while those embedding data workflows into the core measurement experience can position their tools as operational efficiency platforms rather than standalone test devices.
Key Drivers Shaping Market Direction
Technology Innovation and Measurement Precision
The most durable driver in the combustion analyzer market remains continuous improvement in measurement accuracy, response speed, and user workflow design. Modern devices are increasingly built around faster sensor stabilization, clearer visual interfaces, and streamlined test sequences that reduce technician error. This matters because combustion analysis is not a passive measurement task. It directly affects furnace efficiency, emissions compliance, and safety verification. When a device shortens setup time, simplifies sensor orientation, or presents interpretable readings under field conditions, it lowers the barrier to consistent, high-quality testing.
Recent product introductions illustrate how innovation is being framed around practical field performance rather than abstract specifications. Newer models have emphasized large touchscreen interfaces, field-replaceable sensor configurations, and testing workflows that combine pressure, temperature, and gas concentration readings in a single session. These design choices reflect an understanding that technicians value speed, readability, and reduced dependency on external service center turnaround. Innovation that translates into faster verification and fewer re-tests is increasingly the standard by which competitive devices are judged.
PW Consulting Automotive & Machinery Research Center
Policy and Regulatory Environment
Regulatory momentum continues to shape purchasing behavior across HVACR, industrial combustion, and building operations. Training requirements are tightening, and certification expectations are moving toward more structured combustion analysis protocols. In several markets, technician education programs now emphasize multi-parameter testing, including oxygen, carbon monoxide, carbon dioxide, temperature, and pressure, to ensure that servicing work aligns with emissions and safety expectations. This is not simply a matter of compliance documentation. It is reshaping how organizations train personnel, select equipment, and verify burner performance.
At the operational level, institutional buyers are increasingly specifying analyzer models that meet documented compliance and verification expectations. School districts, municipal facilities, and commercial building operators are incorporating combustion analyzer standards into monitoring and reporting processes. Where verification programs name specific product families for burner performance checks, that specification power can influence procurement patterns over multiple budget cycles. For manufacturers, this dynamic creates both an opportunity and a dependency: being recognized in official verification workflows can stabilize demand, but it also raises the stakes for maintaining certification readiness, firmware consistency, and documented support coverage.
Demand-Side Shifts in Commercial and Industrial Operations
Demand is being reinforced by a broader shift toward efficiency optimization rather than reactive maintenance. Facility operators and service contractors are looking to reduce fuel waste, minimize unsafe combustion conditions, and standardize testing procedures across multiple sites. This pushes combustion analyzers beyond occasional compliance checks and into routine tuning, performance benchmarking, and preventive service workflows.
In parallel, the commercial HVACR and residential service segments are expanding their reliance on portable, field-ready equipment. Technicians need devices that travel easily, operate reliably in varied environments, and produce clear records for customer reporting. As service businesses scale, they also value integration with dispatch, documentation, and remote support tools. The result is a demand profile that favors equipment combining measurement accuracy with operational convenience, wireless data handling, and support structures that reduce downtime when recalibration or sensor replacement is required.
Supply Chain and Cost Structure Evolution
Cost structure pressures are influencing product strategy in ways that go beyond simple component pricing. Sensor supply, calibration logistics, and service part availability remain central to profitability and customer satisfaction. Manufacturers that can streamline field service processes, standardize replaceable components, and reduce turnaround time for recertification are building an economic advantage that is difficult for competitors to replicate quickly.
This environment is also rewarding business models that bundle equipment with predictable support. Guarantees that shorten recertification cycles or provide rapid replacement options are becoming relevant because they address a practical pain point: field downtime during compliance-critical periods. As labor costs rise and scheduling windows tighten, the market increasingly values vendors that can keep devices operational without prolonging service interruptions. The implication is clear. Competitive advantage is shifting partly from hardware novelty to service infrastructure and field economics.
Competitive Landscape and Leading Strategies
Differentiation Beyond Specification Sheets
The competitive field includes established instrument manufacturers, safety-focused equipment suppliers, and specialized measurement companies with strong regional or application-specific footprints. What separates the stronger positions is not simply product breadth, but the ability to align device design with real-world certification, service, and workflow needs. Leading players have been shaping their offerings around three recurring themes: usability in the field, support responsiveness, and alignment with recognized safety or efficiency standards.
Several firms have positioned themselves around residential and commercial servicing, where ease of use, quick sensor replacement, and clear display formatting matter heavily. These companies often emphasize practical support features such as guarantee structures, recertification speed, and integrated wireless connectivity that helps technicians document results without interrupting workflow. In this segment, the most effective differentiation is often operational: reducing friction during testing, reporting, and maintenance rather than merely adding features.
In the industrial segment, the emphasis shifts toward measurement robustness, multi-gas capability, and integration with broader burner and boiler control environments. Products designed for comprehensive flue gas analysis and continuous or semi-continuous monitoring are built for higher-duty cycles and more demanding process conditions. The competitive edge here tends to rest on measurement reliability, calibration stability, and the ability to fit into industrial maintenance and emissions verification routines without excessive setup complexity.
Strategic Positioning Among Core Players
The competitive conversation is not monolithic. Some manufacturers compete primarily on precision and industrial-grade measurement platforms, while others compete on portability, field service speed, and technician-friendly interfaces. A firm entering or expanding in this market must decide which value proposition it can defend over time. The more durable strategies are those that connect product design to recurring service economics, recognized compliance expectations, and user workflows that reduce training burden.
A notable pattern in recent activity is the emphasis on third-party recognition and practical certification alignment. Recognition from industry training or emissions-focused organizations can strengthen credibility with service contractors, institutional buyers, and HVACR professionals who need equipment aligned with accepted safety and efficiency standards. Similarly, product launches that highlight enhanced testing functions, sensor flexibility, or faster support response are aimed at converting technical capability into field-level advantage. These moves suggest a market where credibility, usability, and support infrastructure are becoming as important as raw measurement performance.
Consolidation, Speciation, and New Entrant Dynamics
The market is not trending toward rapid consolidation, but selective concentration is likely. Mid-sized and smaller firms may gain traction by specializing in niche applications, regional compliance workflows, or specific technician segments. Larger players, meanwhile, will likely pursue portfolio breadth, cross-segment support, and integration across residential, commercial, and industrial lines. This creates a landscape where both specialization and scale can succeed, provided each is matched to the right demand context.
For new entrants, the barrier is not simply building a functional analyzer. The challenge is entering a market where technicians, service companies, and institutional buyers already have preferences shaped by training, certification, service logistics, and proven reliability. Disruptive entry therefore tends to come from improving workflow economics, accelerating support turnaround, or addressing an underserved compliance or regional need rather than from offering marginally improved hardware alone.
Forward Outlook: Three Trends to Watch Through 2032
Trend One: Compliance-Linked Procurement Becomes More Structured
Over the next three to five years, purchasing decisions are likely to become more tightly connected to documented compliance workflows. Where combustion analysis is already part of emissions verification, technician training, or burner performance checks, buyers will increasingly prefer equipment that can be clearly tied to approved testing protocols and supported by predictable calibration and service processes. This trend favors manufacturers that can maintain certification readiness, provide stable firmware and documentation, and align devices with the expectations of training programs and institutional monitoring routines.
The commercial opportunity lies in becoming the de facto tool for recurring verification programs. Once a device family is embedded in training, reporting, and compliance cycles, demand becomes more predictable and less sensitive to marginal price competition. The risk is that regulatory expectations may diverge across jurisdictions, forcing manufacturers to maintain multiple compatibility paths or adapt product configurations more frequently than anticipated.
Trend Two: Connected Field Workflows Gain Mainstream Adoption
Connectivity is moving from a premium differentiator to a standard expectation across many commercial and residential service applications. Wireless data transfer, mobile application integration, and streamlined reporting will increasingly shape purchasing decisions because they reduce administrative burden and improve record-keeping for compliance and customer documentation. Devices that treat data capture as an afterthought will face growing pressure from tools that make testing results immediately available for dispatch records, service reports, and performance tracking.
The strategic opportunity is to design around the full field workflow rather than the measurement event alone. This includes simplifying how results are stored, shared, and re-tested, as well as ensuring that app or wireless features support rather than complicate technician tasks. The uncertainty here is that connectivity requirements can expand in unanticipated directions, and over-engineering software experiences can distract from measurement reliability and support speed.
Trend Three: Service Economics Drive Competitive Advantage
As the market matures, competitive advantage will be determined more by total cost of ownership than by initial device pricing. Sensor longevity, field-replaceable design, calibration logistics, and support response times will increasingly shape procurement decisions, particularly for organizations managing multiple technicians or multiple service sites. Companies that reduce downtime, simplify sensor replacement, and offer predictable recertification pathways will be better positioned to retain customers through operational reliability rather than promotional pricing.
This trend creates a clear opportunity for manufacturers and distribution partners to build service-led differentiation. The tradeoff is that service infrastructure requires ongoing investment and coordination. Firms that underestimate the operational burden of field support may find that hardware sales growth is offset by dissatisfaction, slower repeat purchases, or erosion of referral-based demand within technician networks.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Align product development with field workflow realities rather than specification competition alone. Prioritize sensor replaceability, calibration turnaround, display clarity, and support structures that reduce technician downtime. Where possible, position devices to fit into training, compliance, and verification workflows that generate recurring demand. Invest in credible third-party alignment and documentation that supports institutional specification. Avoid overloading product lines with features that do not improve measurement reliability or service economics.
Mercury Analyzer Market
For Investors and Strategic Capital Allocators
Focus on companies with defensible service models, recurring compliance exposure, and product families that can scale across residential, commercial, or industrial segments without losing usability. The strongest investment cases in this market are likely to come from firms that combine stable measurement performance with predictable support logistics and clear positioning in technician-driven procurement networks. Be cautious of businesses that rely primarily on pricing pressure or undifferentiated hardware features without a service or workflow advantage.
Ozone Analyzer Market
For Procurement Teams and End-User Buyers
Evaluate combustion analyzers through total cost of ownership, service responsiveness, and compliance alignment rather than purchase price alone. Consider how devices will fit into technician training, documentation requirements, and recurring verification cycles. Where institutional specifications or verification programs are involved, confirm that the selected equipment maintains certification readiness, consistent firmware support, and accessible calibration or sensor replacement pathways. Procurement decisions made around operational reliability and compliance fit tend to reduce downstream risk more effectively than short-term cost minimization.
Closing Perspective
The combustion analyzer market is moving from a compliance-driven baseline toward a more structured, workflow-oriented growth environment. Demand is being reinforced by tighter training expectations, more formalized verification practices, and a growing preference for equipment that integrates measurement accuracy with service speed and data usability. The firms that will lead over the next several years are those that treat combustion analysis not as a standalone instrument category, but as part of a broader operational chain linking technician training, field testing, compliance documentation, and equipment support.
For organizations seeking a deeper view of segment dynamics, regional demand patterns, competitive positioning, and scenario-based forecasts, the full PW Consulting market research report provides a more detailed breakdown of the data and strategic implications behind this overview.
For detailed analysis of this topic, please visit the official page: Combustion Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bakery Processing Equipment Market 2026-2032: What the 7.6% CAGR Reveals About Bread Dominance
By pmarketresearch, 2026-09-21
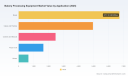
Bakery Processing Equipment Market: Navigating Strategic Shifts and Growth Opportunities Through 2032
Market Overview and Core Challenges
The global bakery processing equipment market has demonstrated resilient expansion over the past half-decade, evolving from a mature operational category into a strategically contested space shaped by automation, hygiene mandates, and shifting consumption patterns. Market valuations have climbed steadily, crossing the 16 billion USD threshold in 2025 and extending toward an estimated 27.5 billion USD by 2032. The compound annual growth rate over the forecast horizon sits at approximately 7.6%, signaling sustained momentum rather than speculative hype. This trajectory is not merely a function of volume replacement; it reflects a structural upgrade cycle as bakeries, contract manufacturers, and industrial food producers modernize lines to capture consistency, labor efficiency, and regulatory compliance.
Despite the favorable macro direction, the industry operates at a critical inflection point. Three interconnected challenges define the current operating environment. First, the capital intensity of modernization has increased as equipment specifications tighten around food safety, energy efficiency, and integrated data connectivity. Operators must justify line-level investments against volatile input costs and margin compression, making retrofit decisions more complex than outright replacement. Second, the divergence between retail-facing craft bakeries and high-volume industrial producers has widened the technology gap. Solutions that excel in throughput and repeatability often struggle to translate into flexible, small-batch environments, while highly modular systems can introduce integration friction at scale. Third, supply chain normalization remains uneven across regions. Component availability, lead-time predictability, and localized service coverage continue to influence not only deployment speed but also total cost of ownership, forcing manufacturers to rethink inventory buffers and partner ecosystems.
The competitive terrain mirrors this complexity. Market concentration remains moderate, with the top three players collectively holding a significant share and the top five extending further, yet no single vendor dominates outright. This fragmentation creates room for differentiated positioning but also raises the bar for service networks, application engineering, and post-sales support. As a result, purchasing decisions are increasingly evaluated through a lifecycle lens rather than a sticker-price comparison, with operators weighing uptime guarantees, sanitation access, and upgrade pathways alongside initial specifications.
Key Drivers of Market Change
Technology innovation is reshaping what processing equipment can deliver on the line. Advanced oven and proofing systems now combine tighter thermal zoning with automated load handling, reducing variability in volume, crust development, and yield. Mixers and continuous blending platforms have evolved to support more consistent dough rheology across formulations, while sheeters, molders, and dividers increasingly integrate vision-assisted adjustment and recipe-driven changeovers. These advances are not about marginal speed gains alone; they are about predictable repeatability in an environment where labor availability and skill mix are under pressure. Equipment that can reduce manual intervention while preserving product character is becoming a competitive necessity rather than a luxury.
Regulatory and sanitary design expectations are adding a parallel layer of change. Updated hygiene and sanitation frameworks for bakery and food service equipment are reinforcing minimum protection requirements, component accessibility, and cleanable construction. Concurrently, accepted-equipment guidance for adjacent processing categories is shaping expectations around sanitary design, even for lines that span bakery and dairy or meat-adjacent workflows. For manufacturers, this translates into a design imperative: equipment must be engineered for faster washdown, fewer harborage points, and documentation-friendly maintenance routines. For buyers, compliance is increasingly tied to uptime and risk management, because non-hygienic architecture can create bottlenecks during audits and production restarts.
Demand-side dynamics are equally influential. Consumer preferences continue to reward variety, freshness, and format flexibility, but the underlying purchasing behavior among commercial buyers is driven by consistency and labor economics. Retail chains, foodservice operators, and contract bakeries are seeking lines that can switch between SKUs with minimal downtime, handle seasonal demand spikes, and maintain quality across shifts. At the same time, the broader food ecosystem is experiencing record-level consumption trends in adjacent categories, underscoring the ongoing relevance of bakery-adjacent product formats and ingredient flows. This wider demand backdrop reinforces the strategic value of equipment that can integrate cleanly into multi-product environments rather than operating as isolated islands.
Cost structure shifts are also influencing investment logic. Energy usage, maintenance frequency, and component lifecycle costs are receiving greater scrutiny as operators look beyond acquisition price. Equipment that offers better thermal recovery, smarter startup sequencing, and modular serviceability can lower operating expense over time, which matters in an environment where margins are sensitive to ingredient volatility and wage pressures. In parallel, regional supply dynamics are encouraging more localized design and service strategies, especially where logistics costs or lead-time variability could disrupt planned expansions. The net effect is that value is being redefined around reliability, service responsiveness, and operational adaptability.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of established multinational specialists and regionally strong exporters, each pursuing distinct positioning strategies. Alfa Laval brings a strong heritage in hygienic processing, emphasizing systems built for sanitary handling and integration into demanding food environments. Buhler offers comprehensive line configurations spanning dough handling, mixing, and sheeting, which supports buyers seeking continuity across station-level transitions. Belshaw Adamatic Bakery Group focuses on dough production and sheeting technology, targeting applications where thickness control, throughput stability, and repeatability are central. AMF Bakery Systems delivers integrated solutions for retail and commercial settings, aligning equipment with formats and throughput profiles that vary by channel.
Coperion contributes a distinct angle through continuous mixing and processing approaches for dough and ingredients, appealing to operators seeking steady-state performance and reduced batch variability. Reading Bakery Systems supplies automated ovens and proofers, where thermal control and automation are prominent value drivers. Porlanmaz Bakery Machinery Co. illustrates the export-oriented route, serving a broad international footprint and demonstrating how regional manufacturers can scale through cost-competitive engineering and wide distribution reach. Lestov adds further diversity with commercial baking and induction-based systems, reflecting the ongoing presence of regional specialists that address local format preferences and service expectations.
The strategic differentiation among these players tends to cluster around three themes. One is application depth: vendors that can map equipment capabilities to specific dough types, product formats, and throughput requirements often secure stronger positions with end-users who prioritize engineering fit. Two is integration and automation: systems that reduce manual handling, improve changeover efficiency, and support consistent process control are increasingly favored as labor and quality pressures rise. Three is service and support architecture: installation, commissioning, training, spare parts availability, and regional responsiveness are becoming decisive in competitive bids, especially for operators running multiple shifts or operating in geographies with limited technical coverage.
Bakery Machine Market
Market structure is evolving along two directions at once. Consolidation is plausible where scale benefits matter in engineering, global service coverage, and component sourcing, particularly for large industrial lines. At the same time, fragmentation persists where flexibility, localized support, and format specialization provide advantages for smaller or regionally focused producers. Trade events such as the International Baking Industry Exposition continue to function as a pulse point for the industry, bringing together suppliers, buyers, and technology demonstrations in a setting that surfaces both emerging capabilities and buyer priorities. This combination of consolidation pressure and continued specialization suggests that competitive advantage will increasingly depend on how well companies align product roadmaps with real-world operating conditions rather than on broad brand presence alone.
Forward Outlook: Trends and Commercial Implications
One of the most consequential trends over the next three to five years is the intensification of hygienic design and automation as a combined requirement. Equipment will increasingly be evaluated not just for throughput but for how readily it supports sanitation routines, reduces contamination risk, and maintains performance after repeated washdowns. This is likely to accelerate demand for lines with improved accessibility, durable finishes, and process controls that can be validated and documented with less manual effort. For manufacturers, this trend opens opportunities in retrofit kits, service partnerships, and design updates that make legacy lines more compliant without full replacement.
A second trend is the continued push toward modular, multi-format flexibility. As product portfolios expand and seasonal variation persists, bakeries and contract manufacturers will favor equipment that can accommodate formulation changes, size adjustments, and batch-to-continuous shifts with minimal disruption. Systems that offer faster recipe recall, simplified tooling changes, and clearer process visibility will be better positioned to capture demand from operators managing diverse output profiles. The commercial implication is clear: flexibility is no longer a niche feature; it is becoming a baseline expectation for many mid-volume and multi-SKU environments.
A third trend is the growing weight of total cost of ownership in purchasing decisions. Energy consumption, maintenance intervals, component durability, and service availability are moving up the evaluation ladder as operators compare options across multi-year horizons. This favors suppliers that can demonstrate dependable uptime, transparent service coverage, and upgrade paths that extend equipment life. It also creates room for service-led business models, predictive maintenance support, and financing structures that align capital outlay with operational outcomes. At the same time, uncertainty remains around regional supply consistency, labor availability for installation and service, and the pace at which regulatory expectations become fully embedded in procurement standards. Companies that treat these variables as strategic inputs rather than background noise will be better prepared to sequence investments and manage portfolio risk.
Strategic Actions for Decision-Makers
For equipment manufacturers, the priority is to tighten the link between technology roadmaps and operational reality. Engineering investments should emphasize sanitary accessibility, changeover efficiency, and integration-friendly architectures that reduce friction for the buyer. Equally important is building service and parts strategies that match the geographic footprint of demand, because responsiveness often determines repeat business and referenceability more than feature lists alone. Where possible, offering modular upgrade options can help customers extend asset life while aligning with evolving compliance and throughput needs.
For investors, the opportunity lies in identifying operators with durable differentiation in application engineering, service coverage, and total-cost positioning rather than those competing primarily on price. Segments with stronger demand for consistent dough handling, hygienic design, and flexible automation are likely to sustain interest, but due diligence should account for exposure to regional supply dynamics and the execution risk involved in scaling service networks. A clear view of which product families are tied to structural demand versus cyclical replacement can improve capital allocation and timing.
PW Consulting Automotive & Machinery Research Center
For buyers and procurement teams, the practical move is to evaluate equipment through a multi-year operating lens. Prioritize not only technical specifications but also sanitation access, maintenance complexity, changeover behavior, and supplier support coverage. Where possible, align procurement with anticipated regulatory expectations and labor constraints, since these factors will shape both compliance burden and operational resilience. For larger programs, staging investments around flexibility and upgrade readiness can provide optionality in a market where product mix and standards continue to evolve.
Food Processing Equipment Market
For any stakeholder looking to move from directional insight to implementation planning, the next step is to ground decisions in segment-level detail and scenario-based evaluation. The broader market trajectory points toward sustained growth, but the most valuable choices will depend on how specific product categories, regional conditions, and customer channels interact over the forecast period. A detailed review of segmentation dynamics, competitive positioning, and regional demand patterns can help translate the macro picture into a practical roadmap for capital deployment, partnership choices, and capability investments.
For detailed analysis of this topic, please visit the official page: Bakery Processing Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Marine Propeller Market 2026–2032: The 6.6% CAGR, Asia Pacific Shift, and What Really Drives Growth
By pmarketresearch, 2026-09-21
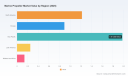
The Marine Propeller Market: Navigating Strategic Shifts and Commercial Opportunities (2026–2032)
The marine propeller market has entered a phase of structural growth, defined by steady expansion, evolving technological standards, and shifting regional demand patterns. Valued at approximately $4.48 billion in 2025, the sector is projected to reach $6.94 billion by 2032, reflecting a compound annual growth rate of 6.6 percent across the forecast period. This trajectory follows a measured recovery from the 2020–2023 cycle, where market valuations fluctuated between $3.56 billion and $3.84 billion amid supply chain disruptions, fluctuating shipbuilding activity, and varying regional investment rates. By 2024, momentum had clearly accelerated, crossing the $4.1 billion threshold and establishing a stronger base for the next decade. The numbers alone, however, tell only part of the story. Beneath the headline growth lies a market undergoing meaningful transformation in how propulsion systems are designed, manufactured, regulated, and integrated into broader maritime operations.
Stern Drive Boat Propeller Market
For executives, investors, and procurement leaders operating in or adjacent to the marine sector, understanding these shifts is no longer optional. Propeller technology sits at the intersection of vessel efficiency, emissions compliance, operational cost management, and regional industrial policy. As shipowners weigh lifecycle performance against upfront capital, and as manufacturers adapt to new material, production, and regulatory realities, strategic positioning will separate winners from followers. This analysis examines the core challenges shaping the market, the forces driving change, the competitive dynamics already in motion, and the strategic implications that will matter most through 2032.
Market Snapshot and Structural Baseline
The current market profile reflects a maturation phase rather than a speculative boom. Growth is broad-based but uneven, with certain applications and regions pulling ahead as vessel replacement cycles, naval modernization programs, and recreational boating demand align with more favorable economic conditions. The overall market trajectory from 2020 through 2032 suggests that while the sector weathered short-term volatility, underlying demand drivers have strengthened rather than faded. Revenue expansion is now supported by a combination of fleet renewal, efficiency mandates, and renewed investment in both commercial and leisure vessel segments.
Concentration patterns indicate that a relatively small group of established players continues to command a majority of market share, yet the landscape is not static. The top three companies hold roughly 55 percent of the market, with the top five reaching approximately 62 percent. This level of concentration points to entrenched relationships, technical expertise, and distribution networks that create meaningful barriers to entry. At the same time, the remaining share distribution leaves room for specialized manufacturers, regional specialists, and technology-focused entrants to compete on performance, customization, or cost structure rather than volume alone.
Critical Challenges and Inflection Points
Three interconnected challenges are reshaping how companies approach product strategy, capacity planning, and market entry.
PW Consulting Automotive & Machinery Research Center
- Regulatory and emissions pressure is redefining performance expectations. The maritime industry is navigating a more complex compliance environment, where operational efficiency is increasingly tied to emissions accounting, fuel choice, and lifecycle performance. Propellers are no longer evaluated solely on thrust delivery or cavitation resistance; they are now part of a broader efficiency equation that includes hull form, engine mapping, and fuel characteristics. This shift raises the bar for product validation, testing, and downstream integration, particularly for manufacturers serving commercial and naval customers with strict performance and compliance requirements.
- Input costs and order timing are creating planning complexity. Vessel construction costs and material pricing have introduced greater unpredictability into procurement cycles. New ship price indices have shown notable year-on-year increases, influencing vessel economics and, by extension, the timing and scale of propeller orders. When capital expenditure cycles stretch or accelerate unexpectedly, manufacturers must balance capacity utilization against inventory risk. This environment rewards companies that can adjust production lead times, communicate clearly with shipbuilders, and offer flexible specification options without compromising quality.
- Supply chain resilience and trade policy are altering sourcing strategies. Tariff actions and trade-related notices have brought renewed attention to dependency on specific sourcing corridors, especially for components and finished goods tied to maritime applications. For propeller manufacturers and distributors, this means that geographic concentration in supply chains is now a strategic risk factor rather than purely a cost consideration. Companies are reassessing where and how they source raw materials, finished components, and sub-assemblies, with resilience and lead-time predictability becoming core competitive attributes.
Key Drivers Reshaping the Market
Technology Innovation as a Competitive Differentiator
Propeller design is moving beyond incremental geometry improvements toward more integrated performance engineering. Advancements in machining precision, alloy performance, and computational design methods are enabling manufacturers to deliver propellers with better efficiency, reduced noise, and more predictable behavior across a wider range of operating conditions. In practice, this means that a propeller is increasingly evaluated as part of a propulsion system rather than a standalone mechanical component.
This shift is visible in recent product and production activity. One notable example is the rollout of multi-blade configurations designed for larger vessels, where performance and efficiency gains are pursued through blade count, pitch geometry, and material selection. Alongside product innovation, manufacturing method innovation is becoming just as important. Faster production pathways are being introduced to reduce lead times and improve scalability. The combination of advanced design and accelerated fabrication is changing the commercial calculus for both manufacturers and buyers, especially when delivery timing can influence vessel commissioning schedules and operational availability.
For companies operating in this space, the strategic implication is clear: design capability alone is no longer enough. The ability to translate engineering improvements into repeatable production, consistent quality, and cost-effective scaling is becoming the real differentiator. Manufacturers that can pair proprietary blade or hub designs with robust production processes are better positioned to capture value across both premium and volume-oriented segments.
Regulatory and Standards Evolution Affecting Design and Specification
Regulations and standards are shaping not only what ships must achieve, but how marine equipment is specified, validated, and documented. Standards development is becoming more granular, extending into component-level design and manufacturing details. Recent guidance on fixed-pitch propeller hub caps with fins, for example, signals a broader trend toward formalizing specifications that improve interchangeability, testing consistency, and design reliability.
At the same time, emissions-related frameworks are adding new layers to operational performance expectations. Guidelines addressing lifecycle greenhouse gas intensity and fuel-related emissions implications are reinforcing the importance of overall propulsion efficiency, including the role of propellers in reducing energy waste and improving vessel performance. For commercial operators, this can translate into a stronger preference for products that support lower fuel consumption and more predictable performance across operating profiles. For manufacturers, it means that technical marketing, specification support, and validation data are becoming increasingly important tools in the sales and engineering engagement process.
The practical consequence is that specification criteria are expanding. Buyers are looking for more than baseline thrust and durability; they want documentation, testing consistency, and assurance that a propeller will perform as part of an integrated efficiency strategy. Companies that invest early in compliance-aligned design, transparent performance data, and engineering support are more likely to win consideration in demanding commercial and naval applications.
Demand-Side Change Across Vessel Segments
Demand is being shaped by a mix of fleet renewal, operational economics, and leisure market dynamics. In commercial shipping, vessel replacement and upgrade cycles continue to drive demand for propulsion components that support efficiency and durability. Shipowners and operators are increasingly focused on total cost of ownership rather than lowest initial price, which favors propeller solutions that deliver measurable performance over the vessel’s operating life.
In naval applications, modernization programs and fleet requirements sustain demand for reliable, mission-appropriate propulsion systems. These programs often emphasize durability, specialized configurations, and long-term support relationships, creating a different set of competitive priorities than the commercial market. Meanwhile, the recreational segment remains sensitive to consumer spending, marine leisure trends, and product appeal. In this segment, performance characteristics such as noise reduction, ease of integration, and visible efficiency gains can influence purchasing decisions more directly than in commercial contexts.
Across these segments, one common theme is the growing importance of application-specific engineering. A propeller that performs well in one operating environment may not be optimal in another, and buyers increasingly expect manufacturers to demonstrate that differentiation. This encourages companies to prioritize segment-focused product development, targeted promotions, and channel strategies that align with how each customer group evaluates risk, cost, and performance.
Supply Chain and Cost Structure Realignment
The supplier base is being reshaped by changing cost structures, material availability, and regional sourcing considerations. The impact of shipbuilding cost movements on downstream component demand is a reminder that propeller markets do not operate in isolation. When new vessel pricing rises, order patterns, contract timing, and budget allocations can shift in ways that affect manufacturers’ planning horizons. This environment favors suppliers that can offer stable lead times, transparent cost communication, and flexible fulfillment models.
Material selection is also becoming more strategically important. The balance between aluminum, stainless steel, and specialized alloys is influenced not only by performance requirements but also by availability, processing complexity, and total cost. Manufacturers with strong casting, machining, and inspection capabilities have an advantage when they can produce consistent results across material types while controlling cycle times. This is particularly relevant when buyers are trying to manage both performance and procurement risk simultaneously.
In addition, trade-related actions are prompting companies to think more carefully about geographic exposure. For some market participants, resilience is being achieved through diversified sourcing, regional production footprints, or closer integration with shipbuilding and distribution partners. The long-term effect is likely to be a more deliberate approach to supply chain design, where agility and predictability are treated as strategic assets alongside unit economics.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiated Playbooks
The competitive field includes a wide range of participants, from large manufacturers with broad commercial and defense exposure to highly specialized firms focused on niche applications or particular production methods. Several companies illustrate the different ways to compete:
- Broad commercial and military reach with disciplined portfolio focus. Some manufacturers have built their reputation on inboard and outboard propellers, rudders, and struts across recreational, commercial, and military vessels. Their advantage typically lies in broad application knowledge, established distribution, and the ability to serve multiple customer groups without losing technical credibility. Recent moves to divest non-core geographic operations suggest a willingness to concentrate resources where scale, support, and product alignment are strongest.
- High-technology, precision-machined propulsion solutions. Other companies compete through specialized design and CNC-machined propellers intended for high-speed and efficiency-focused applications. Their product range often extends into specialized vessel types, where performance and refinement matter as much as raw thrust. This positioning tends to attract buyers who value engineering differentiation and are willing to pay for tailored performance characteristics.
- Patented design and efficiency-led positioning. A different strategic path is visible among firms that emphasize proprietary blade designs, reduced noise, and efficiency claims supported by distinct manufacturing approaches. When those claims are reinforced by production partnerships or advanced fabrication methods, the result can be a compelling story for both commercial and recreational buyers looking for measurable gains.
- Regional specialists and custom engineering providers. There is also a strong constituency of manufacturers that compete through custom builds, repair and tuning services, precision casting, and application-specific solutions. These companies may not lead in global volume, but they can win on responsiveness, technical adaptation, and local support. In markets where vessel types, operating conditions, and customer preferences vary widely, that flexibility carries real commercial value.
Together, these profiles show that success does not depend on a single formula. Some players win through portfolio breadth and established relationships; others through specialized performance, proprietary design, or service depth. The common thread is clarity of positioning. Companies that try to compete everywhere often struggle to communicate why they are the right choice for a specific application or buyer profile.
Market Evolution: Consolidation, Specialization, and New Entry
The market is likely to continue evolving along several overlapping paths. Consolidation will remain relevant where scale, supply chain control, and global service networks create advantages. Strategic transactions that release management attention and capital from less-central operations can allow leading players to concentrate on core segments and higher-value product lines. At the same time, specialization is gaining importance because efficiency, noise, and application-fit are increasingly visible decision factors. That opens space for firms that can solve a specific problem very well, even if they do not compete across the entire market.
New entry and expansion are also being shaped by production innovation. When advanced fabrication methods reduce cycle times and improve repeatability, they lower one of the traditional barriers to scaling specialized products. That can enable faster commercialization of new designs and make it easier to serve demanding customers without sacrificing quality. The broader effect is a market in which differentiation is increasingly tied to how quickly and reliably a company can bring a proven design to market, not just whether it has a promising concept.
Industry events and association activity also play a role in shaping the competitive rhythm. Expos and technical gatherings provide venues for product introductions, supplier networking, and cross-industry signaling. They are not themselves competitive advantages, but they reflect a market where visibility, peer validation, and hands-on demonstration still matter. Companies that use these channels effectively often reinforce their positioning more quickly than those that rely on broad advertising alone.
Forward Trends and Commercial Implications (2026–2032)
Efficiency as the Central Commercial Currency
Over the next several years, efficiency is expected to remain the dominant value proposition in the propeller market. This does not mean every buyer will make the same choice, but it does mean that products and services will be evaluated against their contribution to fuel economy, operational smoothness, and overall propulsion performance. Manufacturers that can quantify performance benefits and align them with real operating conditions will have an advantage in both specification and repeat business.
Commercial opportunity here lies in moving from product selling to performance selling. That may involve better testing data, more detailed application guidance, and closer collaboration with vessel designers and operators. It also creates room for aftersales support, refurbishment, and condition-based service models that help customers extract more value from their propulsion systems over time.
Production Speed and Scalability as Strategic Assets
Speed of production is likely to become a more visible competitive factor, especially as manufacturers introduce advanced casting, machining, and process-control methods. Shorter lead times can reduce inventory pressure, improve responsiveness to custom orders, and help align propeller supply with vessel commissioning schedules. For buyers, this can translate into lower scheduling risk and greater flexibility in fleet planning.
The commercial implication is that manufacturers who can demonstrate reliable delivery without compromising quality will be favored in time-sensitive segments. This is particularly relevant where premium designs are being scaled for broader use. The ability to produce complex designs with repeatable quality and shorter timelines can widen the addressable market for high-performance solutions, creating new growth paths beyond niche applications.
Regulatory Alignment and Specification Support as Table Stakes
As standards and emissions-related expectations become more embedded in procurement decisions, regulatory alignment will increasingly function as a baseline requirement rather than a differentiator reserved for a few leaders. That does not mean every company must become a standards body, but it does mean that documentation, design traceability, and validation support will matter more in competitive evaluations.
For companies serving commercial and naval customers, this trend raises the importance of engineering-led engagement. Buyers are more likely to value suppliers who can help them interpret requirements, justify specifications, and ensure that the selected propeller fits within a broader compliance and efficiency strategy. The opportunity is to build trust through technical credibility and consistent support, not just price competitiveness.
Risks and Uncertainties to Monitor
Even with a clear growth trajectory, there are meaningful uncertainties. Material cost volatility can affect margin planning and order timing. Trade policy shifts may alter sourcing advantages or increase friction in certain supply chains. Macroeconomic conditions can influence leisure demand and commercial capital spending in ways that are difficult to predict far in advance. In addition, standards and compliance expectations can evolve faster than product cycles, creating adaptation pressure for manufacturers with long lead-time development pipelines.
Companies should therefore treat flexibility as a core strategic requirement. That includes the ability to adjust product mix, production allocation, and sourcing strategies without losing quality or service reliability. It also means monitoring regulatory and cost signals closely enough to act before disruptions become urgent.
Airplane Propellers Market
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Clarify where your advantage is real and repeatable. Whether it is design uniqueness, production speed, material expertise, or application-specific service, make sure the market understands the problem you solve best and why your solution is defensible.
- Invest in the bridge between engineering and production. Advanced designs only create value when they can be manufactured consistently and at scale. Prioritize process control, lead-time reduction, and quality repeatability as part of the product strategy, not as a separate operations topic.
- Build specification support into the commercial model. As buyers evaluate efficiency, compliance, and integration more closely, strong technical documentation and application guidance can shorten sales cycles and improve win rates in demanding segments.
For Investors and Strategic Allocators
- Look for companies that combine differentiated technology with credible production pathways. Concepts are common; scalable execution is not. Businesses that can show both are better positioned to convert innovation into durable revenue.
- Assess exposure to segments with stronger spending resilience. Commercial efficiency demand, naval programs, and selective recreational applications may respond differently to economic cycles, so segment mix matters when evaluating growth durability.
- Monitor consolidation signals and supply chain restructuring. Strategic divestitures, regional sourcing shifts, and production partnerships can reveal where value is concentrating and which capabilities are becoming more valuable over time.
For Procurement and Fleet Decision Makers
- Evaluate propellers as part of total propulsion performance, not as isolated components. The best choice often depends on vessel type, operating profile, material requirements, and lifecycle cost, so supplier engagement should go beyond specification sheets.
- Prioritize suppliers with consistent delivery, transparent quality processes, and the ability to support custom requirements. In environments where commissioning schedules and operational continuity matter, reliability can be as valuable as marginal performance gains.
- Ask for evidence tied to your operating context. Performance claims should be aligned with the conditions your vessels actually face, including speed ranges, load patterns, and maintenance realities.
Closing Perspective
The marine propeller market is expanding with discipline rather than speculation. Demand is supported by fleet renewal, efficiency expectations, naval requirements, and evolving leisure activity, while growth is being shaped by technology, standards, cost dynamics, and supply chain strategy. In this environment, the most successful players are likely to be those that combine engineering credibility with production discipline, segment clarity, and responsive customer support.
For organizations seeking a deeper view of segmentation detail, regional dynamics, competitive benchmarking, and scenario-based planning data, a more comprehensive research reference can provide the granularity needed for investment, product, and procurement decisions. A full market study offers the additional breakdown required to translate these strategic directions into operational action with greater confidence.
For detailed analysis of this topic, please visit the official page: Marine Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Motor Spindles Market 2026: Why 5.3% CAGR Reshapes Asia Pacific Growth
By pmarketresearch, 2026-09-21
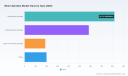
Strategic Trends and Commercial Opportunities in the Motor Spindles Market (2025–2032)
The motor spindles market has matured into a critical enabler of advanced manufacturing, with total market revenue reaching approximately 1,790 million USD in 2025 and projected to expand at a compound annual growth rate of 5.3 percent through 2032. The trajectory reflects more than steady growth; it signals a structural shift in how precision machining, high-speed automation, and digitalized production systems are being deployed across industrial sectors. For executives and investors, the market presents a compelling intersection of incremental volume expansion and qualitative transformation, where competitive advantage increasingly depends on technological differentiation, regulatory compliance, and supply chain agility rather than scale alone.
Understanding the strategic direction of this segment requires looking beyond headline revenue figures. The composition of demand, the evolution of manufacturing locations, and the pace of innovation are reshaping where value is created and how incumbents defend or expand their positions. This analysis examines the market fundamentals, the forces driving change, the competitive architecture, and the forward-looking opportunities that strategic decision-makers should factor into planning cycles.
Market Landscape and Core Challenges
The baseline market dynamics point to a segment that has recovered strongly from earlier disruptions and is now operating in a phase of sustained expansion. Revenue has grown consistently from roughly 1,424 million USD in 2020 to an estimated 1,790 million USD in 2025, with the forecast period projecting steady climbs toward approximately 2,552 million USD by 2032. This trajectory reflects broad-based demand rather than reliance on a single sector, with multiple application domains contributing to the overall volume.
Despite the favorable growth backdrop, the market faces several structural inflection points that will determine which participants capture disproportionate value in the coming years.
-
Precision and performance thresholds are rising faster than commoditization pressures. Buyers across machining, electronics, and automation applications increasingly demand spindles that deliver lower vibration, tighter thermal stability, and higher rotational consistency. Meeting these expectations requires advanced bearing architectures, refined cooling methods, and tighter manufacturing tolerances, which elevates the technical barrier to entry and compresses margins for undifferentiated offerings.
-
Regulatory and environmental compliance is reshaping design and sourcing decisions. Stricter directives on energy efficiency, noise and vibration control, and material compliance are pushing manufacturers to adopt sustainable cooling systems, optimize motor efficiency, and align with certification frameworks for export markets. These requirements are not merely administrative; they influence product architecture, supplier selection, and total cost of ownership calculations.
-
Supply chain localization and component availability remain sensitive points. As end-users prioritize resilience and shorter lead times, manufacturers must balance the cost advantages of globalized sourcing with the operational benefits of regionalized production and component stocking. Volatility in precision components and bearings can disrupt delivery schedules and pressure pricing discipline, especially for high-performance spindle systems where lead times directly affect machine uptime.
Taken together, these challenges point to a market where technical credibility, compliance readiness, and supply chain reliability are becoming as important as unit pricing. Participants that treat these factors as strategic differentiators are better positioned to defend share and command premium positioning.
PW Consulting Automotive & Machinery Research Center
Key Drivers of Market Change
The growth path of the motor spindles market is not uniform across drivers; it is being shaped by a combination of technological, regulatory, demand-side, and supply chain forces that reinforce one another.
Technological Innovation and Performance Breakthroughs
Innovation in spindle architecture continues to expand the envelope of what is possible in high-speed machining and precision material removal. Developments in air bearing and liquid journal designs, as well as improvements in built-in motor integration, are enabling lower runout, better thermal management, and reduced vibration in demanding applications. The introduction of ultra-compact angle spindles and refined series for micro-grinding, milling, and engraving illustrates how manufacturers are pushing size and precision boundaries simultaneously. These advances matter because they allow machine builders to increase feed rates, improve surface quality, and reduce tool wear without enlarging machine footprints, which is particularly valuable in space-constrained production environments.
Policy and Regulatory Environment
Regulatory pressure is becoming a meaningful design constraint and, in some cases, a catalyst for innovation. European Union environmental regulations are encouraging adoption of sustainable cooling systems in motor spindles, while tightening ISO standards for vibration and noise control are raising the baseline performance expectations for precision spindle applications. At the same time, increased emphasis on CE marking and RoHS compliance is shaping export-market readiness, and new EU directives on energy efficiency are pushing industrial automation users toward optimized spindle motors that reduce power consumption without sacrificing throughput. These requirements are gradually becoming table stakes for suppliers targeting regulated markets, and they reward manufacturers that can demonstrate validated compliance and efficiency gains in a credible, documented manner.
Demand-Side Shifts in End Markets
Demand patterns are being reshaped by the expansion of electronics fabrication, precision machinery production, and high-value component manufacturing in automotive and aerospace contexts. The continued scaling of printed circuit board production and consumer electronics assembly is driving need for spindles that can handle fine-detail machining and consistent high-speed operation. At the same time, machinery manufacturers and automation integrators are seeking spindle solutions that integrate more smoothly into digital workflows, support quick-change tool systems, and provide predictable performance over extended operating cycles. The practical implication is that demand is increasingly fragmented by application requirements, and the most attractive commercial opportunities lie in solutions tailored to specific performance profiles rather than generic high-speed units.
Supply Chain and Cost Structure Evolution
Cost dynamics are being influenced by a combination of energy efficiency expectations, material and component pricing, and the strategic trade-offs between centralized production and regional responsiveness. Suppliers with mature manufacturing footprints and long production histories are leveraging scale and process maturity to maintain competitiveness, while others are pursuing product line specialization to differentiate on performance, tool-change convenience, or application fit. In parallel, the push for energy-efficient industrial automation is encouraging customers to evaluate total operating cost rather than upfront price alone, which favors solutions that deliver better efficiency, lower maintenance burden, and longer service intervals. This shift in evaluation criteria is gradually altering negotiation dynamics and creating room for value-based positioning.
Competitive Landscape and Leading Strategies
The market is characterized by a concentration level that remains moderate, with the largest players holding a meaningful but not dominant share of total revenue. This structure creates room for differentiated specialists to compete effectively while rewarding incumbents that can blend technical depth with service reliability and regional reach.
Several companies illustrate the strategic diversity shaping the competitive field.
-
Nakanishi Inc. has built a strong identity around high-precision motor spindles for micro-grinding, milling, and engraving, with product families that emphasize refined control and updated catalog breadth. The recent introduction of what the company describes as the world’s smallest angle spindle signals a continued push into ultra-compact, high-precision niches where size and accuracy are both commercially valuable.
-
GMN Paul Müller Industrie GmbH & Co. positions itself around high-quality spindle systems for machine tools, grinding, and precision applications, with an emphasis on digital twin integration and rapid service response. This combination of advanced simulation capability and service availability supports customers who prioritize uptime and predictive maintenance in production-critical environments.
-
HSD Mechatronics S.p.A. focuses on quick-change air and liquid-cooled electrospindles for metal, wood, plastic, and aluminum machining. Its presence at major industry events with comprehensive machining solution showcases reflects a strategy centered on application breadth and system-level compatibility rather than narrow product specialization.
-
WEISS Spindle Technology GmbH develops motor spindles for high-performance cutting across milling, turning, grinding, and robot applications, with a strong emphasis on optimized cooling and precision. Its multi-application orientation suggests a strategy aimed at serving customers who need consistent performance across varied machining contexts.
-
MicroLab Precision Technology Co., Ltd. produces built-in motor spindles, machining center spindles, and rotary spindle heads with low vibration and high precision for high-speed machining. This profile highlights a focus on integrated spindle solutions that support precision CNC workflows and reduce integration complexity for machine builders.
-
Jiangsu HQD Spindle Motor Co., Ltd. manufactures electric spindle series for engraving, milling, woodworking, and automatic tool change applications, and maintains active participation in trade shows to showcase automatic tool change spindle solutions alongside broader electric spindle lines. This suggests a commercial emphasis on versatility, application coverage, and visible market engagement.
-
Changzhou Sulong Precision Motor Co., Ltd. supplies high-speed electric spindles and spindle parts for precision CNC and engraving use, indicating a positioning centered on component and spindle availability for precision-oriented machining customers.
-
WHD Spindle Motor Co., Ltd. specializes in automatic tool change, air-cooled, and water-cooled high-speed spindle motors for CNC machine tools with a long production history, reflecting a strategy built on product range breadth and manufacturing continuity.
Recent market activity reinforces the strategic themes behind these profiles. The introduction of compact angle spindle technology, the showcase of electric spindle lines at major exhibitions, and the launch of heavy-duty spindle motors for demanding machine tool applications all point to a competitive environment where product refresh cycles are active and application-specific differentiation is increasingly important. Participation in trade shows across regional markets also indicates that suppliers are investing in visibility and customer engagement as part of their growth strategy, particularly in segments where specification decisions are influenced by direct product comparison and live demonstrations.
The competitive evolution appears to be moving along two parallel tracks. On one hand, established players are deepening their advantage through precision engineering, cooling and control optimization, and service-oriented models that reduce customer downtime. On the other hand, specialized entrants and regional suppliers are carving out positions by focusing on particular application sets, tool-change convenience, or cost-efficient production for price-sensitive but volume-important segments. Consolidation remains possible where scale, certification, and service networks create genuine barriers, but fragmentation is likely to persist in niche performance categories where tailored design and rapid customization matter more than broad portfolio size. New entrants will need to demonstrate credible technical capability and compliance readiness to gain traction in regulated or high-precision channels, while established suppliers will need to continue refreshing portfolios to prevent commoditization in more standardized segments.
Machine Tool Spindles Market
Forward-Looking Trends for the Next 3–5 Years
Looking ahead, several trends are likely to shape commercial outcomes and determine which opportunities scale most effectively.
Performance differentiation will increasingly hinge on thermal, vibration, and efficiency control
As machining requirements become more exacting and automation environments demand predictable behavior over longer cycles, spindles that deliver superior thermal stability, lower vibration, and better energy efficiency will command stronger positioning. This trend creates opportunities for suppliers that can validate performance claims with measurable metrics and integrate spindle behavior into broader machine optimization strategies. It also raises the importance of testing, documentation, and application-specific tuning as commercial enablers.
Application-tailored portfolios will outperform generic high-speed offerings
Demand is becoming more segmented by end-use requirements, and buyers are increasingly selecting spindle solutions based on compatibility with specific materials, tool-change systems, and production workflows. Suppliers that organize product lines around application contexts, and that provide clear guidance on performance trade-offs, will be better positioned to capture premium demand. This shift favors companies that combine engineering depth with commercial clarity, and it reduces the advantage of broad but undifferentiated portfolios.
Regulatory and sustainability alignment will become a market-access requirement
As environmental and efficiency directives continue to influence procurement decisions, compliance readiness and demonstrable sustainability improvements will matter more in bids for regulated markets and export-oriented programs. This trend will likely reward suppliers that proactively design for efficiency, adopt sustainable cooling approaches, and maintain documentation that simplifies customer certification processes. At the same time, it introduces a risk for participants that treat compliance as a retroactive adjustment rather than a design principle, since late adjustments can delay launches and increase cost.
These trends are not independent. Efficiency and thermal performance improvements support sustainability objectives, application-specific tuning supports customer productivity goals, and compliance readiness supports market access. Together, they point to a market where integrated value propositions will increasingly outperform narrow price competition.
Potential risks and uncertainties should also be factored into planning. Shifts in regional demand intensity, changes in component availability, and the pace of regulatory implementation can affect both cost structures and timing. In addition, if performance requirements converge across segments faster than expected, differentiation windows may narrow, intensifying competition in previously protected niches. Participants should therefore monitor not only product cycles but also the regulatory calendar, customer procurement criteria, and regional industrial investment patterns.
Strategic Implications for Decision-Makers
The motor spindles market offers genuine growth, but the distribution of value will depend on how well companies align product strategy, compliance posture, and customer engagement with the market’s evolving performance expectations.
For manufacturers and spindle suppliers
-
Prioritize design and documentation that make efficiency, vibration control, and cooling performance verifiable. In a market where buyers are increasingly evaluating total operating cost and regulatory readiness, credible validation can support premium positioning and shorten procurement cycles.
-
Organize product communication around application outcomes rather than specifications alone. Clear mapping between spindle configurations and machining contexts helps customers choose faster and reduces the risk of mismatch-driven returns or underperformance.
Automatic Tool Change Spindle Market -
Strengthen service and availability propositions where uptime is commercially critical. Quick response, predictable lead times, and compatible tool-change options can be decisive in competitive bids, especially for production environments where downtime carries high cost.
For investors and strategic partners
-
Favor participants with clear technological differentiation and evidence of repeatable product refreshes, since the market is rewarding sustained innovation over static portfolios. Look for companies that can connect product performance to measurable customer benefits in precision, efficiency, or service reliability.
-
Assess exposure to regulated and export-oriented demand, as compliance readiness and certification discipline are becoming meaningful determinants of market access. Businesses that have integrated these requirements into product development are less exposed to launch delays and redesign costs.
-
Watch for consolidation opportunities in segments where scale, service networks, and certification create durable barriers, while recognizing that specialized niches may remain attractive for focused operators with strong application expertise.
For procurement and engineering decision-makers
-
Evaluate spindle selections against total cost of ownership, including energy consumption, thermal stability, maintenance intervals, and compatibility with existing tool-change and automation systems. Upfront price is only one component of value in high-utilization environments.
-
Clarify application requirements early and request performance data that reflect real operating conditions rather than generic benchmarks. This reduces the risk of over-specifying where unnecessary or under-specifying where precision matters.
-
Consider supplier capability in documentation, compliance support, and after-sales responsiveness as part of the sourcing decision, since these factors increasingly influence long-term operating reliability and audit readiness.
Decisions in this market are most effective when grounded in current, granular insight into segment performance, regional demand intensity, and product-level differentiation. The motor spindles market is large enough to support multiple successful strategies, but the strategies that work are becoming more specific, more application-aware, and more dependent on verifiable performance and compliance. For teams evaluating market entry, portfolio planning, or investment allocation, more detailed segmentation data and customized scenario analysis can help translate these directional trends into precise commercial choices.
For detailed analysis of this topic, please visit the official page: Motor Spindles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dust Sensors Market: Why 5.4% CAGR Growth Is Reshaping Strategic Competition
By pmarketresearch, 2026-09-21
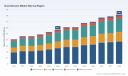
Navigating the Dust Sensors Market: Strategic Trends and Commercial Opportunities in a Tightening Air Quality Landscape
The dust sensors market stands at the intersection of environmental regulation, industrial automation, and consumer health awareness. Valuation reached an estimated $0.57 billion in 2025, expanding from $0.42 billion in 2020 at a compound annual growth rate of 5.4 percent. The trajectory points toward $0.82 billion by 2032, with the most pronounced acceleration concentrated in the 2026–2032 forecast window. This expansion is not merely a function of unit volume growth; it reflects a structural recalibration of how particulate matter is measured, monitored, and managed across commercial, industrial, and domestic environments. For executives and investors, the opportunity lies in recognizing where measurement precision, regulatory pressure, and cost discipline converge to create defensible positioning.
Beneath the headline growth figure, the market reveals a clear maturity curve. Historical expansion from 2020 through 2025 was supported by early-stage adoption in air quality monitoring and incremental industrial compliance upgrades. The next phase demands a shift from broad deployment to targeted, high-value applications where sensor data directly drives operational decisions or regulatory reporting. Market concentration remains moderate, with the top three participants holding approximately 28.5 percent of revenue and the top five reaching 38.2 percent. This fragmentation signals room for specialized players to capture niche leadership, but it also underscores the importance of differentiation in a space where commoditization pressure is building at the lower end of the performance spectrum.
Several structural challenges now shape the market's near-term evolution. The first is the tension between measurement fidelity and cost at scale. As deployment moves into dense urban networks and distributed industrial sites, the operational burden of installation, calibration, and maintenance becomes a meaningful constraint on total cost of ownership. The second challenge is regulatory fragmentation. Differing enforcement timelines, reporting formats, and particulate thresholds across jurisdictions create compliance complexity for manufacturers and end-users alike, requiring sensor solutions that can adapt to varying validation standards without sacrificing accuracy. The third is the performance ceiling of lower-cost optical technologies in harsh or high-particulate environments. Industrial dust, powder handling, and bulk solids operations expose sensors to contamination, humidity, and particle size distributions that can degrade readings if the underlying optical architecture and self-cleaning mechanisms are not engineered for those conditions. These pressures are not bottlenecks so much as filters: they determine which offerings translate into durable market share.
Key Drivers Reshaping Demand and Value Capture
Technology innovation continues to redefine what dust sensors can deliver in real time. Advances in optical detection architectures, laser-based particle sizing, and integrated signal processing are enabling tighter correlation between sensor output and reference-grade measurements. For environmental and indoor air quality applications, this translates into actionable data that can trigger filtration adjustments, ventilation control, or compliance documentation without relying on sporadic manual sampling. In industrial contexts, the shift toward continuous emissions and leak detection monitoring is reducing dependence on periodic checks, allowing operators to identify filter degradation or fugitive dust events sooner. The commercial value of these capabilities lies in their ability to convert raw particulate readings into operational signals that reduce downtime, protect equipment, and support audit-ready reporting.
Policy and regulatory pressure is reinforcing demand from the top down. In the European Union, the revised Ambient Air Quality Directive sets stricter limit values for PM2.5, reducing the annual limit value by more than half to align with WHO guidelines and streamlining provisions for twelve air pollutants. This creates a direct compliance pull for more granular, auditable monitoring across industrial sites, urban environments, and managed indoor spaces. In parallel, U.S. EPA monitoring priorities for 2025–2026 emphasize the deployment of next-generation low-cost sensors for PM2.5 in urban networks, reflecting a broader shift toward distributed measurement architectures that supplement reference stations. These regulatory signals expand the addressable demand base, but they also raise the bar for sensor validation, data credibility, and documentation traceability.
Demand-side behavior is changing on both the enterprise and consumer fronts. Organizations are increasingly treating air quality as an operational and reputational variable rather than a compliance checkbox. In healthcare, cleanroom-adjacent environments, and facilities with vulnerable occupants, particulate monitoring is being integrated into broader environmental management and ventilation strategies. In automotive and aerospace contexts, cabin air quality and sensitive component protection are driving interest in compact, reliable monitoring modules. On the consumer side, family-use applications continue to expand, supported by greater awareness of indoor air quality and the availability of smaller, lower-power devices. The strategic implication is that demand is becoming more application-specific, which rewards providers that can frame sensor performance in terms of the end-use outcome rather than raw specifications alone.
Supply chain and cost dynamics add another layer of complexity. Laser-based dust sensors depend on high-precision optical components and laser sources that require advanced polymer injection molding processes, tying performance to specialized manufacturing capabilities and materials availability. At the same time, labor costs associated with installing and calibrating low-cost sensors in dense urban networks remain a key operational constraint, particularly where large-scale deployments are contemplated. These factors push the market toward solutions that balance upfront hardware cost with ease of deployment, modularity, and maintenance efficiency. For suppliers, the winners are increasingly those who can reduce the hidden costs of integration and ongoing calibration rather than compete solely on unit price.
Competitive Landscape and the Logic of Differentiation
The competitive field is shaped by a mix of specialist sensor manufacturers and broader measurement-player portfolios, each pursuing a distinct value proposition. ENVEA, based in France, has focused its offering on real-time industrial emissions and filter leak detection through its ProSens and Dusty dust monitors. Its positioning reflects an emphasis on continuous industrial monitoring where measurement continuity and operational reliability matter more than consumer-facing form factors. In April 2025, the company launched a next-generation Optical Aerosol Spectrometer for real-time particulate matter monitoring, a move that signals an intent to extend high-resolution measurement capabilities into broader environmental and compliance contexts. The strategic takeaway is that advanced optical architectures can be used to bridge industrial emissions monitoring and ambient air quality requirements, provided the instrumentation is validated for the intended deployment environment.
Air Quality Sensor Market
Chinese manufacturers illustrate a different competitive logic, centered on laser and infrared dust sensors for air quality monitoring and industrial leak detection. Chengdu Pulse Optics-tech and Zhengzhou Winsen Electronics both emphasize laser and infrared-based sensing for air quality applications, with product families such as the ZH10 laser dust sensor and supporting infrared variants. Their trajectory suggests scale-oriented development aimed at cost-sensitive monitoring segments, where integration flexibility and price competitiveness can accelerate adoption. Cubic Sensor and Instrument takes a more application-specific approach, focusing on industrial dust sensors for powder and bulk solids leak detection. This specialization matters because it aligns sensor design with the particle types, loading conditions, and contamination risks encountered in material handling environments, rather than treating all particulate monitoring as a single category. The broader implication is that regional manufacturing depth and application-specific calibration can create defensible positions even in a market with many participants.
Western suppliers in automotive and HVAC-adjacent segments are pursuing integration-led differentiation. Amphenol Advanced Sensors, through its Telaire SMART Dust Sensor and DSF series, targets automotive and air quality applications, indicating a focus on embedding particulate sensing into vehicle and built-environment platforms where size, reliability, and system compatibility are critical. Sensirion, based in Switzerland, offers the SPS30 PM2.5 sensor for HVAC and air quality applications, an approach that connects particulate measurement to air circulation and filtration control in building systems. Shinyei Corporation, from Japan, continues to develop optical dust sensors such as the PPD series for air quality monitoring, reinforcing a long-standing emphasis on compact optical detection suitable for distributed monitoring. Collectively, these profiles show that competitive advantage is increasingly defined by where the sensor is integrated and what control or reporting function it enables, rather than by detection method alone.
The market structure is evolving along three trajectories. First, consolidation pressure is building at the lower-performance end, where generic optical sensors face margin compression and replacement risk from better-integrated alternatives. Second, specialization is intensifying in higher-value industrial and compliance-grade segments, where validation, durability, and data usability justifypremium positioning. Third, new entrants are likely to emerge at the intersection of sensor hardware and data services, particularly where low-cost networks can be combined with calibration support, remote diagnostics, and software layers that make readings operationally useful. For buyers and partners, this means supplier selection should weigh not only detection performance but also the ecosystem around calibration, maintenance, integration support, and data-handling practices.
Forward Outlook: Trends That Will Shape the Next Three to Five Years
The first major trend is the convergence of distributed sensing with regulatory-grade data expectations. As urban and industrial monitoring networks expand, the market will increasingly reward sensor platforms that can operate at scale while maintaining enough measurement consistency to support reporting, trend analysis, and operational decision-making. The commercial opportunity here lies in enabling large-scale deployments without surrendering data credibility, which requires thoughtful calibration strategies, robust optical designs, and software that can contextualize readings across sites and time periods. Companies that can reduce the hidden burden of installation and calibration will be better positioned to serve dense network scenarios.
A second trend is the migration of dust sensing from standalone measurement toward embedded control and predictive maintenance. In HVAC, industrial filtration, and material handling environments, particulate data is becoming part of a feedback loop that adjusts airflow, flags filter status, or alerts operators to leak conditions before they escalate. This creates a shift in value capture from device sales alone to solutions that contribute to energy efficiency, equipment protection, and compliance readiness. The opportunity is strongest for suppliers that can articulate how sensor data integrates with existing control systems and what operational outcomes it supports, rather than positioning the sensor purely as an information source.
PW Consulting Automotive & Machinery Research Center
A third trend is the widening performance gap between generic low-cost sensors and application-hardened solutions. As deployment scales, users are becoming more discerning about where lower-cost units are appropriate and where contamination, humidity, particle size range, or compliance documentation make ruggedized designs necessary. This does not mean the low-cost segment will disappear; it means its role will become more clearly defined. The strategic risk is for suppliers that overgeneralize their offering and get pulled into price competition in applications where performance and maintainability matter more. The corresponding opportunity is to segment the market deliberately and align product architecture, validation claims, and service support with the requirements of each segment.
Underpinning these trends are uncertainties that decision-makers should monitor. Regulatory timelines and enforcement intensity can vary by region, affecting demand pacing and validation requirements. Supply chain dependencies for precision optics and laser sources may influence cost and availability, particularly if manufacturing bottlenecks emerge around advanced polymer injection molding or specialized components. Labor and installation constraints may continue to shape the economics of large-scale urban networks, making modular, field-serviceable designs more valuable. Finally, data credibility remains a persistent question in distributed sensing, especially where readings inform compliance or public-facing reporting. Suppliers and end-users alike will need to manage expectations around uncertainty, calibration intervals, and the role of reference correlation in networked deployments.
Actionable Guidance for Manufacturers, Investors, and Procurement Leaders
For manufacturers, the priority is to define product strategy around use-case outcomes rather than detection method alone. That means mapping sensor architectures to the environments they will face, clarifying where calibration support, self-cleaning, or modular replacement add real value, and positioning data outputs in terms of operational or compliance utility. Companies that can demonstrate repeatability across installation conditions, simplify integration with ventilation or filtration control, and provide clear documentation for audit contexts will be better equipped to hold pricing power as the market matures. Equally important is deciding where not to compete: undifferentiated low-cost segments may generate volume, but margins and longevity will depend on whether the offering is tied to a defensible application fit or service model.
For investors, the most instructive question is where value will concentrate as the market evolves from broad adoption to more demanding applications. Segments tied to industrial leak detection, continuous emissions monitoring, HVAC integration, and compliance-aligned urban networks are likely to support more resilient economics than generic consumer-facing devices, provided the supplier can meet validation and maintainability expectations. Investment thesis-building should therefore emphasize differentiation in optical design, calibration and service strategy, integration readiness, and the ability to support data credibility at scale. It should also account for regional regulatory momentum, since policy-driven demand can create near-term pull but may shift in emphasis as standards harmonize or enforcement patterns change.
For procurement and operations leaders, sensor selection should be evaluated as a total-cost and risk decision, not just a hardware comparison. The relevant considerations include calibration and maintenance burden, expected service life under local particulate and humidity conditions, compatibility with existing control or reporting infrastructure, and the supplier's ability to support validation or documentation requirements where compliance is involved. In dense urban or multi-site deployments, installation labor and ongoing calibration constraints should be priced into the decision, because they can dominate lifecycle cost. Procurement teams also benefit from aligning sensor specifications with the actual decisions the data will inform: if readings drive filter changes, ventilation adjustments, or compliance reporting, then measurement stability and traceability become more important than marginal sensitivity gains in benign conditions.
As the market moves from early adoption to more disciplined, application-specific deployment, the ability to separate durable opportunity from transient hype will depend on detailed segmentation, validation expectations, and regional regulatory pacing. The broader market direction is clear, but the commercial winners will be those who can match sensor capabilities to the operational and compliance realities of each segment. For decision-makers seeking granular breakdowns of regional demand patterns, application-level sizing, company-level positioning, and scenario-based forecasts, a full market study provides the additional structure needed to translate these trends into a concrete investment, product, or procurement roadmap.
UV Sensors Market
For detailed analysis of this topic, please visit the official page: Dust Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laser Drilling Machine for Aerospace: Why 6.98% CAGR Reshapes the $344.8M Market
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Laser Drilling Machine for Aerospace Market
The aerospace manufacturing sector is undergoing a fundamental transformation in how precision components are produced, and laser drilling technology sits at the center of this shift. As the 2025 market reaches an estimated 215.0 Million, with growth tracked from 2020 through the current year, the sector has demonstrated consistent expansion across the historical period. Looking ahead to 2032, the trajectory points toward a 6.98% compound annual growth rate, positioning this technology as a critical enabler for next-generation aerospace production. For executives, investors, and strategic planners, understanding the underlying dynamics of this market requires more than surface-level sizing. It demands a clear view of the technological, regulatory, and competitive forces shaping where capital and capability will flow over the next several years.
Worldwide Laser Drilling Device Market
The expansion from 2020 to 2025 reflects a steady accumulation of adoption across engine component manufacturing, airframe assemblies, and specialized aerospace applications. By 2032, revenues are projected to reach 344.8 Million, signaling a market that has moved well beyond niche adoption and is becoming embedded in standard aerospace manufacturing workflows. This growth is not uniform across all categories. Energy-based machining technologies show clear differentiation, with fiber-based systems capturing the largest share of revenue, followed by solid-state laser approaches and carbon dioxide-based configurations. Similarly, the demand landscape shows commercial aviation driving the majority of activity, while military aviation and other specialized applications contribute meaningful but smaller volumes. Regionally, established aerospace hubs continue to anchor the largest revenue pools, while emerging industrial centers are gradually expanding their footprint.
Core Challenges and Inflection Points
Despite the positive growth trajectory, the market faces structural challenges that will determine which participants capture value and which struggle to compete. Three critical dynamics deserve attention.
First, certification and qualification remain formidable barriers. Laser drilling for aerospace components must align with stringent aviation quality standards and non-conventional machining certifications. Systems designed for turbine disc cooling holes, jet engine components, and high-temperature alloy processing require documented process control, traceable quality assurance, and often original equipment manufacturer approvals. These requirements create a high bar for entry and raise the cost of scaling new offerings, but they also protect incumbents who have invested in certified workflows and established relationships with engine and airframe manufacturers.
Second, the shift in laser technology modalities is reshaping buyer expectations. Fiber-based systems have gained prominence because they offer compact form factors, high beam quality, and strong compatibility with multi-axis CNC integration. Solid-state and carbon dioxide approaches still serve specific use cases, but the momentum is clearly tilted toward platforms that can deliver micro-hole precision with minimal heat-affected zones and predictable cycle times. Manufacturers that continue to rely on legacy process chains without adapting to fiber and hybrid architectures risk being outcompeted on throughput and repeatability.
Third, the demand environment is evolving as aerospace production scales and aircraft architectures become more complex. Cooling hole density, micro-hole accuracy, and surface integrity requirements are intensifying, especially for turbine blades, vanes, and high-performance structural parts. At the same time, the industry is looking for automation, monitoring, and software integration that can reduce variability across high-mix production runs. This places pressure on equipment suppliers and service providers to deliver not just hardware, but integrated process solutions that include control software, inspection feedback, and application engineering support.
Key Drivers Shaping Market Direction
The market is being pulled forward by a combination of technology advancement, regulatory frameworks, demand-side transformation, and cost structure evolution. Each driver reinforces the others, creating a coherent case for continued investment in laser drilling capabilities.
Worldwide Solar Laser Drilling Market
Technology Innovation and Breakthroughs
Precision and speed are becoming defining competitive dimensions. Advanced multi-axis systems now support positioning accuracy on the order of micrometers while enabling drilling rates that can reach hundreds of bores per second in optimized configurations. These capabilities are particularly relevant for effusion cooling holes in turbine discs and engine components, where geometry, diameter consistency, and surface quality directly affect performance and lifecycle cost. Fiber laser integration with 5-axis and 7-axis CNC architectures has expanded the feasible design space for drilling in complex contours and 3D aerospace alloys. In parallel, software and monitoring layers are improving process stability, allowing operators to manage trepanning, micro-hole patterns, and specialized flow or optical products with greater control and repeatability.
Policy and Regulatory Environment
Aviation quality standards and non-conventional machining certification requirements create both a barrier and a catalyst. Regulatory regimes and OEM quality expectations push manufacturers toward documented process control, validated machine performance, and certified service practices. This environment favors suppliers that can demonstrate compliance with recognized aerospace standards and provide the audit trail that engine and airframe producers require. At the same time, the standardization of laser drilling for critical cooling and precision hole applications reinforces its role as a preferred process in high-temperature alloy manufacturing, supporting long-term demand stability beyond cyclical production fluctuations.
Demand-Side Changes
Commercial aviation continues to be the dominant application driver, reflecting the scale of production, aftermarket demand, and the ongoing need for precision cooling and micro-hole features across engine and airframe components. Military aviation adds a distinct set of requirements, where performance margins, material behavior under extreme conditions, and component reliability place a premium on advanced drilling technology. Beyond these core segments, specialized applications in flow control, optical products, and calibrated micro-leak features are creating pockets of high-value demand. The broader trend is toward more demanding geometries and tighter tolerances, which increases the appeal of laser processes that can maintain precision across difficult-to-machine materials and composite structures.
Supply Chain and Cost Structure Evolution
The economics of laser drilling are shifting as equipment becomes more integrated, automation more accessible, and service models more flexible. Multi-axis platforms with fiber lasers can reduce rework and improve throughput by minimizing heat-affected zones and improving hole quality consistency. For high-mix production, the ability to switch between configurations, control processes through software, and integrate monitoring reduces the cost of changeovers and improves asset utilization. At the same time, certified service providers and system integrators are expanding their geographic reach, allowing manufacturers to access specialized drilling capability without always investing in full in-house capacity. This combination of capital efficiency and capability access is changing how aerospace manufacturers evaluate their sourcing and production strategies.
Competitive Landscape and Leading Strategies
The market features a mix of established machine builders, specialized service providers, and technology integrators, each pursuing a distinct route to value. The competitive field is not dominated by a single model, and concentration remains moderate, indicating that differentiation and application expertise still matter greatly. This environment rewards companies that can combine hardware performance with certification readiness, software-enabled process control, and strong OEM relationships.
Strategic Positioning Among Leading Participants
DMG MORI has built its positioning around high-end multi-axis laser machining with fiber laser integration for precision drilling of turbine blades, vanes, and aerospace components. Its 5-axis LASERTEC PowerDrill series emphasizes precision, process software, and shape-control technology, targeting high-value engine and IGT component manufacturing where accuracy and repeatability are central. The appeal lies in combining machine rigidity, laser performance, and application software into a single platform that can be qualified for demanding aerospace workflows.
Prima Power offers a different angle through multi-axis laser systems focused on high-precision micro-hole drilling with low heat-affected zones and CNC monitoring. Its LASERDYNE series is oriented toward aerospace components where micro-hole integrity and process control are critical. By emphasizing specialized processing and 3D laser drilling capabilities, Prima Power positions itself for customers who need tight control over hole quality in complex geometries, while also expanding into broader laser processing solutions that include cutting and hybrid workflows.
EBTEC Corporation has developed a strong identity around certified laser drilling services and systems for aerospace alloys and composites, supported by AS9100 and NADCAP credentials as well as OEM approvals. Its multi-axis machines, spanning Nd:YAG and fiber laser configurations across a broad power range, are designed for precision holes in demanding materials. This service-plus-equipment model gives the company a clear route to customers who value qualification readiness, OEM acceptance, and full-process support rather than hardware alone.
Corry Laser Technology focuses on high-degree-of-freedom moving beam systems for trepanning and micro-hole drilling in 3D aerospace alloys. Its emphasis on multiple industry certifications and approvals from major aerospace players signals a strategy centered on trust, qualification, and capability validation. By aligning its systems with recognized aerospace standards, the company creates a defensible position in an environment where certification is often as important as raw machining performance.
Lenox Laser and Accumet Engineering illustrate the service-oriented side of the market. Lenox Laser specializes in precision laser drilling services and systems for small-hole technology, with particular attention to calibrated micro-leaks and flow or optical products. Accumet Engineering provides precision laser drilling services for metals and ceramics, with broad regional coverage and secondary processing capability. These participants show that for many aerospace manufacturers, the decision is not only about buying equipment but also about accessing specialized process expertise, quality assurance, and capacity flexibility.
Market Evolution and Structural Trends
The competitive landscape is evolving along several axes. One is the gradual convergence of laser drilling with broader laser processing platforms, as seen in recent industry showcases where drilling capabilities are presented alongside cutting and automated modules. This convergence reduces the friction of integrating drilling into larger production cells and can improve overall facility efficiency. Another is the continued importance of certification and OEM acceptance as filters for serious competition. Participants that can demonstrate NADCAP-aligned processes and approvals from major engine and component manufacturers are better positioned to win demanding contracts and retain long-term relationships.
At the same time, the market is open enough that new entrants and specialist service providers can build niches around application expertise, material-specific process development, and regional service coverage. The moderate concentration in the market suggests that scale alone is not the only winning strategy. Differentiation through software, monitoring, process qualification, and customer support remains a viable path, especially for companies serving high-mix, high-precision production environments. Recent industry activity also indicates that the sector is actively converging around aerospace-focused demonstrations and discussions, signaling that both suppliers and end users are paying close attention to laser drilling as a strategic process rather than a peripheral capability.
Future Trends and Commercial Opportunities
Looking forward across the next three to five years, several trends are likely to shape where value is created and how participants should position themselves.
PW Consulting Automotive & Machinery Research Center
Integration of Drilling with Automated Laser Processing Cells
The direction of travel points toward more tightly integrated systems that combine drilling, cutting, and automation within unified machine concepts. This trend is already visible in recent product announcements that pair drilling modules with laser cutting workflows and smart automation. For manufacturers, the commercial opportunity lies in reducing handling, improving throughput, and standardizing process control across multiple operations. For equipment suppliers, the opportunity is to offer platforms that can serve multiple process steps without forcing customers to manage fragmented equipment portfolios. The risk is that integration raises technical complexity and can increase the importance of application engineering, service responsiveness, and customer training.
Continued Emphasis on Certification, Quality Documentation, and OEM Alignment
Aviation standards and OEM approvals will continue to act as both a constraint and a competitive moat. Systems and services that can demonstrate NADCAP-aligned machining practices and maintain the approvals required for engine and airframe components will be better positioned to access the most demanding segments. This creates a commercial opportunity for participants to invest in qualified process documentation, audit readiness, and customer-facing quality systems. It also implies that short-term pricing pressure is less important than long-term qualification credibility in high-value aerospace segments. The uncertainty is that certification requirements can evolve, and qualifying new materials or new hole geometries may require additional validation effort.
Growth in High-Precision Micro-Hole and Complex Geometry Demand
As turbine components, cooling structures, and specialized aerospace parts become more geometry-intensive, demand for precise micro-hole drilling and complex trepanning will likely remain strong. Fiber laser systems with multi-axis capability are well suited to this demand because they can address difficult materials and 3D contours while maintaining tight tolerances. The commercial opportunity here is for suppliers and service providers that can demonstrate repeatable performance on challenging alloys and composites, including low heat-affected zones and stable hole quality. The downside risk is that materials and cooling requirements can change as engine architectures evolve, which means process flexibility and continued application development will be essential.
Strategic Recommendations for Decision Makers
Different stakeholders should prioritize different actions based on their role in the value chain. The common theme is that competitive advantage will come from combining technical capability with qualification readiness, process integration, and responsive service models.
For manufacturers and production leaders, the priority is to assess where laser drilling can replace or enhance existing process chains in ways that improve quality, reduce rework, and support tighter tolerances. Before expanding capacity, it is worth evaluating whether integrating drilling with adjacent laser processes or automated modules can increase asset utilization and simplify workflow. Equally important is ensuring that selected systems or services can meet the certification and approval requirements of target applications, because those requirements often determine whether a solution is viable for production use in the first place.
For investors and technology acquirers, the most relevant signal is that the market is expanding steadily, but value capture will depend on differentiation rather than volume alone. Platforms that combine fiber laser performance with multi-axis flexibility, software-enabled process control, and strong aerospace certification readiness are better aligned with long-term demand. Service-oriented providers with OEM approvals and specialized application expertise also represent an attractive way to participate in demand without needing to compete purely on equipment commoditization. At the same time, investors should monitor integration trends and watch for consolidation among specialists, since those dynamics can reshape regional coverage and service availability.
For procurement and sourcing leaders, the focus should be on total process reliability rather than unit price alone. Laser drilling for aerospace parts often implicates quality, certification, and downstream performance, so supplier selection should weigh documented process control, traceability, approval status, and the ability to support new materials or new hole geometries. Engaging suppliers early in the qualification process can reduce later delays, particularly when component designs require micro-hole precision or complex contours. Where in-house capacity is limited, partnering with certified service providers can offer flexibility while preserving access to specialized process expertise.
For organizations navigating this market, the most practical next step is to obtain a detailed view of segment-level demand, regional dynamics, and company-specific capability maps before making major investment or sourcing decisions. The broader trends are clear, but the specifics of where demand is strongest, which certifications matter most for a given application, and how competing platforms differ on precision, integration, and service support can materially change the outcome of a strategic choice. More granular data and tailored assessments can help translate market direction into concrete capital, procurement, and partnership decisions.
The laser drilling market for aerospace is moving from steady expansion toward a more integrated, qualification-intensive, and application-driven phase. That shift creates opportunities for equipment suppliers, service providers, and manufacturers that can combine precision technology with certified processes and flexible delivery models. It also raises the stakes for participants that underestimate the importance of software, monitoring, automation, and OEM acceptance. In a market projected to grow to 344.8 Million by 2032, the winners are likely to be those who treat laser drilling not as an isolated machine purchase, but as a strategic process capability embedded in high-performance aerospace production.
For detailed analysis of this topic, please visit the official page: Laser Drilling Machine for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Water Pump Market: Why 5.3% CAGR and Asia Pacific Resonance Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Automotive Water Pump Market
The automotive water pump market has evolved from a commoditized mechanical component into a strategically critical subsystem within broader vehicle thermal management architectures. Valued at approximately $2.085 billion in 2025 and projected to reach nearly $3 billion by 2032, the segment is expanding at a compound annual growth rate of 5.3 percent over the 2026–2032 forecast horizon. This trajectory reflects more than steady replacement demand; it signals a structural shift driven by powertrain electrification, tighter emissions and thermal efficiency mandates, and the growing complexity of cooling circuits that now serve internal combustion engines, hybrid drivetrains, battery packs, and power electronics simultaneously. For executives and investors evaluating near-term industrial exposure, the water pump market offers a tractable lens into how legacy component suppliers are repositioning for electrified thermal management, how aftermarket channels are adapting to new testing and certification requirements, and where margin pools are migrating as product specifications become more application-specific.
Automotive Vacuum Pump Market
Market Structure and Core Operational Challenges
The market’s scale and growth profile mask a moderately concentrated competitive environment. The top three players collectively command roughly 38 percent of global revenue, while the top five account for just under half, leaving meaningful room for regional specialists, Tier 2 suppliers, and well-capitalized aftermarket brands to compete on coverage, service speed, and application-specific engineering. This fragmentation is particularly visible across powertrain types and vehicle classes, where mechanical circulation pumps still dominate volume but electric and vacuum-assisted variants are expanding their share in hybrid, EV-adjacent, and specialized commercial applications. The structural tension is that growth is not evenly distributed; it is concentrated in configurations that demand higher reliability, tighter integration with electronic control units, and more rigorous validation protocols.
Three challenges are currently shaping how manufacturers, distributors, and service networks operate in this space.
- Testing and quality assurance intensity is rising. Modern water pumps, particularly those built with premium alloy materials for high-temperature engine environments, now require 100 percent functional and leakage testing to satisfy OEM and aftermarket safety expectations. This standard elevates fixed costs and compresses the economics of low-mix, high-volume production unless offset by automation, process control, and yield optimization.
- Certification and installer competency requirements are tightening. Updated qualification pathways for personnel handling cooling system repairs and replacements are reshaping labor readiness in the service channel. As safety standards evolve, professional installers increasingly need refreshed certifications, which affects turnaround times, warranty exposure, and the practical adoption of new pump variants in the field.
- Thermal management complexity is fragmenting demand. Vehicles no longer rely on a single cooling loop with a single pump duty cycle. Hybrid and electric architectures require coolant flow control that responds to engine load, battery temperature, and power electronics needs, often with speed variation and ECU activation. This shifts purchasing behavior from generic replacement toward application-matched components and elevates the importance of diagnostic compatibility.
The commercial implication is straightforward: competitive advantage is increasingly defined by the ability to deliver validated performance at scale, support evolving service certifications, and align product portfolios with the thermal architectures that dominate new vehicle production and high-value replacement segments.
Key Demand Drivers Reshaping the Segment
Several interlocking forces are accelerating change in the automotive water pump market. None of these drivers operates in isolation; together, they are redefining both the technical specification of pumps and the economic structure of the supply base.
Technology Innovation and Thermal Integration
The most decisive technological shift is the migration from purely mechanical circulation toward electronically controlled and application-specific pumping solutions. In legacy internal combustion platforms, water pumps remain fundamental to engine cooling, but their design tolerances, sealing architectures, and bearing durability are increasingly judged against higher operating temperatures and longer service intervals. In electrified and hybrid applications, pumps must coordinate with control units to modulate flow, reduce parasitic load, and optimize thermal management across multiple subsystems. This creates a dual opportunity set: suppliers that can offer cost-effective standalone repair variants for the aftermarket while also delivering integrated, control-ready hardware for OEM thermal loops are positioned to capture demand across the vehicle lifecycle. Recent product visibility at industry exhibitions, including augmented-reality demonstrations of water pump innovations, suggests that leading suppliers are investing in visualization, training, and integration messaging to help customers understand how next-generation pumps function within complex cooling circuits.
Water Pumps Market
Regulatory and Standards Pressure
Policy and standardization activity is raising the bar for both production and service. On the manufacturing side, the expectation that automotive water pumps undergo complete leakage and functional testing is no longer an optional quality flourish; it is a baseline requirement for OEM and aftermarket acceptance. On the service side, evolving safety qualifications are changing who can handle cooling system repairs and what credentials are required, which indirectly affects the competitiveness of aftermarket suppliers that depend on broad installer adoption. At the same time, material expectations are shifting: premium alloy constructions are increasingly tied to durability assurance in high-temperature environments, which raises performance credibility but also pressures cost structures. The net effect is a market where compliance and validation are becoming strategic differentiators rather than administrative overhead.
Demand-Side Shifts Across Vehicle segments
Vehicle mix is changing the shape of demand. Passenger cars continue to represent the largest application pool, but the composition of that demand is being reshaped by hybrid penetration, extended maintenance cycles, and higher expectations for cooling reliability across a wider range of operating conditions. Commercial vehicle applications remain significant, and their cooling requirements are intensifying as heavy-duty platforms adopt more sophisticated engine families and operate under demanding duty cycles. Off-highway vehicles constitute a smaller but technically demanding niche, where robustness and application-specific fitment often outweigh pure price competition. Across these segments, the strongest growth is not simply in unit volume but in specification complexity: customers increasingly want components that can be installed with confidence, tested to recognized standards, and matched to the thermal load characteristics of the target vehicle.
Supply Chain and Cost Structure Reconfiguration
Materials, testing throughput, and geographic manufacturing footprints are recalibrating cost dynamics. The emphasis on premium alloys and full-functional testing increases the importance of supplier process capability and yield discipline. At the same time, the broader component ecosystem is adapting to higher content per vehicle in thermal management, which can support pricing power for suppliers that bring validated performance and application breadth. Geography also plays a role: different regions reflect distinct vehicle production patterns, service channel maturity, and regulatory expectations, meaning that suppliers with flexible manufacturing and strong regional coverage can better absorb localized cost shocks and respond to application-specific demand.
Competitive Landscape and Leading Strategies
The competitive field combines established global suppliers, regional specialists, and aftermarket-focused manufacturers, each pursuing a distinct route to relevance. The strategic puzzle is not who is largest in absolute terms, but who is best positioned to convert technical change into defensible share.
Global OEM-oriented suppliers such as Aisin and Continental are leaning into thermal management breadth and manufacturing credibility. Aisin’s position as a leading aluminum die-cast engine cooling water pump supplier to Japanese manufacturers, with expanding reach into European and American production, reflects the value of scale, casting expertise, and long-standing OEM relationships. Its recent demonstration of augmented-reality product innovations at a major industry event underscores a broader playbook: using visible technology demonstrations to signal engineering depth and to educate partners on new pump behaviors in electrified and hybrid cooling loops. Continental’s focus on standalone water pumps and kits for thermal management, including cost-effective variants without control units, highlights a complementary strategy: serving the repair and replacement market with practical, lower-integration options while still participating in higher-specification thermal management solutions.
In the aftermarket and engineered replacement space, brands such as Gates, Carter, and SKF are competing on performance assurance, coverage, and testing credibility. Gates emphasizes premium alloy automotive water pumps for late-model, hybrid, and vintage vehicles, paired with 100 percent functional and leakage testing, a positioning that directly addresses the rising quality expectations discussed earlier. Carter positions engineered water pumps for engine cooling with OEM-level performance and broad vehicle coverage, appealing to customers who want dependable replacement without sacrificing fitment confidence. SKF’s emphasis on precision pumps and high reliability for engine cooling reinforces the broader theme that durability and fit are increasingly valuable in a market where warranty exposure and installer trust matter.
Heavy-duty and commercial vehicle specialists illustrate a different competitive angle. US Motor Works, for example, maintains a professional-series heavy-duty water pump lineup covering platforms such as PACCAR and Detroit Diesel applications, supported by ISO 9001:2015 certified manufacturing. Its recent catalog updates and new part numbers for specific commercial engine families demonstrate how application-specific coverage and timely part expansion can defend share in commercial channels where downtime costs are high and specification accuracy is non-negotiable. Setco Automotive, based in India, has been expanding its water pump offerings within a broader thermal management and clutch component portfolio targeting passenger cars and light commercial vehicles, an example of how regional manufacturers can scale by aligning component portfolios with local vehicle mix and growing service demand.
Electric and thermal-management-focused entrants are also shaping the field. VALEO’s integration of electric and mechanical water pumps into vehicle cooling systems for passenger and commercial vehicles reflects the broader shift toward electrified thermal architectures. Bosch’s portfolio of water pumps, including switchable and control-unit variants for modern engine systems with expanded aftermarket part numbers, illustrates how established technology suppliers can bridge OEM content and aftermarket availability. Padmini VNA Mechatronics has been developing electric water pumps for EV and passenger vehicle thermal management, working with Indian OEMs such as Mahindra and Tata, which shows how regional suppliers can enter higher-value thermal content through partnerships and application-specific electrification support.
Taken together, these positions reveal three prevailing strategic orientations. First, some leaders are consolidating advantage through OEM content, casting and precision manufacturing, and thermal integration messaging. Second, others are differentiating through testing credibility, alloy and durability claims, and broad aftermarket coverage. Third, a third group is pursuing application-specific expansion in heavy-duty, commercial, or EV-adjacent segments where specification accuracy and regional vehicle mix create defensible niches. The likely trajectory over the next several years is continued differentiation rather than wholesale consolidation, because the value pool is splitting across high-specification OEM content, service-friendly repair kits, and specialized heavy-duty or electrified thermal applications.
Forward-Looking Trends and What They Mean for Commercial Strategy
Looking ahead three to five years, several trends are likely to define how the market matures and where commercial opportunities concentrate.
Trend One: Electronic Control and Thermal Management Will Become the Primary Margin Driver
As cooling loops grow more complex, the economic center of gravity will shift toward pumps and related hardware that integrate effectively with electronic control, support variable flow, and reduce thermal management load. This does not mean mechanical pumps will disappear; it means the highest-value work will increasingly involve coordination with control logic, coolant flow optimization, and application-specific validation. Suppliers that can offer both control-integrated solutions for new platforms and accessible repair options for the aftermarket will be better placed to capture value across the vehicle lifecycle. The commercial opportunity lies in packaging hardware with the technical support, diagnostics compatibility, and installer education that reduce friction in adoption.
Trend Two: Quality Assurance and Certification Will Separate Competitors
The expectations around 100 percent functional and leakage testing, premium material durability, and installer certification are not temporary frictions; they are becoming structural entry conditions. Companies that invest in testing throughput, process control, and clear quality communication will be able to command stronger positioning with OEMs and demanding aftermarket buyers. Conversely, suppliers that cannot demonstrate consistent validation or support the evolving competency requirements of the service channel will face growing disadvantages in warranty exposure, brand trust, and repeat procurement. For commercial strategy, this creates an opportunity to treat quality systems and certification readiness as market-facing assets rather than internal compliance tasks.
Trend Three: Regional Vehicle Mix Will Drive Asymmetric Growth Paths
Growth will not be uniform across regions because vehicle production, electrification pace, and service channel maturity differ. Asia Pacific’s scale in vehicle production and expanding local OEM ecosystems make it a central arena for both content and aftermarket development. North America and Europe will continue to reward suppliers that can combine broad coverage with strong application fit and service readiness, especially as hybrid and complex cooling architectures become more common in faster-turning replacement cycles. Latin America and the Middle East and Africa will remain important but likely more price-sensitive and infrastructure-dependent, where coverage, availability, and installer support can be as influential as technical differentiation. The strategic takeaway is that portfolios, manufacturing flexibility, and service networks must be calibrated to regional vehicle mixes rather than treated as homogeneous global demand.
These trends carry risks. Electrification timelines can shift, which changes the pace at which electric and hybrid thermal content scales. Testing and certification requirements may evolve further, raising compliance costs for suppliers that are slow to adapt. Material and manufacturing cost pressures can compress margins if yield and automation do not keep pace. And in the aftermarket, the success of cost-effective standalone repair variants depends on installer acceptance and diagnostic compatibility, which can be slower to develop than OEM adoption. Companies that monitor these signals closely will be better positioned to time portfolio investments and avoid overcommitting to a single trajectory.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with the dual reality of rising thermal complexity and persistent aftermarket demand for reliable, installable replacements. That means investing in testing capability, process control, and alloy or sealing architectures that support durability claims, while also building a portfolio that spans control-integrated hardware for OEM loops and cost-effective variants for repair markets. Equally important is application coverage: deep fitment support for high-value commercial engine families, hybrid platforms, and passenger-car segments where replacement frequency and warranty sensitivity justify stronger engineering and service content.
For investors, the most relevant question is where margin pools are expanding as the market shifts from commodity replacement toward validated performance and thermal integration. Opportunities are likely to be strongest in suppliers that combine application breadth with credible quality systems, in regional players that can scale with local OEM and service demand, and in companies that can bridge electric and mechanical cooling requirements without over-concentration in a single architecture. Due diligence should pay close attention to testing infrastructure, certification readiness, coverage depth in commercial and hybrid applications, and the ability to support installer education and service adoption.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet service organizations, the practical focus should be on reducing installation risk and warranty exposure while maintaining coverage across evolving vehicle populations. That argues for sourcing strategies that prioritize validated performance, clear documentation, and compatibility with existing service competencies, especially as certification expectations for cooling system repairs continue to tighten. In this environment, the value of detailed segment-level intelligence increases: knowing which applications are growing fastest, which specifications are becoming standard, and where testing or certification requirements are changing can materially improve sourcing decisions and inventory planning.
Detailed segmentation data, regional breakouts, application-level revenue estimates, and company-specific competitive benchmarks can sharpen these decisions further. For teams that need granular visibility into market splits, growth dispersion across vehicle types, and the strategic positioning of individual suppliers, the full research report provides the additional detail required to translate these trends into procurement roadmaps, portfolio priorities, and investment theses.
For detailed analysis of this topic, please visit the official page: Automotive Water Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com