

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Marine Propeller Market 2026–2032: The 6.6% CAGR, Asia Pacific Shift, and What Really Drives Growth

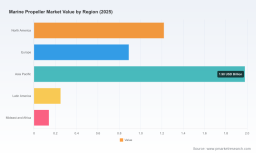
The Marine Propeller Market: Navigating Strategic Shifts and Commercial Opportunities (2026–2032)
The marine propeller market has entered a phase of structural growth, defined by steady expansion, evolving technological standards, and shifting regional demand patterns. Valued at approximately $4.48 billion in 2025, the sector is projected to reach $6.94 billion by 2032, reflecting a compound annual growth rate of 6.6 percent across the forecast period. This trajectory follows a measured recovery from the 2020–2023 cycle, where market valuations fluctuated between $3.56 billion and $3.84 billion amid supply chain disruptions, fluctuating shipbuilding activity, and varying regional investment rates. By 2024, momentum had clearly accelerated, crossing the $4.1 billion threshold and establishing a stronger base for the next decade. The numbers alone, however, tell only part of the story. Beneath the headline growth lies a market undergoing meaningful transformation in how propulsion systems are designed, manufactured, regulated, and integrated into broader maritime operations.
Stern Drive Boat Propeller Market
For executives, investors, and procurement leaders operating in or adjacent to the marine sector, understanding these shifts is no longer optional. Propeller technology sits at the intersection of vessel efficiency, emissions compliance, operational cost management, and regional industrial policy. As shipowners weigh lifecycle performance against upfront capital, and as manufacturers adapt to new material, production, and regulatory realities, strategic positioning will separate winners from followers. This analysis examines the core challenges shaping the market, the forces driving change, the competitive dynamics already in motion, and the strategic implications that will matter most through 2032.
Market Snapshot and Structural Baseline
The current market profile reflects a maturation phase rather than a speculative boom. Growth is broad-based but uneven, with certain applications and regions pulling ahead as vessel replacement cycles, naval modernization programs, and recreational boating demand align with more favorable economic conditions. The overall market trajectory from 2020 through 2032 suggests that while the sector weathered short-term volatility, underlying demand drivers have strengthened rather than faded. Revenue expansion is now supported by a combination of fleet renewal, efficiency mandates, and renewed investment in both commercial and leisure vessel segments.
Concentration patterns indicate that a relatively small group of established players continues to command a majority of market share, yet the landscape is not static. The top three companies hold roughly 55 percent of the market, with the top five reaching approximately 62 percent. This level of concentration points to entrenched relationships, technical expertise, and distribution networks that create meaningful barriers to entry. At the same time, the remaining share distribution leaves room for specialized manufacturers, regional specialists, and technology-focused entrants to compete on performance, customization, or cost structure rather than volume alone.
Critical Challenges and Inflection Points
Three interconnected challenges are reshaping how companies approach product strategy, capacity planning, and market entry.
PW Consulting Automotive & Machinery Research Center
- Regulatory and emissions pressure is redefining performance expectations. The maritime industry is navigating a more complex compliance environment, where operational efficiency is increasingly tied to emissions accounting, fuel choice, and lifecycle performance. Propellers are no longer evaluated solely on thrust delivery or cavitation resistance; they are now part of a broader efficiency equation that includes hull form, engine mapping, and fuel characteristics. This shift raises the bar for product validation, testing, and downstream integration, particularly for manufacturers serving commercial and naval customers with strict performance and compliance requirements.
- Input costs and order timing are creating planning complexity. Vessel construction costs and material pricing have introduced greater unpredictability into procurement cycles. New ship price indices have shown notable year-on-year increases, influencing vessel economics and, by extension, the timing and scale of propeller orders. When capital expenditure cycles stretch or accelerate unexpectedly, manufacturers must balance capacity utilization against inventory risk. This environment rewards companies that can adjust production lead times, communicate clearly with shipbuilders, and offer flexible specification options without compromising quality.
- Supply chain resilience and trade policy are altering sourcing strategies. Tariff actions and trade-related notices have brought renewed attention to dependency on specific sourcing corridors, especially for components and finished goods tied to maritime applications. For propeller manufacturers and distributors, this means that geographic concentration in supply chains is now a strategic risk factor rather than purely a cost consideration. Companies are reassessing where and how they source raw materials, finished components, and sub-assemblies, with resilience and lead-time predictability becoming core competitive attributes.
Key Drivers Reshaping the Market
Technology Innovation as a Competitive Differentiator
Propeller design is moving beyond incremental geometry improvements toward more integrated performance engineering. Advancements in machining precision, alloy performance, and computational design methods are enabling manufacturers to deliver propellers with better efficiency, reduced noise, and more predictable behavior across a wider range of operating conditions. In practice, this means that a propeller is increasingly evaluated as part of a propulsion system rather than a standalone mechanical component.
This shift is visible in recent product and production activity. One notable example is the rollout of multi-blade configurations designed for larger vessels, where performance and efficiency gains are pursued through blade count, pitch geometry, and material selection. Alongside product innovation, manufacturing method innovation is becoming just as important. Faster production pathways are being introduced to reduce lead times and improve scalability. The combination of advanced design and accelerated fabrication is changing the commercial calculus for both manufacturers and buyers, especially when delivery timing can influence vessel commissioning schedules and operational availability.
For companies operating in this space, the strategic implication is clear: design capability alone is no longer enough. The ability to translate engineering improvements into repeatable production, consistent quality, and cost-effective scaling is becoming the real differentiator. Manufacturers that can pair proprietary blade or hub designs with robust production processes are better positioned to capture value across both premium and volume-oriented segments.
Regulatory and Standards Evolution Affecting Design and Specification
Regulations and standards are shaping not only what ships must achieve, but how marine equipment is specified, validated, and documented. Standards development is becoming more granular, extending into component-level design and manufacturing details. Recent guidance on fixed-pitch propeller hub caps with fins, for example, signals a broader trend toward formalizing specifications that improve interchangeability, testing consistency, and design reliability.
At the same time, emissions-related frameworks are adding new layers to operational performance expectations. Guidelines addressing lifecycle greenhouse gas intensity and fuel-related emissions implications are reinforcing the importance of overall propulsion efficiency, including the role of propellers in reducing energy waste and improving vessel performance. For commercial operators, this can translate into a stronger preference for products that support lower fuel consumption and more predictable performance across operating profiles. For manufacturers, it means that technical marketing, specification support, and validation data are becoming increasingly important tools in the sales and engineering engagement process.
The practical consequence is that specification criteria are expanding. Buyers are looking for more than baseline thrust and durability; they want documentation, testing consistency, and assurance that a propeller will perform as part of an integrated efficiency strategy. Companies that invest early in compliance-aligned design, transparent performance data, and engineering support are more likely to win consideration in demanding commercial and naval applications.
Demand-Side Change Across Vessel Segments
Demand is being shaped by a mix of fleet renewal, operational economics, and leisure market dynamics. In commercial shipping, vessel replacement and upgrade cycles continue to drive demand for propulsion components that support efficiency and durability. Shipowners and operators are increasingly focused on total cost of ownership rather than lowest initial price, which favors propeller solutions that deliver measurable performance over the vessel’s operating life.
In naval applications, modernization programs and fleet requirements sustain demand for reliable, mission-appropriate propulsion systems. These programs often emphasize durability, specialized configurations, and long-term support relationships, creating a different set of competitive priorities than the commercial market. Meanwhile, the recreational segment remains sensitive to consumer spending, marine leisure trends, and product appeal. In this segment, performance characteristics such as noise reduction, ease of integration, and visible efficiency gains can influence purchasing decisions more directly than in commercial contexts.
Across these segments, one common theme is the growing importance of application-specific engineering. A propeller that performs well in one operating environment may not be optimal in another, and buyers increasingly expect manufacturers to demonstrate that differentiation. This encourages companies to prioritize segment-focused product development, targeted promotions, and channel strategies that align with how each customer group evaluates risk, cost, and performance.
Supply Chain and Cost Structure Realignment
The supplier base is being reshaped by changing cost structures, material availability, and regional sourcing considerations. The impact of shipbuilding cost movements on downstream component demand is a reminder that propeller markets do not operate in isolation. When new vessel pricing rises, order patterns, contract timing, and budget allocations can shift in ways that affect manufacturers’ planning horizons. This environment favors suppliers that can offer stable lead times, transparent cost communication, and flexible fulfillment models.
Material selection is also becoming more strategically important. The balance between aluminum, stainless steel, and specialized alloys is influenced not only by performance requirements but also by availability, processing complexity, and total cost. Manufacturers with strong casting, machining, and inspection capabilities have an advantage when they can produce consistent results across material types while controlling cycle times. This is particularly relevant when buyers are trying to manage both performance and procurement risk simultaneously.
In addition, trade-related actions are prompting companies to think more carefully about geographic exposure. For some market participants, resilience is being achieved through diversified sourcing, regional production footprints, or closer integration with shipbuilding and distribution partners. The long-term effect is likely to be a more deliberate approach to supply chain design, where agility and predictability are treated as strategic assets alongside unit economics.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiated Playbooks
The competitive field includes a wide range of participants, from large manufacturers with broad commercial and defense exposure to highly specialized firms focused on niche applications or particular production methods. Several companies illustrate the different ways to compete:
- Broad commercial and military reach with disciplined portfolio focus. Some manufacturers have built their reputation on inboard and outboard propellers, rudders, and struts across recreational, commercial, and military vessels. Their advantage typically lies in broad application knowledge, established distribution, and the ability to serve multiple customer groups without losing technical credibility. Recent moves to divest non-core geographic operations suggest a willingness to concentrate resources where scale, support, and product alignment are strongest.
- High-technology, precision-machined propulsion solutions. Other companies compete through specialized design and CNC-machined propellers intended for high-speed and efficiency-focused applications. Their product range often extends into specialized vessel types, where performance and refinement matter as much as raw thrust. This positioning tends to attract buyers who value engineering differentiation and are willing to pay for tailored performance characteristics.
- Patented design and efficiency-led positioning. A different strategic path is visible among firms that emphasize proprietary blade designs, reduced noise, and efficiency claims supported by distinct manufacturing approaches. When those claims are reinforced by production partnerships or advanced fabrication methods, the result can be a compelling story for both commercial and recreational buyers looking for measurable gains.
- Regional specialists and custom engineering providers. There is also a strong constituency of manufacturers that compete through custom builds, repair and tuning services, precision casting, and application-specific solutions. These companies may not lead in global volume, but they can win on responsiveness, technical adaptation, and local support. In markets where vessel types, operating conditions, and customer preferences vary widely, that flexibility carries real commercial value.
Together, these profiles show that success does not depend on a single formula. Some players win through portfolio breadth and established relationships; others through specialized performance, proprietary design, or service depth. The common thread is clarity of positioning. Companies that try to compete everywhere often struggle to communicate why they are the right choice for a specific application or buyer profile.
Market Evolution: Consolidation, Specialization, and New Entry
The market is likely to continue evolving along several overlapping paths. Consolidation will remain relevant where scale, supply chain control, and global service networks create advantages. Strategic transactions that release management attention and capital from less-central operations can allow leading players to concentrate on core segments and higher-value product lines. At the same time, specialization is gaining importance because efficiency, noise, and application-fit are increasingly visible decision factors. That opens space for firms that can solve a specific problem very well, even if they do not compete across the entire market.
New entry and expansion are also being shaped by production innovation. When advanced fabrication methods reduce cycle times and improve repeatability, they lower one of the traditional barriers to scaling specialized products. That can enable faster commercialization of new designs and make it easier to serve demanding customers without sacrificing quality. The broader effect is a market in which differentiation is increasingly tied to how quickly and reliably a company can bring a proven design to market, not just whether it has a promising concept.
Industry events and association activity also play a role in shaping the competitive rhythm. Expos and technical gatherings provide venues for product introductions, supplier networking, and cross-industry signaling. They are not themselves competitive advantages, but they reflect a market where visibility, peer validation, and hands-on demonstration still matter. Companies that use these channels effectively often reinforce their positioning more quickly than those that rely on broad advertising alone.
Forward Trends and Commercial Implications (2026–2032)
Efficiency as the Central Commercial Currency
Over the next several years, efficiency is expected to remain the dominant value proposition in the propeller market. This does not mean every buyer will make the same choice, but it does mean that products and services will be evaluated against their contribution to fuel economy, operational smoothness, and overall propulsion performance. Manufacturers that can quantify performance benefits and align them with real operating conditions will have an advantage in both specification and repeat business.
Commercial opportunity here lies in moving from product selling to performance selling. That may involve better testing data, more detailed application guidance, and closer collaboration with vessel designers and operators. It also creates room for aftersales support, refurbishment, and condition-based service models that help customers extract more value from their propulsion systems over time.
Production Speed and Scalability as Strategic Assets
Speed of production is likely to become a more visible competitive factor, especially as manufacturers introduce advanced casting, machining, and process-control methods. Shorter lead times can reduce inventory pressure, improve responsiveness to custom orders, and help align propeller supply with vessel commissioning schedules. For buyers, this can translate into lower scheduling risk and greater flexibility in fleet planning.
The commercial implication is that manufacturers who can demonstrate reliable delivery without compromising quality will be favored in time-sensitive segments. This is particularly relevant where premium designs are being scaled for broader use. The ability to produce complex designs with repeatable quality and shorter timelines can widen the addressable market for high-performance solutions, creating new growth paths beyond niche applications.
Regulatory Alignment and Specification Support as Table Stakes
As standards and emissions-related expectations become more embedded in procurement decisions, regulatory alignment will increasingly function as a baseline requirement rather than a differentiator reserved for a few leaders. That does not mean every company must become a standards body, but it does mean that documentation, design traceability, and validation support will matter more in competitive evaluations.
For companies serving commercial and naval customers, this trend raises the importance of engineering-led engagement. Buyers are more likely to value suppliers who can help them interpret requirements, justify specifications, and ensure that the selected propeller fits within a broader compliance and efficiency strategy. The opportunity is to build trust through technical credibility and consistent support, not just price competitiveness.
Risks and Uncertainties to Monitor
Even with a clear growth trajectory, there are meaningful uncertainties. Material cost volatility can affect margin planning and order timing. Trade policy shifts may alter sourcing advantages or increase friction in certain supply chains. Macroeconomic conditions can influence leisure demand and commercial capital spending in ways that are difficult to predict far in advance. In addition, standards and compliance expectations can evolve faster than product cycles, creating adaptation pressure for manufacturers with long lead-time development pipelines.
Companies should therefore treat flexibility as a core strategic requirement. That includes the ability to adjust product mix, production allocation, and sourcing strategies without losing quality or service reliability. It also means monitoring regulatory and cost signals closely enough to act before disruptions become urgent.
Airplane Propellers Market
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Clarify where your advantage is real and repeatable. Whether it is design uniqueness, production speed, material expertise, or application-specific service, make sure the market understands the problem you solve best and why your solution is defensible.
- Invest in the bridge between engineering and production. Advanced designs only create value when they can be manufactured consistently and at scale. Prioritize process control, lead-time reduction, and quality repeatability as part of the product strategy, not as a separate operations topic.
- Build specification support into the commercial model. As buyers evaluate efficiency, compliance, and integration more closely, strong technical documentation and application guidance can shorten sales cycles and improve win rates in demanding segments.
For Investors and Strategic Allocators
- Look for companies that combine differentiated technology with credible production pathways. Concepts are common; scalable execution is not. Businesses that can show both are better positioned to convert innovation into durable revenue.
- Assess exposure to segments with stronger spending resilience. Commercial efficiency demand, naval programs, and selective recreational applications may respond differently to economic cycles, so segment mix matters when evaluating growth durability.
- Monitor consolidation signals and supply chain restructuring. Strategic divestitures, regional sourcing shifts, and production partnerships can reveal where value is concentrating and which capabilities are becoming more valuable over time.
For Procurement and Fleet Decision Makers
- Evaluate propellers as part of total propulsion performance, not as isolated components. The best choice often depends on vessel type, operating profile, material requirements, and lifecycle cost, so supplier engagement should go beyond specification sheets.
- Prioritize suppliers with consistent delivery, transparent quality processes, and the ability to support custom requirements. In environments where commissioning schedules and operational continuity matter, reliability can be as valuable as marginal performance gains.
- Ask for evidence tied to your operating context. Performance claims should be aligned with the conditions your vessels actually face, including speed ranges, load patterns, and maintenance realities.
Closing Perspective
The marine propeller market is expanding with discipline rather than speculation. Demand is supported by fleet renewal, efficiency expectations, naval requirements, and evolving leisure activity, while growth is being shaped by technology, standards, cost dynamics, and supply chain strategy. In this environment, the most successful players are likely to be those that combine engineering credibility with production discipline, segment clarity, and responsive customer support.
For organizations seeking a deeper view of segmentation detail, regional dynamics, competitive benchmarking, and scenario-based planning data, a more comprehensive research reference can provide the granularity needed for investment, product, and procurement decisions. A full market study offers the additional breakdown required to translate these strategic directions into operational action with greater confidence.
For detailed analysis of this topic, please visit the official page: Marine Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com