

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Motor Spindles Market 2026: Why 5.3% CAGR Reshapes Asia Pacific Growth

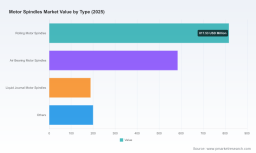
Strategic Trends and Commercial Opportunities in the Motor Spindles Market (2025–2032)
The motor spindles market has matured into a critical enabler of advanced manufacturing, with total market revenue reaching approximately 1,790 million USD in 2025 and projected to expand at a compound annual growth rate of 5.3 percent through 2032. The trajectory reflects more than steady growth; it signals a structural shift in how precision machining, high-speed automation, and digitalized production systems are being deployed across industrial sectors. For executives and investors, the market presents a compelling intersection of incremental volume expansion and qualitative transformation, where competitive advantage increasingly depends on technological differentiation, regulatory compliance, and supply chain agility rather than scale alone.
Understanding the strategic direction of this segment requires looking beyond headline revenue figures. The composition of demand, the evolution of manufacturing locations, and the pace of innovation are reshaping where value is created and how incumbents defend or expand their positions. This analysis examines the market fundamentals, the forces driving change, the competitive architecture, and the forward-looking opportunities that strategic decision-makers should factor into planning cycles.
Market Landscape and Core Challenges
The baseline market dynamics point to a segment that has recovered strongly from earlier disruptions and is now operating in a phase of sustained expansion. Revenue has grown consistently from roughly 1,424 million USD in 2020 to an estimated 1,790 million USD in 2025, with the forecast period projecting steady climbs toward approximately 2,552 million USD by 2032. This trajectory reflects broad-based demand rather than reliance on a single sector, with multiple application domains contributing to the overall volume.
Despite the favorable growth backdrop, the market faces several structural inflection points that will determine which participants capture disproportionate value in the coming years.
-
Precision and performance thresholds are rising faster than commoditization pressures. Buyers across machining, electronics, and automation applications increasingly demand spindles that deliver lower vibration, tighter thermal stability, and higher rotational consistency. Meeting these expectations requires advanced bearing architectures, refined cooling methods, and tighter manufacturing tolerances, which elevates the technical barrier to entry and compresses margins for undifferentiated offerings.
-
Regulatory and environmental compliance is reshaping design and sourcing decisions. Stricter directives on energy efficiency, noise and vibration control, and material compliance are pushing manufacturers to adopt sustainable cooling systems, optimize motor efficiency, and align with certification frameworks for export markets. These requirements are not merely administrative; they influence product architecture, supplier selection, and total cost of ownership calculations.
-
Supply chain localization and component availability remain sensitive points. As end-users prioritize resilience and shorter lead times, manufacturers must balance the cost advantages of globalized sourcing with the operational benefits of regionalized production and component stocking. Volatility in precision components and bearings can disrupt delivery schedules and pressure pricing discipline, especially for high-performance spindle systems where lead times directly affect machine uptime.
Taken together, these challenges point to a market where technical credibility, compliance readiness, and supply chain reliability are becoming as important as unit pricing. Participants that treat these factors as strategic differentiators are better positioned to defend share and command premium positioning.
PW Consulting Automotive & Machinery Research Center
Key Drivers of Market Change
The growth path of the motor spindles market is not uniform across drivers; it is being shaped by a combination of technological, regulatory, demand-side, and supply chain forces that reinforce one another.
Technological Innovation and Performance Breakthroughs
Innovation in spindle architecture continues to expand the envelope of what is possible in high-speed machining and precision material removal. Developments in air bearing and liquid journal designs, as well as improvements in built-in motor integration, are enabling lower runout, better thermal management, and reduced vibration in demanding applications. The introduction of ultra-compact angle spindles and refined series for micro-grinding, milling, and engraving illustrates how manufacturers are pushing size and precision boundaries simultaneously. These advances matter because they allow machine builders to increase feed rates, improve surface quality, and reduce tool wear without enlarging machine footprints, which is particularly valuable in space-constrained production environments.
Policy and Regulatory Environment
Regulatory pressure is becoming a meaningful design constraint and, in some cases, a catalyst for innovation. European Union environmental regulations are encouraging adoption of sustainable cooling systems in motor spindles, while tightening ISO standards for vibration and noise control are raising the baseline performance expectations for precision spindle applications. At the same time, increased emphasis on CE marking and RoHS compliance is shaping export-market readiness, and new EU directives on energy efficiency are pushing industrial automation users toward optimized spindle motors that reduce power consumption without sacrificing throughput. These requirements are gradually becoming table stakes for suppliers targeting regulated markets, and they reward manufacturers that can demonstrate validated compliance and efficiency gains in a credible, documented manner.
Demand-Side Shifts in End Markets
Demand patterns are being reshaped by the expansion of electronics fabrication, precision machinery production, and high-value component manufacturing in automotive and aerospace contexts. The continued scaling of printed circuit board production and consumer electronics assembly is driving need for spindles that can handle fine-detail machining and consistent high-speed operation. At the same time, machinery manufacturers and automation integrators are seeking spindle solutions that integrate more smoothly into digital workflows, support quick-change tool systems, and provide predictable performance over extended operating cycles. The practical implication is that demand is increasingly fragmented by application requirements, and the most attractive commercial opportunities lie in solutions tailored to specific performance profiles rather than generic high-speed units.
Supply Chain and Cost Structure Evolution
Cost dynamics are being influenced by a combination of energy efficiency expectations, material and component pricing, and the strategic trade-offs between centralized production and regional responsiveness. Suppliers with mature manufacturing footprints and long production histories are leveraging scale and process maturity to maintain competitiveness, while others are pursuing product line specialization to differentiate on performance, tool-change convenience, or application fit. In parallel, the push for energy-efficient industrial automation is encouraging customers to evaluate total operating cost rather than upfront price alone, which favors solutions that deliver better efficiency, lower maintenance burden, and longer service intervals. This shift in evaluation criteria is gradually altering negotiation dynamics and creating room for value-based positioning.
Competitive Landscape and Leading Strategies
The market is characterized by a concentration level that remains moderate, with the largest players holding a meaningful but not dominant share of total revenue. This structure creates room for differentiated specialists to compete effectively while rewarding incumbents that can blend technical depth with service reliability and regional reach.
Several companies illustrate the strategic diversity shaping the competitive field.
-
Nakanishi Inc. has built a strong identity around high-precision motor spindles for micro-grinding, milling, and engraving, with product families that emphasize refined control and updated catalog breadth. The recent introduction of what the company describes as the world’s smallest angle spindle signals a continued push into ultra-compact, high-precision niches where size and accuracy are both commercially valuable.
-
GMN Paul Müller Industrie GmbH & Co. positions itself around high-quality spindle systems for machine tools, grinding, and precision applications, with an emphasis on digital twin integration and rapid service response. This combination of advanced simulation capability and service availability supports customers who prioritize uptime and predictive maintenance in production-critical environments.
-
HSD Mechatronics S.p.A. focuses on quick-change air and liquid-cooled electrospindles for metal, wood, plastic, and aluminum machining. Its presence at major industry events with comprehensive machining solution showcases reflects a strategy centered on application breadth and system-level compatibility rather than narrow product specialization.
-
WEISS Spindle Technology GmbH develops motor spindles for high-performance cutting across milling, turning, grinding, and robot applications, with a strong emphasis on optimized cooling and precision. Its multi-application orientation suggests a strategy aimed at serving customers who need consistent performance across varied machining contexts.
-
MicroLab Precision Technology Co., Ltd. produces built-in motor spindles, machining center spindles, and rotary spindle heads with low vibration and high precision for high-speed machining. This profile highlights a focus on integrated spindle solutions that support precision CNC workflows and reduce integration complexity for machine builders.
-
Jiangsu HQD Spindle Motor Co., Ltd. manufactures electric spindle series for engraving, milling, woodworking, and automatic tool change applications, and maintains active participation in trade shows to showcase automatic tool change spindle solutions alongside broader electric spindle lines. This suggests a commercial emphasis on versatility, application coverage, and visible market engagement.
-
Changzhou Sulong Precision Motor Co., Ltd. supplies high-speed electric spindles and spindle parts for precision CNC and engraving use, indicating a positioning centered on component and spindle availability for precision-oriented machining customers.
-
WHD Spindle Motor Co., Ltd. specializes in automatic tool change, air-cooled, and water-cooled high-speed spindle motors for CNC machine tools with a long production history, reflecting a strategy built on product range breadth and manufacturing continuity.
Recent market activity reinforces the strategic themes behind these profiles. The introduction of compact angle spindle technology, the showcase of electric spindle lines at major exhibitions, and the launch of heavy-duty spindle motors for demanding machine tool applications all point to a competitive environment where product refresh cycles are active and application-specific differentiation is increasingly important. Participation in trade shows across regional markets also indicates that suppliers are investing in visibility and customer engagement as part of their growth strategy, particularly in segments where specification decisions are influenced by direct product comparison and live demonstrations.
The competitive evolution appears to be moving along two parallel tracks. On one hand, established players are deepening their advantage through precision engineering, cooling and control optimization, and service-oriented models that reduce customer downtime. On the other hand, specialized entrants and regional suppliers are carving out positions by focusing on particular application sets, tool-change convenience, or cost-efficient production for price-sensitive but volume-important segments. Consolidation remains possible where scale, certification, and service networks create genuine barriers, but fragmentation is likely to persist in niche performance categories where tailored design and rapid customization matter more than broad portfolio size. New entrants will need to demonstrate credible technical capability and compliance readiness to gain traction in regulated or high-precision channels, while established suppliers will need to continue refreshing portfolios to prevent commoditization in more standardized segments.
Machine Tool Spindles Market
Forward-Looking Trends for the Next 3–5 Years
Looking ahead, several trends are likely to shape commercial outcomes and determine which opportunities scale most effectively.
Performance differentiation will increasingly hinge on thermal, vibration, and efficiency control
As machining requirements become more exacting and automation environments demand predictable behavior over longer cycles, spindles that deliver superior thermal stability, lower vibration, and better energy efficiency will command stronger positioning. This trend creates opportunities for suppliers that can validate performance claims with measurable metrics and integrate spindle behavior into broader machine optimization strategies. It also raises the importance of testing, documentation, and application-specific tuning as commercial enablers.
Application-tailored portfolios will outperform generic high-speed offerings
Demand is becoming more segmented by end-use requirements, and buyers are increasingly selecting spindle solutions based on compatibility with specific materials, tool-change systems, and production workflows. Suppliers that organize product lines around application contexts, and that provide clear guidance on performance trade-offs, will be better positioned to capture premium demand. This shift favors companies that combine engineering depth with commercial clarity, and it reduces the advantage of broad but undifferentiated portfolios.
Regulatory and sustainability alignment will become a market-access requirement
As environmental and efficiency directives continue to influence procurement decisions, compliance readiness and demonstrable sustainability improvements will matter more in bids for regulated markets and export-oriented programs. This trend will likely reward suppliers that proactively design for efficiency, adopt sustainable cooling approaches, and maintain documentation that simplifies customer certification processes. At the same time, it introduces a risk for participants that treat compliance as a retroactive adjustment rather than a design principle, since late adjustments can delay launches and increase cost.
These trends are not independent. Efficiency and thermal performance improvements support sustainability objectives, application-specific tuning supports customer productivity goals, and compliance readiness supports market access. Together, they point to a market where integrated value propositions will increasingly outperform narrow price competition.
Potential risks and uncertainties should also be factored into planning. Shifts in regional demand intensity, changes in component availability, and the pace of regulatory implementation can affect both cost structures and timing. In addition, if performance requirements converge across segments faster than expected, differentiation windows may narrow, intensifying competition in previously protected niches. Participants should therefore monitor not only product cycles but also the regulatory calendar, customer procurement criteria, and regional industrial investment patterns.
Strategic Implications for Decision-Makers
The motor spindles market offers genuine growth, but the distribution of value will depend on how well companies align product strategy, compliance posture, and customer engagement with the market’s evolving performance expectations.
For manufacturers and spindle suppliers
-
Prioritize design and documentation that make efficiency, vibration control, and cooling performance verifiable. In a market where buyers are increasingly evaluating total operating cost and regulatory readiness, credible validation can support premium positioning and shorten procurement cycles.
-
Organize product communication around application outcomes rather than specifications alone. Clear mapping between spindle configurations and machining contexts helps customers choose faster and reduces the risk of mismatch-driven returns or underperformance.
Automatic Tool Change Spindle Market -
Strengthen service and availability propositions where uptime is commercially critical. Quick response, predictable lead times, and compatible tool-change options can be decisive in competitive bids, especially for production environments where downtime carries high cost.
For investors and strategic partners
-
Favor participants with clear technological differentiation and evidence of repeatable product refreshes, since the market is rewarding sustained innovation over static portfolios. Look for companies that can connect product performance to measurable customer benefits in precision, efficiency, or service reliability.
-
Assess exposure to regulated and export-oriented demand, as compliance readiness and certification discipline are becoming meaningful determinants of market access. Businesses that have integrated these requirements into product development are less exposed to launch delays and redesign costs.
-
Watch for consolidation opportunities in segments where scale, service networks, and certification create durable barriers, while recognizing that specialized niches may remain attractive for focused operators with strong application expertise.
For procurement and engineering decision-makers
-
Evaluate spindle selections against total cost of ownership, including energy consumption, thermal stability, maintenance intervals, and compatibility with existing tool-change and automation systems. Upfront price is only one component of value in high-utilization environments.
-
Clarify application requirements early and request performance data that reflect real operating conditions rather than generic benchmarks. This reduces the risk of over-specifying where unnecessary or under-specifying where precision matters.
-
Consider supplier capability in documentation, compliance support, and after-sales responsiveness as part of the sourcing decision, since these factors increasingly influence long-term operating reliability and audit readiness.
Decisions in this market are most effective when grounded in current, granular insight into segment performance, regional demand intensity, and product-level differentiation. The motor spindles market is large enough to support multiple successful strategies, but the strategies that work are becoming more specific, more application-aware, and more dependent on verifiable performance and compliance. For teams evaluating market entry, portfolio planning, or investment allocation, more detailed segmentation data and customized scenario analysis can help translate these directional trends into precise commercial choices.
For detailed analysis of this topic, please visit the official page: Motor Spindles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com