

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
HDTV Antennas Market: Why 7.12% CAGR and Residential Demand Redefine Growth

Strategic Trends and Commercial Opportunities in the HDTV Antennas Market
1. Market Snapshot and Core Challenges
The over-the-air antenna sector has navigated a decade of steady expansion, driven by renewed interest in broadcast television, cord-cutting momentum, and incremental product innovation. Historical data from 2020 through 2025 reflects consistent top-line growth, with the market reaching a baseline valuation in the mid-$180 million range by 2025. Forward projections from 2026 to 2032 point toward continued expansion at a compound annual growth rate of approximately 7.12 percent, positioning the category as a resilient niche within the broader broadcast reception ecosystem. This trajectory suggests that antennas are no longer relegated to a legacy accessory but have evolved into a strategic hardware component for households and businesses seeking reliable, low-cost access to local television signals.
Several structural challenges now define the market's inflection points. First, the shift toward next-generation broadcast standards creates uncertainty around legacy hardware compatibility. As broadcasters explore voluntary transitions to enhanced digital formats, manufacturers and consumers must balance near-term purchasing decisions against the risk of premature standardization. Second, housing and installation dynamics remain a persistent friction point. Over-the-air reception depends heavily on line-of-sight placement, building materials, and outdoor mounting conditions. Regulatory protections exist to prevent unreasonable restrictions on antenna installation, yet enforcement variability and design constraints continue to complicate residential deployments in multi-unit buildings and dense urban environments. Third, consumer perception lags behind actual signal quality improvements. Many households still associate antennas with outdated image quality and limited channel access, creating an education gap that slows conversion among cord-cutters who have not yet tested modern reception hardware.
These challenges do not undermine the market's fundamentals, but they shape the pace and direction of adoption. In markets where digital transition momentum accelerates, antenna relevance grows alongside broadcast availability. In contexts where infrastructure, housing density, or regulatory clarity lag, demand remains fragmented and more sensitive to product performance and ease of installation.
2. Key Demand Drivers Reshaping the Category
The market's evolution is shaped by a mix of technological, regulatory, demand-side, and supply-side forces. Each driver interacts with the others, creating a dynamic environment where product performance, policy clarity, and user behavior converge.
Technology Innovation and Hardware Differentiation
Modern antenna designs have moved well beyond the basic antenna shapes of earlier decades. Amplified and non-amplified configurations now serve different use cases, while directional models address scenarios where signal strength and source alignment matter most. Amplification circuits help households overcome weak signal environments, but they also require careful tuning to avoid overdriving reception or amplifying noise. Directional designs, while representing a narrower portion of the installed base, provide specialized value for long-range reception and targeted signal capture. Beyond form factors, improvements in signal processing, weather-resistant materials, and streamlined mounting systems contribute to higher user confidence and lower installation friction. Manufacturers that combine clearer signal capture with intuitive setup experiences gain an advantage in a market where ease of use strongly influences repeat purchase and word-of-mouth adoption.
Mobile Phone Antenna Market
Policy and Regulatory Momentum
Regulatory activity has become a meaningful catalyst for market direction. The Federal Communications Commission advanced rulemaking in late 2025 to authorize permissive use of the next-generation broadcast television standard, supporting a voluntary broadcaster transition. Around the same timeframe, legislative attention intensified, with a broad group of lawmakers urging regulators to accelerate the transition so households could access the full benefits of enhanced broadcast capabilities. Alongside these developments, the Over-the-Air Reception Devices rule continues to protect consumer access by limiting unreasonable restrictions on antenna installation by homeowners' associations and similar bodies. Together, these forces create a policy environment that supports broadcast reception while leaving transition pace largely dependent on broadcaster willingness and market readiness. The practical effect is a market that benefits from enabling rules but must still contend with staggered adoption across regions and stations.
PW Consulting Automotive & Machinery Research Center
Consumer and Enterprise Behavior Shifts
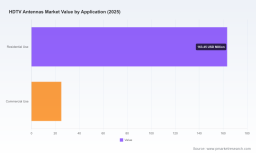
Demand-side behavior has shifted as households and businesses reassess how they access video content. Cord-cutting continues to motivate consumers to explore free local broadcast options, especially in markets where streaming subscriptions accumulate costs or where internet reliability fluctuates. Residential use remains the dominant application context, reflecting the core pull of household entertainment, local news, and emergency broadcast access. At the same time, commercial use cases have expanded in more specialized scenarios, including hospitality, shared living facilities, and mobile or recreational settings where reliable off-network reception adds value. In both cases, the strategic appeal of antennas lies in cost efficiency and independence from recurring subscription fees, provided the hardware can deliver consistent signal quality and user-friendly setup.
Supply Chain and Cost Structure Considerations
Cost dynamics in manufacturing, components, and distribution influence both pricing strategy and margin management. The antenna category benefits from relatively modular production compared with more complex electronics categories, yet material costs, logistics variability, and the performance requirements of outdoor-rated hardware still shape product economics. Suppliers that can standardize reliable internal components while maintaining outdoor durability, weather resistance, and low noise amplification are better positioned to manage cost volatility. Distribution has also become more complex as customers expect both direct purchasing options and retail availability to compare products. For manufacturers, balancing channel strategy with product consistency and regional support can determine how efficiently growth translates into profitability.
3. Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with no single company dominating the category and room for differentiated positioning across product families, use cases, and distribution models. Core players illustrate how manufacturers compete on performance, brand trust, and specialization rather than scale alone.
Antennas Direct has built its identity around digital and HDTV antenna systems for over-the-air reception, with indoor and outdoor models aimed at households seeking free local HDTV channels. Its market narrative emphasizes cord-cutting and access to local broadcast without recurring fees, aligning product positioning with the broader consumer shift away from traditional pay television. Winegard Company competes with a focus on outdoor and indoor reception solutions and long-range VHF/UHF performance, including models designed for residential and recreational vehicle use. This dual emphasis allows the company to address both stationary home reception and mobile or semi-mobile use cases where signal range and durability matter. ANTOP Antenna operates with a broader portfolio spanning indoor, outdoor, and marine HDTV antennas, alongside signal distribution products. Its export-oriented approach and wider application coverage give it a distinct footprint in both consumer and specialized environments where multi-channel distribution and reception resilience are priorities.
These companies illustrate three strategic advantages that matter in this market. First, product clarity helps reduce purchase hesitation; customers often compare amplified versus non-amplified options and need guidance that matches their signal environment. Second, installation and usability are competitive differentiators, since a well-performing antenna that is difficult to mount or configure can underperform in real-world adoption. Third, brand trust in over-the-air reception depends on consistent signal claims, support resources, and realistic expectations around range and channel availability.
Market evolution is likely to continue along both consolidating and fragmenting paths. Larger electronics and accessory players may seek adjacency to expand their home entertainment portfolios, while specialized antenna manufacturers may deepen their lead in particular use cases such as long-range reception, marine settings, or streamlined indoor designs. New entrants can still find room by targeting underserved scenarios, including properties with challenging signal environments or users who need compact, aesthetics-conscious designs. The result is a competitive landscape that rewards focused engineering, credible product claims, and channel alignment rather than pure scale.
4. Forward-Looking Trends and Commercial Implications
Looking ahead, several trends are likely to shape the market over the next three to five years, with clear implications for product strategy and commercial positioning.
One important trend is the gradual influence of next-generation broadcast standards on hardware expectations. As broadcasters evaluate voluntary transitions, the market will likely see a dual-track environment in which legacy-compatible antennas remain relevant for the near term while enhanced-format compatibility becomes a more prominent question over time. The commercial implication is that manufacturers and retailers should avoid overcommitting to a single transition assumption too early, while still preparing product messaging and engineering roadmaps for evolving signal environments. The uncertainty here is not whether broadcast technology will continue evolving, but how quickly-station-by-station and region-by-region adoption will occur.
A second trend is the growing importance of installation experience and signal predictability. As customers compare antennas against streaming alternatives, the decision often comes down to whether the antenna will reliably deliver local channels with minimal setup hassle. Products that simplify placement, improve signal capture consistency, and provide practical guidance for different housing types can reduce the gap between purchase intent and satisfied use. The opportunity lies in transforming antennas from a technically variable purchase into a more predictable home entertainment solution. The risk is that overpromising on range or channel counts can undermine trust if real-world results vary by location.
A third trend is the continued expansion of specialized and niche applications. While residential use dominates overall demand, commerical and specialized deployments create higher-value scenarios where durability, distribution, and long-range performance are especially important. Marine, recreational, and shared-facility contexts can benefit from products designed for specific environmental or operational needs. The related risk is that these niches remain small in aggregate and require targeted support, documentation, and channel relationships to scale efficiently.
Across these trends, the common thread is that antennas are increasingly judged not as isolated hardware, but as part of a broader home and commercial connectivity experience. That framing creates opportunities for manufacturers, distributors, and buyers who treat reception quality, ease of installation, and compatibility planning as core value drivers rather than secondary features.
5. Strategic Recommendations for Decision Makers
Different stakeholders face different priorities, but several actionable themes apply across the board.
For manufacturers and product leaders, engineering focus should prioritize real-world signal performance and installation simplicity alongside feature differentiation. Clear guidance on when amplified, non-amplified, or directional designs make sense can reduce returns and improve customer satisfaction. In addition, positioning products with credible expectations around range, signal conditions, and compatibility helps build trust in a category where user disappointment often stems from mismatched assumptions rather than product failure. Companies should also monitor broadcast transition developments closely and align product roadmaps to maintain flexibility without making premature bets on a single standard path.
For investors and market observers, the category offers a stable growth profile with a moderate growth rate and multiple expansion levers, including product segmentation, specialized applications, and distribution optimization. The more important question is not whether the market will grow, but which players capture value through better product-market fit, stronger channel execution, and credible transition readiness. Investment theses should account for the fact that competitive advantage in this space tends to come from specialization and customer experience as much as from scale.
For procurement teams and commercial buyers, selection should depend on site conditions, signal environment, and intended use rather than on headline specifications alone. Residential buyers should weigh mounting constraints, indoor versus outdoor needs, and the practical benefits of amplification based on local reception quality. Commercial and specialized buyers should assess durability, distribution requirements, and long-term maintenance considerations. In both cases, documented performance expectations and support resources can be as valuable as hardware cost when evaluating total value.
Automobile Antenna Market
For organizations seeking a deeper, segment-level view of revenue splits, regional dynamics, application breakdowns, and concentration patterns, a more detailed research package can provide the refined data needed to support planning, pricing, and competitive benchmarking. PW Consulting offers tailored market intelligence that translates category-level trends into targeted decisions, with the option to access full segmentation, company profiles, and scenario-based analysis through the complete HDTV Antennas Market research report.
For detailed analysis of this topic, please visit the official page: HDTV Antennas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com