

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting: Nursing Bras Market to Reach USD 2,510M by 2032 at 8.1% CAGR
By pmarketresearch, 2026-07-09
Nursing Bras Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s Nursing Bras Market study is designed as an operational playbook for executives, product leads, and investors preparing decisions across 2026. This briefing distills the study’s strategic value: it reveals why the category is shifting from a niche postpartum accessory into a mainstream, innovation-driven subsegment of intimate apparel—and which levers matter most for near-term commercial success. We surface the structural drivers, competitive moves, and supply-chain constraints that will determine winners, while deliberately reserving the full, granular segmentation and scenario tables for the complete report.
Nursing Bras Market
Market trajectory and why 2026 is pivotal
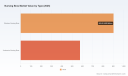
The category moved from a stable niche in the early 2020s to a double-digit growth trajectory by mid-decade. Our base-year analysis (2025) benchmarks the global market at approximately USD 1.48 billion, with a compound annual growth rate of 8.1% across the forecast window (2026–2032). By 2032 the market is projected to exceed USD 2.5 billion under the baseline scenario. That pace is sufficient to change strategic calculus for mainstream apparel brands, private-label retailers, and specialist innovators alike: what was once incremental revenue now represents a platform for adjacent services (pumping solutions, subscription replacement, certified materials) and durable customer relationships across pregnancy and postpartum cohorts.
Nursing Bras Market
Three structural dynamics converge to make 2026 a strategic inflection point:
Nursing Bras Market
- Product innovation (hands‑free pumping, breathable quick‑dry zones, seamless wireless constructions) is moving from premium niche to broad market adoption.
- Regulatory and certification pressures (material safety and Oeko‑TEX® standards) are increasing supplier switching costs and raising barriers for low‑quality entrants—this is shifting the competition from low‑price to product‑quality and compliance differentiation.
- Retail and reimbursement pathways (including selective insurer reimbursement and workplace breastfeeding support programs) are beginning to amplify distribution beyond traditional maternity channels.
Strategic implications for 2026 corporate planning
Leaders who use this report convert macro trends into executable choices across five decision domains:
- Portfolio strategy: Invest selectively across wireless, underwire, and hands‑free pumping variants based on margin and brand fit. The market rewards clarity—brands that present a coherent “from pregnancy to pumping” narrative outperform those that treat nursing bras as an afterthought.
- Manufacturing & sourcing: Expect rising emphasis on certified materials and skilled sewing labor. Firms should map supplier certification status, labor specialization, and audit trail to de‑risk scale. Near‑sourcing options matter for speed-to-market of seasonal innovations.
- Pricing & channel mix: Entry-level price points remain important for volume; premium features (pumping compatibility, advanced fabrics) justify higher ASPs and direct-to-consumer channels. Retail assortment decisions should balance trial-driven low-price SKUs and margin-rich premium cores.
- Go-to-market & partnerships: Strategic collaborations—co‑branded bundles with pumping device manufacturers or lactation service providers—accelerate adoption, as seen in recent industry tie‑ups. Retailer and insurer pathways can materially expand addressable reach when paired with clinical validation.
- M&A & innovation scouting: Consolidation and tuck‑ins are already reshaping concentration in parts of the market. Identify targets that provide proprietary hands‑free designs, pump integration, or certification advantages before competition escalates multiples.
What the full PW Consulting report delivers (practical, transaction‑grade)
This market preview accompanies a comprehensive dossier built for implementation. Key operational deliverables included in the full report:
- Proprietary market sizing and demand model (historical 2020–2025 and forecast 2026–2032) with scenario sensitivities to price, channel mix, and hands‑free adoption rates.
- Go‑to‑market playbooks for direct-to-consumer, specialty retail, and mass retail channels, showing SKU rationalization, pricing ladders, and promotion timing to optimize lifetime value.
- Supplier risk maps and a certification tracker focused on material safety (e.g., Oeko‑TEX®), labor skill requirements for inclusive sizing, and supplier lead times by region.
- Segment playbooks—buyer personas for lactating and pregnant cohorts, retailer decision trees, and product feature-set prioritization to maximize conversion.
- Competitive heat maps and M&A candidate shortlists with valuation heuristics tied to portfolio synergies and scale economics.
- Regulatory impact assessment and reimbursement opportunity matrix by major markets—highlighting where partial insurance coverage or workplace programs can be leveraged.
Note: this preview highlights the types of segmentation and models included. The full report contains the granular regional, type, and application splits and underlying datapoints that leaders use in board‑level business cases.
Competitive landscape: profiles and strategic postures
The market’s competitive structure exhibits moderate concentration; three firms account for a meaningful share of branded sales while the top five control a larger portion of specialty revenues. This leaves room for nimble challengers and retailer private labels, but also benefits incumbents that can scale innovation and certification investments quickly.
Representative competitive archetypes analyzed in the report include:
- Specialist innovators — Brands that foreground hands‑free pumping and inclusive sizing, investing in fabric engineering and user‑centric closures. These players are driving product feature expectations in higher‑value channels.
- Heritage intimates — Established bra manufacturers that bring category expertise and distribution scale; their advantage lies in fit engineering and trusted retail relationships.
- Retail/private‑label players — High-volume, value-focused offerings that accelerate category penetration among price‑sensitive buyers; these players pressure conversion economics for all competitors.
We profile specific companies that illustrate these archetypes and their strategic moves—examples include Kindred Bravely (leader in wireless, hands‑free and inclusive sizing innovations), Cake Maternity (full‑coverage and bust‑support specialization), Bravado Designs (seamless everyday comfort and fit focus), Davin & Adley and Momcozy (pump‑integration and hands‑free design leaders), plus European specialists like Anita and Medela who emphasize technical fabrics and clinical compatibility. Recent activity—product launches, award recognitions, and collaborative bundles—signal an acceleration of product differentiation and channel partnerships that will be decisive in 2026.
Supply chain, regulation, and consumer behavior — the operational constraints
Three “noise” factors in the operating environment require immediate attention:
- Labor specialization: Manufacturing nursing bras requires precise cutting and sewing to deliver inclusive fits across size ranges. Labor skill and factory capacity are bottlenecks for rapid line expansions, increasing the value of supplier relationships and manufacturing flexibility.
- Material compliance: Certification standards for maternal apparel are tightening—Oeko‑TEX® and related textile certifications influence supplier selection and time‑to‑market. Brands that pre‑certify fabrics reduce downstream compliance costs and retailer objections.
- Consumer shifts: Wireless and hands‑free pumping styles are moving from trend to expectation in several leading markets. Pricing remains bifurcated: value SKUs drive trial, while advanced features command premium pricing. Reimbursement and workplace support programs are early amplifiers of demand in select geographies.
Recommended 90‑/180‑day roadmap for 2026
- 30 days: Conduct a rapid supplier certification audit and prioritize fabrics that meet Oeko‑TEX® and quick‑dry specifications; identify at least two near‑sourcing options for pilot SKUs.
- 90 days: Validate two pilot SKUs—one wireless hands‑free and one value everyday style—with controlled retail and DTC channels; run A/B pricing and shopper experience tests linked to conversion and returns metrics.
- 180 days: Finalize channel mix guided by pilot economics, secure strategic partnership(s) with lactation or pump manufacturers for bundled offers, and prepare a 12‑month product roadmap emphasizing certification lead times and inventory cadence.
Why PW Consulting’s study accelerates your 2026 decisions
Executives tell us they need three things to move fast: credible market sizing, actionable operational playbooks, and targeted competitive intelligence tied to transaction opportunities. This study delivers all three. It translates macro momentum (baseline market size and 8.1% CAGR) into executable next steps and measurable KPIs—without overwhelming readers with raw micro‑splits in this preview. The full report contains the segmentation, price‑band models, and competitive benchmarking necessary to build investment cases, product roadmaps, and M&A screens for 2026.
For senior leaders planning product launches, channel expansion, or M&A activity in 2026, the study provides the data, scenarios, and operational tools to convert market growth into sustainable margin and market share. Access the complete report to unlock the detailed regional and application breakdowns, SKU-level demand curves, and candidate lists that underpin our recommendations.
For detailed analysis of this topic, please visit the official page: Nursing Bras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Kiosk Market 2026: A Strategic Preview for Enterprise Decision‑Makers
As enterprises plan capital allocations and channel strategies for 2026, kiosks have moved from experimental add‑ons to mission‑critical infrastructure across retail, financial services, hospitality and public services. This preview synthesizes the strategic implications of PW Consulting’s new Kiosk Market study — highlighting growth dynamics, competitive posture, technology inflection points and procurement playbooks — while withholding detailed segment tables to encourage direct engagement with the full research.
Kiosk Market
Why this study matters for 2026 decision cycles
-
Timing: Our base year is 2025 and the forecast window runs through 2032 — aligning with most three‑to‑five year corporate investment plans and multi‑year vendor contracts.
Kiosk Market -
Scale & momentum: The global kiosk market is on a steep growth trajectory, registering meaningful expansion in the historical 2020–2025 window and entering a robust forecast period at a compound annual growth rate of 15.6%.
Kiosk Market -
Concentration dynamics: The market exhibits moderate concentration among the top vendors (CR3 ≈ 60%, CR5 ≈ 65%), which shapes partner selection, bargaining power and M&A playbooks for enterprise buyers and incumbents alike.
-
Decision‑grade outputs: The full report translates market dynamics into procurement tools — supplier scorecards, TCO models, integration checklists and a phased roll‑out template — designed to reduce implementation risk and speed time‑to‑value.
Market trajectory: what the headline numbers tell you
After a period of steady adoption, the kiosk market reached a pivotal inflection in 2025. From that base, our forecast sees sustained acceleration through 2032, driven by a combination of software‑led services, hardened hardware, and expanded use cases. Put simply: the market that many organizations still categorize as “adjacent” to core commerce and service channels is set to become a primary touchpoint for customer experience, revenue capture and operational automation.
For strategists, the headline metrics matter because they convert abstract opportunity into budgetary expectations: the market’s size in 2025 provides the starting ledger for modelled ROI; the 15.6% CAGR underpins scenario planning for adoption, and 2032 projections anchor long‑dated vendor commitments and internal capability roadmaps.
Key growth vectors and business implications
-
Software as differentiation: Hardware commoditization pressures mean winners will be judged by software ecosystems — payment orchestration, identity handling, analytics and verticalized UX. Enterprises should foreground API openness and lifecycle update policies during procurement.
-
Accessibility & compliance as a baseline: Accessibility features are moving from nice‑to‑have to table stakes. Recent product launches emphasize vision, mobility and hearing accommodations; expect accessibility to be an evaluation filter for procurement and a regulatory touchpoint for public contracts.
-
Edge reliability: Hardened processing units and industrial‑grade designs are reducing field failures and service calls. Buying specifications should now include mean time between failure (MTBF) targets and verified field telemetry metrics.
-
Contactless & PCI: Payment flows are evolving rapidly — contactless acceptance, tokenization and "PIN on Glass" standards are reshaping hardware and certification requirements. Enterprises must align kiosk payment architecture with PCI guidance and vendor roadmaps.
-
Managed services tilt: Given the concentration of deployments and the cost of distributed maintenance, managed service models (hardware + software + monitoring) are becoming financially attractive for large rollouts.
Competitive landscape: who matters and how they compete
The market’s mid‑to‑high consolidation means enterprises face a manageable set of strategic vendor archetypes. Our analysis highlights a spectrum from turnkey integrators to component specialists — each carrying different risk profiles for scale, customization and long‑term support.
-
KIOSK Information Systems (Phoenix, AZ): Strength lies in end‑to‑end deployment capabilities — design, manufacture, monitoring and nationwide support. Recent partnerships and product series emphasize ergonomic designs and ruggedized compute, signaling a push to reduce the “digital front‑door” reliability crisis that previously elevated total cost of ownership.
-
Elo Touch Solutions (Milpitas, CA): A recognizable leader in touch hardware, Elo’s footprint in retail, QSR and healthcare underscores a hardware+UX play. Buyers that prioritize certified touch performance and vertical UX templates should include Elo in shortlists.
-
LG Electronics: With Gen‑2 accessible self‑ordering kiosks, LG is positioning accessibility and human‑centered design as a differentiator — attractive for large retailers and public sector deployments that require inclusive interfaces.
-
Diebold Nixdorf & NCR Corporation: Both companies bridge enterprise banking and retail ecosystems with IoT/cloud management and AI‑enhanced self‑service. They are natural partners for organizations seeking tightly integrated payments, cash handling (where applicable), and omnichannel continuity.
-
Specialists & regional manufacturers (Olea, Acrelec, Meridian, ZIVELO, among others): These vendors offer deep verticalization (QSR, museums, government) and custom engineering — ideal for clients that need differentiation in either form factor or integration depth.
-
Component and compute suppliers (AOPEN, Posiflex, Pyramid Computer): They underpin reliability at the edge; enterprises should assess the compute architecture, thermal management and lifecycle availability when approving platforms for rollouts.
Strategic takeaway: mix tier‑1 partners for scale and managed services with niche integrators for vertical differentiation. Contract structures should protect against component obsolescence and include telemetry access for performance benchmarking.
Regulatory & supply‑chain forces to watch in 2026
-
Semiconductor and component tariffs: Tariff movements in 2026 increased build costs and operating expenses for hardware. Buyers must model sensitivity to component price volatility and consider multi‑sourced BOM strategies or longer‑term supplier agreements.
-
Network modernization rules: Recent regulatory moves have reduced some burdens on broadband modernization, easing connectivity upgrades for kiosks. This can speed deployment timelines for distributed kiosks that rely on higher bandwidth or low‑latency links.
-
Data center and infrastructure levies: Certain regional policies introduce new cost considerations for hosting and edge services. Enterprises should review cloud vs. on‑prem cost comparisons with levy scenarios baked into TCO models.
-
Payment standards & certification: Emerging interpretations of "PIN on Glass" and contactless payment standards require early coordination between hardware vendors, payment processors and integrators to avoid retrofit costs.
Operational playbook: five actions for enterprise leaders
-
Start with a service‑led TCO, not just a hardware price. Include uptime SLAs, spare parts logistics, and software licensing cadence.
-
Procure for software portability: require modular stacks, containerized apps or well‑documented APIs to reduce vendor lock‑in and enable future features without full hardware replacements.
-
Mandate accessibility and payments compliance up front; make certification milestones payment triggers in vendor contracts.
-
Plan a two‑stage roll‑out: pilot for reliability and UX metrics, then scale using telemetry‑driven site selection — this reduces the risk of widespread field failures and accelerates learning loops.
-
Use market concentration to negotiate bundled services (installation, monitoring, spare pool) with top vendors while maintaining at least one alternative supplier for critical components.
What the full PW Consulting report delivers
The complete study is structured to move from insight to execution. Highlights include:
-
Market sizing and forecast model (2026–2032) with scenario sensitivity analyses informed by component cost curves and regulatory scenarios.
-
Competitive scorecards mapping product breadth, vertical specialization, service capabilities and platform openness for the leading vendors.
-
Procurement playbook: RFP templates, KPI matrices, warranty and spares negotiations checklist, and a vendor transition playbook for phased replacements.
-
Operational risk register and mitigation strategies covering supply‑chain shocks, certification delays and field reliability events.
-
TCO and ROI workbooks that integrate capital, operating, connectivity and service costs — with adjustable levers for tariffs, levies and service models.
-
Implementation blueprints for common enterprise use cases (retail self‑checkout, QSR self‑ordering, banking kiosks, public access terminals) with staged KPIs for pilot and scale phases.
Note: this preview intentionally omits granular regional and application share tables and detailed vendor revenue splits to preserve the report’s strategic edge. The full datasets, interactive models and supplier scorecards are available in the complete PW Consulting Kiosk Market release.
Final counsel
By 2026, kiosks are no longer experimental endpoints; they are strategic touchpoints that influence sales conversion, reduce operating costs, and extend service availability. The macro indicators — a strong post‑2025 base and a high‑teens CAGR — signal both urgency and opportunity. Enterprises that move from ad hoc pilots to structured procurement and managed services strategies will capture disproportionate benefits. PW Consulting’s full Kiosk Market report supplies the playbooks, models and vendor intelligence to convert that opportunity into repeatable, measurable outcomes.
For detailed analysis of this topic, please visit the official page: Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Films Market to Grow at 7.1% CAGR Through 2032
By pmarketresearch, 2026-07-09
Optical Films Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing on the optical films market that translates technical market intelligence into boardroom-ready actions for 2026. This preview highlights the structural drivers, competitive dynamics, and near-term strategic levers that will determine winners and laggards across display OEMs, advanced materials suppliers, and tiered component manufacturers. It intentionally demonstrates analytical depth while withholding granular segmentation tables and proprietary model outputs — the latter are available in the full report for subscribers.
Optical Films Market
Market trajectory and strategic context
The optical films market has shown resilient expansion through the post-pandemic recovery period and is on a steady growth path into the next decade. Using 2025 as our base year, the market is valued in the mid-hundreds of millions (USD, revenue basis) and is forecast to grow at a compound annual growth rate (CAGR) of 7.1% over the 2026–2032 forecast window. This trajectory reflects a convergence of display innovation (flexible OLEDs, mini-LED and micro-LED backlights, AR/ HUD integration), increased per-unit complexity in consumer devices, and rising content and safety requirements in automotive and industrial displays.
Optical Films Market
Historical performance through 2020–2025 demonstrates both the resilience and volatility of this sector. Supply-side shocks and raw-material swings depressed margins intermittently, while product innovation and recycling mandates have opened higher-margin, differentiated opportunities. For 2026, executives must read this as a market in which steady top-line expansion coexists with heightened operational and regulatory risks — a classic environment where strategy execution and supply-chain choices trump static market-share plays.
Optical Films Market
What is changing now — five dynamics to watch
-
Technology-driven demand composition: Display manufacturers are increasing requirements for thinner, higher-transmittance, and multi-functional films (e.g., polarizers integrated with brightness enhancement or anti-reflection properties). Novel form factors (foldables, rollables) are accelerating adoption of ultra-thin and flexible optical films.
-
Sustainability and regulatory pressure: Recyclable and low-environmental-impact chemistries are rapidly moving from “nice-to-have” to procurement prerequisites for major OEMs. Suppliers that can demonstrate circularity and reduced life-cycle impact will secure preferential sourcing and command premium pricing.
-
Supply-chain localization and capacity shifts: Manufacturers are responding to labor cost volatility, material shortages, and tariff uncertainty by selectively localizing production and reconfiguring inventory strategies. Recent greenfield expansions in Asia and targeted capacity upgrades in Korea and Japan create regional capacity pockets that change lead-time economics.
-
Tariff and trade-policy tail risks: Specialty chemicals used in film production face variable export controls and tariffs. These policies can rapidly reconfigure competitive advantages among global suppliers and alter sourcing decisions for display OEMs.
-
Automotive and AR use-cases scaling: Head-up displays, in-cabin infotainment, and augmented-reality overlays are driving bespoke film requirements (optical clarity, polarization control, durability). Co-development agreements between chemical suppliers and automotive OEMs are emerging as strategic anchors.
Competitive landscape — what the market structure means for 2026 moves
The market is moderately concentrated among several global players, with a handful of firms capturing a material share of advanced optical film demand. That concentration creates both supplier power and opportunity: leading players can invest in specialized R&D, while mid-tier suppliers can carve resilient niches through partnerships and tailored product stacks.
-
3M Company — continues to push ultra-thin polarizers and flexible-film innovation tailored to next-gen OLED form factors. Recent product introductions signal an emphasis on extending portfolio depth for foldable and flexible devices.
-
LG Chem — positions itself on sustainable materials, launching recyclable optical film families that meet increasingly exacting OEM sustainability requirements. This is a defensive and offensive play: defend existing relationships while opening new procurement pathways where ESG is a criterion.
-
Samsung SDI — integrates display-facing film capabilities with panel technologies, leveraging close OEM relationships to co-develop film composites for both LCD and OLED stacks.
-
Zeon, Toray, Nitto, Toyobo — these specialists are focused on high-transmittance substrates, low-haze films, and material science upgrades for touch and polarizer stacks. Their depth in polymer chemistry and substrate processing is a key competitive barrier.
-
Eastman Chemical — recently expanded manufacturing capacity in Asia, which materially alters the cost and lead-time calculus in certain regional supply chains.
Recent industry actions — a new ultra-thin polarizer launch, capacity expansions in Asia, and OEM-supplier partnerships for automotive HUD/AR — underscore a bifurcation: larger suppliers are investing in scale and premium innovation; specialist firms are protecting margin via targeted material differentiation and collaboration with OEMs.
Practical contents — what the full PW Consulting report delivers
The full study offers executive-ready, operational guidance designed for 2026 planning cycles. Highlights include:
-
Robust market-sizing and forecast model (base year 2025; 2026–2032 forecasts) with scenario layers for technology adoption, trade-policy shocks, and raw-material price regimes.
-
Competitive benchmarking with strategic profiles for each major supplier, innovation roadmaps, and capability heatmaps to identify partnership and acquisition targets.
-
Supply-chain resilience playbook: a prioritized set of actions covering capacity localization, dual-sourcing, strategic inventory sizing, and contract structures to mitigate tariff and raw-material volatility.
-
Commercial go-to-market playbooks for suppliers and OEMs: tiered pricing strategies, co-development contracting templates, procurement scorecards, and channel optimization guidance.
-
Capex and ROI toolkits: sensitivity matrices and break-even analyses for greenfield lines, product conversion investments, and recycling-enhancement retrofits.
-
Regulatory and compliance checklist tailored to chemical export controls and environmental mandates, with recommended mitigation steps and timeline impact assessments.
-
Investor and M&A intelligence: target screening criteria, valuation benchmarks, and post-merger integration risks specific to optical-film technology and production footprints.
Strategic recommendations for 2026 corporate planning
For boards and C-level teams, the following strategic priorities should be operationalized in 2026 planning cycles to capture upside and insulate downside risk.
-
Prioritize differentiated product roadmaps: Invest in ultra-thin, multifunctional films and recyclable chemistries. Incremental manufacturing efficiency is necessary but insufficient — differentiation will drive margin expansion.
-
Lock in OEM co-development partnerships: Move from transactional sales to integrated development agreements with major panel and device manufacturers to secure long-term demand visibility and co-fund innovation risk.
-
Reassess manufacturing footprint defensively: Use scenario modeling to determine which assets to localize, expand, or decommission — prioritize proximity to strategic OEMs and access to stable input streams rather than lowest labor cost alone.
-
Hedge raw-material and tariff exposure: Deploy commodity hedging where possible, negotiate long-term supply agreements with pricing collars, and structure sales contracts to share tariff risk with customers in clearly defined triggers.
-
Pursue bolt-on M&A and strategic alliances: Acquire niche material innovators or processing specialists to shorten time-to-market for next-generation films. Target assets that plug directly into existing supply relationships with panel OEMs.
-
Embed sustainability into procurement and product specification: Make recyclability and end-of-life processing part of your product spec for new contracts; this reduces future retrofit costs and strengthens negotiation positions with ESG-focused OEMs.
Decision triggers and KPIs to include in 2026 execution plans
-
Volume and revenue mix against scenario buckets (baseline, upside, downside) for product families tied to flexible OLEDs and automotive AR.
-
Gross margin differential from recycled/eco-friendly product lines versus legacy films; milestone-based R&D expenditure tracking.
-
Weighted lead-time and fill-rate metrics across primary production nodes to trigger capacity shifts or inventory builds.
-
Tariff exposure quantified as a percentage of cost of goods sold, with defined contractual triggers for price pass-through or mitigation actions.
Closing — the strategic value of this research for 2026
For executives planning capital allocation, product strategy, or M&A in 2026, this market represents a growth opportunity tempered by operational and policy risk. The sector’s 7.1% projected CAGR and the mid-hundreds million USD market base (2025) suggest healthy expansion, but realizing attractive returns requires precision in technology roadmaps, supply-chain positioning, and regulatory strategy. PW Consulting’s full Optical Films Market report supplies the models, scenario analyses, and playbooks that translate market forecasts into executable corporate strategy — enabling decision-makers to prioritize investments, secure long-term OEM relationships, and hedge the structural risks that will define 2026 outcomes.
To access the complete dataset, granular regional and application segmentation, and downloadable decision-support models, please consult the full PW Consulting report online. The comprehensive package contains appendices with vendor scorecards, capex calculators, and contract templates not published in this preview.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: WiFi Modules Market to Reach USD 886 Million by 2032 at 9.2% CAGR
By pmarketresearch, 2026-07-09
WiFi Modules Market — PW Consulting Strategic Preview for 2026 Decisions
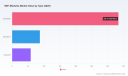
As connectivity becomes the invisible nervous system of industry, commerce, and the consumer experience, WiFi modules are at the center of a strategic inflection for hardware-first businesses. PW Consulting’s latest market study places the global WiFi modules market at USD 480 million in the base year (2025), having expanded from roughly USD 310 million in 2020. Our forward-looking model—anchored in device adoption curves, chipset roadmaps, and realistic supply-side constraints—projects a compound annual growth rate (CAGR) of 9.2% through the 2026–2032 forecast horizon, taking the market toward an expected approximately USD 886 million by 2032. This preview explains why the study matters to corporate leaders in 2026 and how it converts market observation into actionable strategy—while reserving the detailed segment tables and competitive scorecards to the full report.
WiFi Modules Market
Why this study matters for 2026 strategic decisions
-
Timing: 2026 is a bifurcation year. Chipset suppliers are transitioning to new IP blocks (driven by WiFi 7 and low-power LPWAN hybrids), while end markets—consumer, smart home, industrial, and automotive—are evolving different cadence and margin expectations. Our study quantifies the systemic impacts of that transition on design cycles, procurement budgets, and certification timelines.
WiFi Modules Market -
Risk management: Recent geopolitical and regulatory interventions have materially altered wafer, memory, and specialized substrate availability. Companies that use the right scenario-based procurement and inventory playbooks will avoid multi-quarter product delays; the report’s supply-chain simulations translate macro shocks into expected lead-time and cost delta scenarios.
WiFi Modules Market -
Portfolio positioning: With an aggregate market growing at ~9.2% annually, the strategic choice is between scale (volume-led modules for mass consumer IoT) and differentiation (industrial-grade, pre-certified, or multi-radio combo modules). The study provides the decision frameworks needed to prioritize R&D, partnerships, and commercial investments under budget constraints.
Market trajectory — evidence, not guesswork
The market’s historical expansion from about USD 310 million in 2020 to USD 480 million in 2025 reflects both unit-demand growth and rising ASPs for advanced module classes. Our 2026 baseline sits modestly above 2025, consistent with continued OEM replenishment and early commercial deployments of WiFi 7-capable modules. By the early 2030s the market undergoes another structural shift as edge-AI enablement and new regulatory compliance requirements reshape module specs and certification costs. These dynamics—captured in our time-series model—allow finance, product, and procurement teams to stress-test three distinct growth scenarios (conservative, base, and accelerated) and map P&L and cash-flow outcomes to product roadmaps.
What’s in the report — practical outputs for leaders
-
Market sizing and forecast: A reproducible model spanning 2020–2032 with transparent assumptions and sensitivity levers for pricing, adoption, and supply constraints.
-
Go-to-market playbooks: Actionable steps for suppliers and OEMs for cost-to-serve optimization, channel selection, and certification acceleration (including recommended timelines to avoid first-mover compliance penalties).
-
Supplier risk matrix and procurement tactics: Ranked supplier archetypes, dual-sourcing templates, and inventory hedging scenarios calibrated to lead-time shocks observed in early 2026.
-
Product and platform strategy guidance: Decision trees that help R&D and product teams choose between embedded, standalone, and integrated architectures depending on margin targets, time-to-market, and field-service economics.
-
Regulation and raw-material impact analysis: Scenario maps that translate tariff, export-control, and critical-mineral licensing actions into component price and availability outcomes at the module level.
-
Peer and M&A intelligence: A curated shortlist of potential acquisition targets and partnership candidates with high strategic fit across three buyer archetypes (scale-seeker, vertical-specialist, and platform-expander).
Competitive landscape — where incumbents and challengers stand
The WiFi modules ecosystem is populated by chipset suppliers, module manufacturers, and system integrators. Market concentration is moderate: the top three suppliers account for roughly one-third of market value, and the top five for just over half—indicating room for niche specialists and differentiated entrants while underscoring the importance of scale for global OEMs that require broad certification footprints.
-
Raytac Corporation (Taiwan) — Strengths: pre-certified WiFi/Bluetooth modules and rapid certification cycles. Strategic value: ideal partner for companies prioritizing shortened time-to-market in IoT and industrial segments. Recent product and trade-show activity through early 2026 underscores a push into lower-power, Nordic SoC-based modules and edge-AI showcases.
-
SparkLAN (Taiwan) — Strengths: early mover in WiFi 7 modules and industrial-grade offerings. Strategic value: suppliers building AI PC, automotive, and ruggedized product lines should evaluate SparkLAN for high-throughput, latency-sensitive deployments.
-
Espressif Systems (China) — Strengths: cost-effective, low-power module ecosystems widely adopted in consumer and IoT markets. Strategic value: an attractive option for scale production where unit economics drive platform selection and OTA ecosystems are required.
-
Quectel Wireless Solutions (China) — Strengths: broad combo-module portfolio and industrial certifications. Strategic value: companies seeking integrated cellular-WiFi solutions or WiFi HaLow for long-range IoT should examine Quectel’s roadmap and certification support.
-
Nordic Semiconductor (Norway) — Strengths: SoCs and reference modules used in pre-certified solutions for low-power edge devices. Strategic value: critical supplier for designs where battery life and tight RF integration are non-negotiable.
-
u-blox (Switzerland) — Strengths: compact WiFi and WiFi+BT modules with industrial and medical certifications. Strategic value: vendors in regulated verticals will find u-blox’s validation and quality processes compelling.
-
NXP Semiconductors (Netherlands) — Strengths: SoC platforms and partner ecosystems for certified modules. Strategic value: semiconductor partnerships with NXP can accelerate certification and provide long-term roadmap visibility for OEMs.
-
Semtech (USA), Murata (Japan), Laird Connectivity (USA) — Strengths: complementary roles across wireless subsystems, embedded module leadership, and industrial connectivity. Strategic value: these players are frequent targets for OEMs seeking proven quality, robust supply, and aftermarket support.
Recent developments and market noise — what to watch in 2026
Several market events in late 2025 and 2026 are reshaping supplier selection and go-to-market timing. Notable examples include product announcements and certification milestones by module makers, and macro-level policy shifts that increase supply-chain friction. In particular, we account for the industry’s observed surge in component prices and lead times—driven by AI-related demand—and significant regulatory movements affecting semiconductor trade and critical mineral access. These events are not transient; they materially alter both unit economics and implementation timelines for module-reliant products. The full report translates these occurrences into probabilistic outcomes for product launches, cost-of-goods-sold (COGS) trajectories, and inventory exposure.
Strategic implications — decision playbook for 2026
-
Procurement and supplier strategy: Move from single-source to diversified supply agreements with tiered lead-time SLAs. Use our scenario matrices to calculate the cost of dual-sourcing versus the expected cost of supply disruption across a two-year horizon.
-
Product architecture: For new designs, adopt modular architectures that allow field upgrades (e.g., replaceable radio modules). This reduces obsolescence risk and makes certification more manageable when migrating to newer WiFi standards.
-
Certification as strategic asset: Factor certification timelines and costs into go/no-go gates for all product launches. Pre-certified module selection can shave months off launch cycles—an advantage that often outweighs modest ASP premiums.
-
M&A and partnership targeting: Prioritize acquisitions that fill either a certification gap, supply-chain control point (e.g., antenna or RF front-end), or a vertical channel play that accelerates access to high-value customers.
-
Regulatory hedging: Create a five-point compliance checklist tied to export-control and critical-mineral risk. The checklist in our report provides immediate steps for legal and procurement teams to lower exposure to sudden trade-policy shifts.
Concluding perspective
The WiFi modules market is maturing into a bifurcated landscape: high-volume, price-sensitive modules for consumer IoT on one hand; and differentiated, certification-heavy modules for industrial, medical, and automotive segments on the other. With a market expanding from roughly USD 310 million in 2020 to USD 480 million in 2025 and an expected CAGR of ~9.2% through 2032, companies that prepare today—by locking in supplier relationships, rethinking architecture, and integrating regulatory risk into their roadmaps—will convert market growth into sustainable profit pools. PW Consulting’s full report contains the detailed segment breakdowns, supplier scorecards, and the operational templates required to execute these strategies. For decision-makers planning 2026 budgets and roadmaps, the study is a practical guide: it reduces uncertainty, quantifies trade-offs, and translates industry noise into executable actions.
Next steps
Access the full PW Consulting WiFi Modules Market Report to unlock the proprietary segment tables, scenario models, supplier scoring, and downloadable playbooks that underpin the guidance summarized above. The full document is designed as an operational toolkit for product leaders, procurement teams, and corporate strategists who must make high-consequence choices in 2026.
For detailed analysis of this topic, please visit the official page: WiFi Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Construction PM Software Set for 13.82% CAGR Through 2032
By pmarketresearch, 2026-07-09
Construction Project Management Software Market — Strategic Preview for 2026 Decision-Makers
As construction organizations confront accelerating complexity—distributed teams, tighter regulatory oversight, and relentless margin pressure—the software stack that coordinates projects has moved from “nice to have” to mission critical. PW Consulting’s latest market study, anchored on a 2025 base year and projecting through 2032, quantifies this shift and translates it into actionable choices for executives preparing 2026 budgets, procurement roadmaps, and M&A agendas.
Construction Project Management Software Market
Why this study matters for 2026
-
A rapidly expanding opportunity. The market for construction project management software is no longer nascent: having grown steadily across the 2020–2025 period, it is forecast to expand at a compound annual growth rate of approximately 13.82% over the 2026–2032 horizon. Our topline projections show a marked step-up in absolute scale through the forecast window, driven by digital transformation programs, regulatory mandates for digital documentation, and a wave of cloud and AI-enabled product enhancements.
Construction Project Management Software Market -
Strategic timing. For boards and C-suite teams planning 2026 spend, the research identifies inflection points where incremental investment in project management platforms delivers outsized returns: reducing rework from design clashes, shortening approval cycles on change orders, and improving field-to-office cash conversion. The value calculus in 2026 is less about ‘if’ to adopt and more about ‘how aggressively’ to standardize on integrated toolchains.
Construction Project Management Software Market -
Decision-useful framing. Rather than a static vendor scorecard, the study frames supplier selection and investment through practical scenarios (greenfield digital transformation, brownfield incremental upgrades, and bolt-on acquisitions). Each scenario maps to expected timeline, risk profile, and ROI thresholds relevant to 2026 capital planning cycles.
Market trajectory — a data-driven narrative
PW Consulting’s model draws on historical observations from 2020–2025 and a scenario-rich forecasting engine for 2026–2032. The result: a clear trajectory from a mid-market footprint in 2025 toward a materially larger opportunity by the early 2030s. That growth is not uniform—our qualitative analysis identifies pockets of accelerated adoption (notably projects with mandated BIM or sophisticated sustainability reporting) alongside slower-moving segments where legacy workflows and client procurement constraints persist. Importantly, the forecast recognizes the monetization potential of adjacent capabilities—AI-driven schedule risk analytics, integrated safety and compliance modules, and digital twin-enabled lifecycle services—that are driving incremental vendor revenue beyond basic project controls.
What the report contains — operationally relevant deliverables
-
Executive playbooks: concise, role-specific recommendations for CIOs, heads of construction, and procurement leads, including sequencing of capabilities to prioritize in 2026 (document control, RFI/change management automation, field mobility, and real-time schedule-risk dashboards).
-
Investment-grade forecasting: topline and scenario forecasts from 2026–2032, with transparent assumptions and sensitivity testing for input variables such as cloud migration rates, AI feature adoption, and public-sector BIM mandates.
-
Vendor benchmarking toolkit: an assessment framework that combines functional capability, deployment flexibility, integration posture, and go-to-market strength—designed to be used directly in vendor selection RFPs or due diligence checklists.
-
Implementation playbooks and ROI calculators: practical templates for pilot-to-scale sequencing, resource plans, and short/medium-term benefits realization metrics tailored to contractor, owner, and engineer/operator models.
-
Regulatory and compliance mapper: distilled implications of BIM mandates, safety training requirements, and public procurement rules that matter for software scope and contract obligations.
Competitive landscape — synthesis and strategic implications
The vendor ecosystem blends global software platforms, specialist construction cloud players, and ERP-focused incumbents. Market concentration metrics indicate a moderate level of consolidation: the leading three vendors account for a meaningful portion of vendor revenue, with the top five widening that footprint further. This structure creates a dual dynamic: sizable incumbents can leverage integrated suites and enterprise sales motion, while specialist vendors exploit vertical depth and agility to win niche use-cases.
-
Procore Technologies: A cloud-native platform with end-to-end construction workflows. Its strengths lie in mobile field execution, document control, and a broad partner ecosystem. For 2026 strategy, Procore remains a benchmark for cloud-first deployments and wide-scale contractor adoption.
-
Autodesk (Construction): Leveraging BIM and design-to-construction continuity, Autodesk’s offering positions well where architectural and engineering workflows must remain tightly coupled to execution. For public infrastructure and projects with strict digital delivery mandates, Autodesk’s integrated BIM advantage is material.
-
Bentley Systems: Strong in infrastructure and 4D planning with digital twin capabilities. Bentley’s positioning favors large civil and infrastructure projects that value high-fidelity modeling and lifecycle asset management.
-
Trimble: Focused on field-to-office data capture and resource tracking. Trimble’s product suite is attractive for firms that prioritize geospatial accuracy and integrated field hardware/software workflows.
-
Sage Group: Traditionally an accounting and ERP specialist that has extended into construction lifecycle management. Sage is relevant for organizations seeking tighter financial controls and profitability tracking embedded in project software.
-
Buildertrend, CMiC, Jonas: These vendors illustrate divergent go-to-market strategies—Buildertrend targets residential and smaller commercial builders with cloud simplicity, CMiC and Jonas emphasize ERP-grade project accounting and enterprise continuity for larger contractors.
Recent product moves in 2026—ranging from document workflow upgrades to mobile releases—underscore the market’s practical focus. Vendor updates in the first half of 2026 emphasize better PDF/document handling, improved RFI/change order workflows, and mobile experience refinements—features that directly reduce day-to-day friction in contractor operations. These incremental advancements are meaningful because they accelerate user adoption and shorten payback periods for deployments.
Technology and regulatory dynamics shaping 2026 choices
-
BIM and procurement: Regulatory regimes in several jurisdictions now mandate BIM or equivalent digital collaboration on many public projects. This continues to push buyers toward platforms that can demonstrate clash detection, versioned documentation, and audit-ready records.
-
Safety and compliance integration: Training and certification requirements—such as OSHA and national site management standards—make safety tracking and workforce credentialing an operational prerequisite. Platforms that incorporate compliance workflows reduce administrative overhead and contractual risk.
-
AI and predictive analytics: AI adoption has moved from experimentation to embedded functionality; a meaningful share of platforms already shipped AI-driven analytics for schedule and cost risk by 2025. In 2026, buyers will evaluate AI not as an add-on but as a differential factor for real-time decision support.
-
Cloud-first economics: Cloud adoption continues to be the dominant deployment approach because it supports distributed teams, rapid feature delivery, and integration with other enterprise systems. Expect cloud-native offerings to accelerate product innovation and partner integrations in 2026.
Implications for investment, M&A, and procurement
For investors and corporate development teams, the combination of solid CAGR dynamics and moderate market concentration suggests two enduring strategies: (1) bolt-on acquisitions to fill capability gaps (AI analytics, compliance modules, field data capture), and (2) roll-up strategies that consolidate niche regional or vertical specialists into broader platform plays. For enterprise procurement teams, the imperative is to adopt a modular roadmap: secure core project controls and document management in the near term, then phase in higher-value components (AI risk engines, digital twin integrations) aligned with measurable KPIs.
How to use the full report in a 2026 planning cycle
-
Use the scenario forecasts to stress-test procurement budgets under different migration timelines and regulatory impact assumptions.
-
Run vendor shortlists through our benchmark framework to prioritize pilots that validate integration, user adoption, and benefits realization within a 6–12 month window.
-
Leverage the implementation playbooks and ROI templates to convert vendor promises into contractual SLAs and milestone-based payments.
Final note — what we intentionally withhold here
This preview shares the strategic conclusions, market trajectory, and vendor implications that matter for 2026 decisions. To preserve the value of the full study as an operational tool, detailed segment-level splits, regional allocations, precise vendor revenue shares by segment, and the complete financial model are available exclusively in the full report. Those datasets power the granular supplier scorecards and the scenario-specific ROI calculators that procurement teams and investors will require to finalize 2026 commitments.
PW Consulting’s Construction Project Management Software Market study is crafted for leaders who must convert market understanding into executable plans. If you are preparing technology budgets, evaluating acquisition targets, or leading a transformation program in 2026, the full report provides the evidence base, templates, and vendor intelligence you will need to move from intent to impact.
For detailed analysis of this topic, please visit the official page: Construction Project Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrostatic Chucks for Wafer Market Poised for 8.45% CAGR through 2032
By pmarketresearch, 2026-07-08
Electrostatic Chucks for Wafer Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As semiconductor nodes compress and fabs push throughput, the electrostatic chuck (ESC) market is entering a sustained growth phase that demands proactive strategic responses. Our latest PW Consulting study, built on a 2020–2025 historical baseline and projecting to 2032, quantifies the sector’s momentum and decodes the operational, supply-chain, and regulatory inflection points that will shape supplier and end‑user strategies in 2026 and beyond. At a compound annual growth rate (CAGR) of 8.45% through the forecasting horizon, the market trajectory underscores both expanding demand and intensifying competitive dynamics. The global market expands notably from the 2025 base year into the 2032 horizon—an outcome that validates investment and reshoring conversations across the value chain.
Electrostatic Chucks for Wafer Market
Why this report matters for 2026 decisions
- Actionable foresight: The report converts macro growth projections into decision-ready scenarios for procurement, R&D prioritization, and capacity investments timed for 2026 capex cycles.
- Risk-informed planning: It overlays supply‑chain fragilities and export/regulatory noise onto demand forecasts to quantify exposure and recommend mitigation measures appropriate for near‑term contracting windows.
- Competitive advantage: By synthesizing technical trends (multi‑zone thermal control, RF‑optimized chucks, AI‑enabled sensing) with market structure metrics, the study helps executives select between organic product development, alliances, and M&A pathways to defend or expand market share.
Market trajectory — what the headline numbers reveal
Using 2025 as a base year, the ESC market exhibits a clear upward trajectory through 2032. Historical market development between 2020 and 2025 shows steady maturation, while the forecast period captures accelerated adoption driven by advanced node requirements and increased localized equipment spending. The reported CAGR of 8.45% reflects both unit demand growth and a premiumization effect as customers adopt high‑value ESC variants (e.g., multi‑zone thermal chucks, RF‑optimized solutions) that command higher average selling prices.
Electrostatic Chucks for Wafer Market
This growth picture is not uniform: technology migration (from legacy nodes to sub‑10nm processes), capacity expansions in leading foundry clusters, and non‑semiconductor usage (MEMS, sensors, specialty fabs) all create differentiated pockets of demand. Our analysis quantifies these dynamics in a way that is immediately usable for capacity planning, but, in line with our 'trailer' approach, detailed subsegment figures are reserved for the full report to ensure maximum commercial utility for subscribers.
Electrostatic Chucks for Wafer Market
Concentration and competitive dynamics
The industry exhibits high concentration among the top suppliers, with the three‑firm concentration and five‑firm concentration indicators signaling a market where scale, IP, and service footprint matter. This structure has strategic implications for pricing power, partnership approaches, and the speed at which new entrants can scale.
- Applied Materials, Inc. — Leveraging multi‑zone thermal control capabilities and recent moves into AI‑enabled wafer handling, Applied Materials is positioning ESCs as integrated subsystems within tool platforms. The firm’s M&A activity signals a push to embed predictive maintenance and process‑aware sensing into the ESC layer.
- Lam Research Corporation — Focused on etch and deposition applications, Lam’s ESC strategy centers on process optimization and tool‑level integration, reinforcing the importance of close OEM‑supplier collaboration for high‑throughput fabs.
- Japanese ceramic specialists (Shinko Electric, Kyocera, NGK, Sumitomo Osaka Cement, TOTO, NTK CERATEC) — These players emphasize materials engineering (e.g., aluminum nitride ceramics, rare earth doping) and production precision, maintaining a competitive edge in manufacturing quality and thermal management.
- Specialized component and regional suppliers (Entegris, II‑VI M Cubed, Calitech, Beijing U‑PRECISION) — These firms compete on niche performance attributes, service proximity to fabs, and cost flexibility, often serving as vital second‑source partners for major tool integrators.
Recent industry moves reinforce these trends: product launches optimized for advanced nodes, acquisitions integrating AI sensors into chuck systems, and partnerships to develop eco‑friendly ceramic solutions—each event illustrates the dual push for technical differentiation and supply resilience.
Supply‑chain and regulatory realities that will shape 2026 playbooks
We identify five interlocking sources of risk that require immediate incorporation into 2026 planning:
- Export controls and licensing complexity: New rules targeting advanced computing items with sophisticated ESC features (for example, systems with many independently controlled temperature zones) mean export licensing is now an integral part of go‑to‑market planning. Firms must integrate compliance and trade remediation costs into tender responses and subcontracting decisions.
- Raw‑material concentration: Key inputs—most notably high‑purity aluminum nitride powder and certain rare‑earth dopants—are concentrated among a few suppliers. The sector has already experienced delivery delays and has been compelled to hold extended safety stocks. Tactical playbooks must include multi‑sourcing, strategic inventory, and supplier development programs.
- Volatility in specialty materials pricing: Quarterly price swings for dopants and engineered ceramics can materially affect margins on high‑performance ESCs. Hedging policies, pass‑through clauses, and cost‑reduction roadmaps must be established before 2026 procurement cycles.
- Localized production incentives: U.S. and EU incentives are accelerating the establishment of near‑fab service hubs and manufacturing footprints. This is a two‑edged sword: proximity unlocks faster service, but it also raises the bar for fixed‑cost investments and drives consolidation among players that can absorb regional setups.
- Geopolitical supply constraints: Technology restrictions affecting cross‑border flows—particularly between the U.S. and China—create uncertainty for companies relying on integrated supply networks. Scenarios range from re‑routing procurement to building duplicate capacity in friendly jurisdictions.
What the PW Consulting report delivers (practical components)
The report is designed to be a practical toolkit for executives and program managers responsible for product roadmap, procurement, and M&A decisions in 2026. Key deliverables include:
- Top‑line and bottom‑line scenario modeling (2026–2032) calibrated to process node adoption curves and fab expansion schedules.
- Supply‑chain heat map highlighting single‑points‑of‑failure for critical materials and optional mitigations (second‑source, inventories, supplier co‑development).
- Regulatory impact assessment that translates current export control and incentive frameworks into commercially relevant constraints and opportunities by geography and product capability.
- Commercial playbooks for OEMs and ESC specialists covering pricing strategy, service‑network design, and aftermarket revenue levers.
- A competitive scorecard benchmarking product features (thermal uniformity, RF compatibility, sensing integration), service reach, and horizontal capabilities such as AI‑enabled predictive maintenance.
- M&A and alliance decision framework that maps capability gaps to likely targets and partnership archetypes—supporting both bolt‑on and platform plays.
How to translate insights into 2026 actions
For executives preparing 2026 budgets, the report suggests a prioritized sequence of actions:
- Immediate (0–6 months): Conduct a supplier concentration audit for critical materials; commence trade‑compliance scenario planning for advanced ESC features; and assess short‑term inventory strategies.
- Near‑term (6–18 months): Validate product roadmaps against node migration timelines; pilot AI‑enabled sensing in controlled lines to validate predictive maintenance ROI; negotiate strategic supply agreements with manufacturing‑grade clauses to lock in quality and lead times.
- Medium‑term (18–36 months): Decide on localized production investments informed by incentive programs; implement near‑fab service hubs where economics and customer proximity justify the cost; or form alliances with local manufacturers to secure market access.
Competitive bets and M&A signals
Given the market concentration and technological premiumization, we see three dominant strategic bets that will differentiate winners in 2026:
- Integration of intelligence: Embedding sensing and analytics into ESCs (as evidenced by recent acquisitions and product launches) yields superior uptime and total cost of ownership narratives for customers.
- Materials leadership: Control over high‑quality ceramics and dopants—either through vertical integration, strategic partnerships, or secured long‑term supply—reduces production variability and shortens qualification cycles.
- Service proximity: Near‑fab servicing and rapid spare availability convert into tangible revenue premiums for tool integrators and ESC specialists alike; investors should expect consolidation to accelerate around these capabilities.
Call to action — what to read next
This preview outlines the contours of a market that is both expanding and becoming more complex. The full PW Consulting report contains the granular segmentation, regional scenario models, detailed supplier matrices, and exact financial forecasts that procurement, product, and corporate development teams will need to craft binding 2026 strategies. We intentionally withhold detailed subsegment and region‑level figures here to preserve the actionable value of that intelligence for subscribers.
For companies preparing capital and operational plans for 2026, the report functions as a strategic playbook: quantify exposure, prioritize mitigations, and align investments with the node and geography‑specific demand signals that will determine who captures premium margins in the coming cycle.
Closing
Electrostatic chucks are no longer a commodity component: they sit at the intersection of materials science, precision manufacturing, and embedded intelligence. The market growth and structural signals highlighted herein make 2026 a pivotal planning year. PW Consulting’s full study equips decision‑makers with the data, risk maps, and playbooks required to convert an industry inflection into competitive advantage—while the accompanying dataset provides the fine‑grained insights necessary to operationalize those choices.
For detailed analysis of this topic, please visit the official page: Electrostatic Chucks for Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tank Cleaning Services Market to Reach USD 14.44 Billion by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-08
Tank Cleaning Service Market — Strategic Preview for 2026 Decision-Making
Executive summary
As companies plan capital allocations and go-to-market moves for 2026, the tank cleaning services sector presents a clear, accessible growth pathway underpinned by steady demand from energy, chemicals, water treatment and industrial manufacturing. Our analysis shows the global market expanding from an estimated USD 9.28 billion in 2025 toward roughly USD 14.44 billion by 2032, implying a mid-single-digit compounded annual growth rate (CAGR) of approximately 6.5% through the forecast window. That trajectory masks important structural shifts — consolidation among established environmental services players, accelerated adoption of automation and robotics in desludging operations, and a tightening regulatory and liability landscape that is reshaping service design and commercial terms.
Tank Cleaning Service Market
Why this research matters for 2026 planning
-
Portfolio allocation: The growth profile and earnings visibility of tank cleaning services make the segment an attractive defensive growth bet for industrial services investors — but returns will depend on operational discipline and margin capture in hazardous- vs. non-hazardous segments.
Tank Cleaning Service Market -
M&A and partnership timing: The market is at an inflection where strategic buyers can either buy scale to win larger industrial and municipal contracts or acquire specialized capability (robotics, PFAS treatment, advanced sludge recovery). Recent large-scale deals signal that scale plus niche capability is being rewarded in valuations.
Tank Cleaning Service Market -
Cost and insurance planning: Rising compliance scrutiny and high-profile safety incidents are increasing the importance of robust risk management — a material contributor to tender evaluation and insurance pricing in 2026 procurement cycles.
Market trajectory — the macro picture
The market’s expansion from the early 2020s into the mid-2020s reflects a combination of steady replacement demand (scheduled cleaning and desludging), episodic large projects (tank decommissioning, remediation), and an increasing share of work driven by environmental compliance and advanced waste treatment requirements. By 2025, global annual industry revenue reached the high single-digit billions (USD 9.28 billion), and the consensus forecast in our model points toward a roughly USD 14.44 billion market by 2032 at an approximate 6.5% CAGR. That pace is sufficient to sustain both organic investment cases and an active M&A market, but not so rapid as to obscure the need for operational rigor.
Key strategic implications for 2026
-
Invest in safe, automated capabilities now — and make them commercial: Robotics, remote monitoring, and online desludging technologies materially reduce confined-space risk and downtime. Companies that can commercialize automation through time-and-motion productivity gains and demonstrable HSE benefits will command premium contract terms in 2026.
-
Prioritize compliance and liability-proofing: Regulators and customers are tightening permit and entry requirements. High-profile enforcement actions — such as a multi-violation OSHA citation tied to failure to perform atmospheric testing inside tanks (and substantial proposed penalties) — illustrate how safety lapses can create existential cost shocks. Buyers and insurers will prefer vendors with documented confined-space programs, third-party certifications, and digital entry-permit systems.
-
Structure M&A to combine scale with specialty: The market exhibits moderate concentration at the top, making scale attractive for national and multinational procurement. However, buyers should layer on specialty capabilities (advanced contaminant management, PFAS solutions, sludge recovery) to protect margins and reduce cyclicality.
-
Design commercial models around total cost of ownership (TCO): Procurement is shifting from low-cost per-job pricing to TCO models that include environmental disposal, remediation risk, downtime, and reputational factors. Service providers must build and sell integrated TCO analyses to win longer-term agreements.
-
Capitalize on environmental tailwinds: Waste treatment and contaminant-specific remediation (notably PFAS and complex hydrocarbons) are driving incremental service spend. Vendors that integrate advanced treatment and recovery — rather than purely focusing on removal and transport — can capture higher-value scopes.
Competitive landscape — who matters and why
The vendor field contains a mix of global environmental services groups, regional specialists, and technology-focused entrants. Market concentration is meaningful but not prohibitive — the top three players control a significant share of industry revenues, and the top five an even larger slice, leaving space for specialized and regional players to outcompete on capability or cost.
-
Veolia — A global environmental services leader with a strategy of capability-led scale. Recent large acquisitions aimed at hazardous waste and advanced contaminant management underscore Veolia’s intent to broaden its North American footprint and advanced treatment capabilities. For corporate buyers, Veolia represents the archetype of the scale-specialist consolidator.
-
Clean Harbors — A principal North American hazardous-waste and industrial services platform. Its integrated model across treatment, transport and disposal is designed to capture end-to-end value on complex tank cleaning projects.
-
Tradebe and National Tank Services — Regional to continental players that blend full-service offerings with niche remediation projects. They are often preferred on contracts where local permitting and rapid response are determinants.
-
Dulsco and Arham Oil — Examples of regionally dominant firms innovating with service delivery models suited to local market dynamics; case in point, Arham Oil’s 2025 nationwide launch of upgraded robotic crude oil tank cleaning services signals growing market acceptance for automation-led service propositions in high-volume markets.
-
Evergreen Industrial Services , Thompson Industrial Services , SWS Environmental Services , and ARKOIL Technologies — Mid-market players that emphasize time-critical shutdown work, industrial cleaning contracts, and specialist technologies. They are potential acquisition targets for scale players or strategic partners for capability augmentation.
Operational and compliance dynamics shaping vendor selection
-
Confined-space safety and atmospheric testing regimes are now table-stakes. Buyers increasingly require documented permit-to-work systems, third-party auditability, and digital logs of atmospheric testing and PPE compliance. Failure to meet these expectations materially increases both bid rejection rates and insurance costs.
-
Environmental performance is pricing power: Disposal pathways, sludge recovery rates, and PFAS handling capabilities influence lifetime contract economics more than marginal cleaning price. Vendors that can demonstrate higher recovery rates and lower disposal liabilities will command longer contracts and higher margins.
-
Workforce and training are competitive differentiators. Skilled operator scarcity is real in many jurisdictions; firms that invest in upskilling, remote-operated platforms and predictive workforce planning will reduce labor cost volatility.
-
Technology and digital enablement are shifting cost structures. Remote monitoring, digital permits, and automated desludging reduce non-productive time and can be monetized through performance-based contracting.
What the full report delivers — an operational playbook
The PW Consulting Tank Cleaning Service Market report is structured to support executable decisions in 2026. It combines top-line market sizing and forward-looking scenarios with operational toolkits and commercial templates. Highlights include:
- Robust market-sizing methodology with base-year 2025 calibration and a 2026–2032 forecast scenario set; sensitivity testing for oil price, regulatory tightening, and municipal spend.
- Actionable M&A playbooks: target screening criteria, valuation multiples benchmarking, and integration checklists tailored for both scale buyers and capability acquirers.
- Vendor due-diligence templates and RFP evaluation rubrics that weight safety, environmental treatment capability, and TCO impact.
- Commercial models and sample contract language for performance-based and TCO-oriented deal structures.
- Operational levers: productivity-improvement roadmaps (automation adoption curves, crew productivity KPIs), and CapEx/Opex models for scaling robotics and advanced treatment lines.
- Regulatory and safety compendium: concise summaries of confined-space entry requirements, permit frameworks, and recent enforcement trends to inform compliance budgeting and insurance discussions.
Concrete near-term recommendations for 2026
-
Buyers: Tighten vendor pre-qualification on HSE and advanced treatment credentials; prefer multi-year TCO contracts that shift disposal and remediation risk back to vendors with demonstrated treatment capability.
-
Service providers: Prioritize investments in robotic desludging and online sludge-processing capability that demonstrably reduce confined-space exposure; use pilot projects to build commercial case studies for premium pricing.
-
Investors: Target carve-outs and bolt-on acquisitions that add contaminant-specific treatment or coverage in underpenetrated geographies, but require clear integration plans to capture cross-selling opportunities.
-
Risk managers: Reassess insurance programs and bonding capacity, incorporating recent regulatory actions and penalties into stress-testing models for potential operational lapses.
Concluding perspective — opportunity with discipline
The tank cleaning services market in 2026 offers predictable top-line growth and multiple strategic pathways for value creation — organic specialization, technology-driven productivity, and consolidation-led scale. Yet, the market prize will go to organizations that combine safety-first operational discipline with differentiated technical capability and commercially savvy contract design. Our full report equips executives with the diagnostic data, playbooks, and vendor intelligence needed to act decisively in 2026. For a deep dive into scenario-modeled forecasts, company profiles, and the full competitive dataset, access the complete PW Consulting Tank Cleaning Service Market study.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PhotoMOS Optically Isolated Relay Market to Hit USD 766M by 2032 at 7.5% CAGR — PW Consulting
By pmarketresearch, 2026-07-08
PhotoMOS Optically Isolated Relay Market — A 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a condensed strategic briefing to orient executive decision-making for 2026. This preview synthesizes our full PhotoMOS Optically Isolated Relay Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) to highlight the levers that will determine winners and losers over the next planning cycle. The global market reached USD 463.5 Million in 2025 and, at a compound annual growth rate (CAGR) of 7.5%, is forecast to expand to approximately USD 766 Million by 2032. This momentum makes 2026 a pivotal year to convert market visibility into durable strategic advantage.
PhotoMOS Optically Isolated Relay Market
Why this report matters for 2026 decisions
-
Macroeconomic inflection: Persistent demand from industrial automation, telecommunications rollouts, medical device upgrades, and the accelerating electrification of mobility is creating structurally higher requirements for optically isolated semiconductor relays. Our study translates these demand signals into actionable scenarios for product, supply chain, and commercial strategy.
PhotoMOS Optically Isolated Relay Market -
Cost and supply shocks: A documented rise in raw-material and production costs has compressed margins across the value chain. These pressures force immediate choices around sourcing, product architecture, and pricing—choices with long lead times and cumulative effects on competitiveness.
PhotoMOS Optically Isolated Relay Market -
Competitive positioning window: The market concentration level indicates a competitive field where a small set of established incumbents hold meaningful share, but where product differentiation and thermal/current handling performance still create accessible niches for focused players.
Market trajectory: evidence-based growth, actionable implications
The PhotoMOS optically isolated relay market has demonstrated steady recovery and acceleration through the 2020–2025 historical period, culminating in USD 463.5 Million in 2025. Looking forward, a 7.5% CAGR to 2032 points to a materially larger addressable market: our base-case projects market size to reach roughly USD 766 Million by the end of the forecast window. For executives, these macro figures translate into three clear imperatives:
-
Invest in scalable manufacturing and thermal design now: anticipated volumes will reward early capacity expansion and product designs that lower long-run bill-of-materials and testing costs.
-
Prioritize modular product architectures: design choices that allow a single core die/package to serve multiple voltage/current points reduce time-to-market and mitigate component-cost volatility.
-
Develop go-to-market plays by use case: with multiple end-markets maturing at different paces, targeted commercial strategies (e.g., telecom vs. automotive EV test benches) preserve margin while maximizing penetration.
Demand-side drivers and technological inflection points
-
Automation and higher-frequency switching: Adoption of solid-state switching in factory automation and semiconductor test equipment favors PhotoMOS relays for their reliability and switching characteristics.
-
Telecommunications and 5G/edge infrastructure: As higher-frequency signaling and density increase on baseband and RF boards, demand for low-leakage, stable on-resistance relays rises.
-
Medical and safety-critical devices: Qualification cycles and the need for non-contact switching in diagnostic and therapeutic equipment create demand for variants with rigorous isolation and lifecycle guarantees.
-
Automotive electrification: Automotive and EV segments are not uniform—certain sub-applications require high-temperature operation, extended reliability, and voltage-driven variants tailored for battery-test and power-control use cases.
Supply-side dynamics: margins under pressure, winners defined by supply resilience
Our dynamics analysis reveals material and production cost shocks that are not transitory. Key inputs—such as compound semiconductor substrates—saw a significant cost uptick, which contributed to increased manufacturing complexity and higher energy/labor outlays. Smaller manufacturers have been disproportionally affected by component-cost volatility and rising energy usage in production.
-
Strategic implication — sourcing and design for cost: Firms that secure multi-year supply agreements, diversify substrate sources, or redesign to use lower-cost packaging and alternative materials will see margin recovery sooner.
-
Strategic implication — operational intensity: Investments in energy efficiency, process automation, and localized assembly can mitigate rising production energy use and labor cost inflation.
-
Strategic implication — pricing sophistication: Dynamic pricing that reflects raw-material cycles and differentiated firmware/hardware feature sets will protect margin without sacrificing share in price-sensitive segments.
Competitive landscape — capabilities that matter in 2026
The market exhibits moderate concentration: our CR3 and CR5 metrics indicate that leading vendors hold significant influence but that opportunity remains for targeted challengers. Four archetypal incumbent strategies illustrate the competitive playbook:
-
Legacy broad-portfolio scale — Firms with expansive PhotoMOS/photorelay families leverage variant breadth and application certifications to serve OEMs across automation, medical, and telecom. Depth of SKUs enables tight pairing with customer BOM requirements and reduces switching friction.
-
Application-specialist approach — Some companies concentrate on high-current or high-temperature variants (including automotive-grade and industrial thermal envelopes), capturing premium pricing where qualification barriers are high.
-
Power-relay specialization — Providers that focus on DC power switching for motors, robotics, and vehicle subsystems emphasize isolation ratings and current handling as differentiators, often pairing relays with thermal management solutions.
-
Rapid-innovation entrants — Newer offerings featuring miniaturized packaging, enhanced on-resistance stability, or voltage-driven photorelays have gained traction in niches like semiconductor testers and EV battery systems.
Recent product launches underscore how incumbents are sharpening these plays. For example, a February 2026 introduction of multiple voltage-driven photorelays in a small S-VSON4T package with 135°C operating rating signals an industry move toward higher-temperature automotive and industrial solutions. These developments demonstrate the market premium for thermal robustness and package density—attributes buyers are increasingly demanding.
Strategic recommendations for 2026—what to do in the next 12 months
-
Prioritize product roadmaps by return on qualification: Focus R&D and certification dollars first on variants that unlock the largest long-term OEM contracts (e.g., high-temperature automotive, semiconductor test equipment), then extend to broader-volume SKUs.
-
Lock in supply and hedge input cost exposure: Execute multi-year supply contracts for critical substrates, explore forward-buy programs for key components, and invest in process improvements that reduce substrate dependence.
-
Differentiate through systems-level solutions: Pair PhotoMOS relays with thermal/packaging innovations, diagnostic firmware, or integrated driver modules to move up the value chain and protect margin.
-
Commercial segmentation and channel optimization: Align sales motions with end-market economics—use direct OEM partnerships in high-certification segments and distributor/channel strategies for rapid volume adoption in commoditized applications.
-
M&A and partnerships playbook: Consider tuck-ins that add thermal packaging IP or vertical integration of substrate processing to control cost and improve time-to-market.
What PW Consulting’s full report delivers
Our comprehensive study goes well beyond this preview to provide the operational datasets and decision tools required for 2026 planning:
-
Scenario-based market sizing and demand-supply models (2026–2032) with revenue and unit forecasts under multiple macroeconomic and technology adoption scenarios.
-
Cost-to-serve and BOM-level manufacturing cost models that isolate the impact of substrate, packaging, testing, and energy on unit economics.
-
Competitive benchmark profiles and capability maps for leading vendors, including technology differentiation, patent landscapes, and partnership matrices.
-
Playbooks for product roadmaps, sourcing strategies, pricing tactics, and M&A screening criteria—designed to be directly executable by strategy and product teams.
Note: This preview highlights high-level, decision-relevant findings while intentionally omitting granular segment-level tables and proprietary data points that are available in the complete PW Consulting report. For executives seeking the exact regional, type, and application splits, downloadable datasets, and scenario files to run internal models, the full study provides the necessary depth and export-ready deliverables.
Concluding perspective
The PhotoMOS optically isolated relay market is entering a growth phase where technical nuance, supply-chain resilience, and calibrated go-to-market strategies will determine leadership. The macro trajectory—strong historical growth culminating in a mid-decade base and an estimated 7.5% CAGR through 2032—creates both opportunity and urgency. Organizations that act in 2026 to shore up sourcing, sharpen product differentiation, and align commercial models to end-market economics will capture disproportionate value as the market scales.
To access the full dataset, company profiles, and the executable strategic playbook, please consult PW Consulting’s complete PhotoMOS Optically Isolated Relay Market report via our client portal.
For detailed analysis of this topic, please visit the official page: PhotoMOS Optically Isolated Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rubidium Atomic Clock Market to Reach USD 845.41M by 2032 (7.02% CAGR)
By pmarketresearch, 2026-07-08
Rubidium Atomic Clock Market — Strategic Preview for 2026 Decision-Making
Atomic timing is no longer a niche engineering discipline; it is a strategic enabler across telecommunications, navigation, defense and space systems, and critical infrastructure. Our Rubidium Atomic Clock Market study synthesizes five years of historical performance and a seven-year forward view to deliver a decision-grade perspective for corporate leaders planning in 2026. This preview highlights the study’s strategic value, the market dynamics shaping near-term choices, and the competitive posture of incumbent and emerging suppliers — while reserving the granular segment datapoints for the full report to preserve its commercial utility.
Rubidium Atomic Clock Market
Why this study matters in 2026
-
Clear, investable growth trajectory — The market has expanded from a firmly established base in 2020 and reached an estimated USD 525.0 Million in 2025. Our baseline forecast anticipates continuation of growth into the next planning cycle, reaching roughly USD 574.56 Million in 2026 and accelerating toward an estimated USD 845.41 Million by 2032 at a compound annual growth rate of 7.02% (USD Million basis). For product planners, M&A teams and procurement leaders, those dynamics change how you prioritize R&D, capital allocation and supplier strategies for 2026.
Rubidium Atomic Clock Market -
Decision-focused deliverables — This study is built to be actionable: it combines bottom-up sizing, technology roadmaps, go-to-market playbooks and supplier risk matrices so that boardrooms and program teams can convert market intelligence into executable plans within weeks rather than months.
Rubidium Atomic Clock Market -
Timing-sensitive regulatory and procurement constraints — The market’s growth is tightly coupled to regulatory shifts and procurement cycles (notably in telecom and defense), which makes early alignment on certification, interoperability and sustainability a competitive advantage in 2026.
What the full report delivers (practical, operational content)
-
Robust market model: historical 2020–2025 reconciliation and scenario-driven forecasts for 2026–2032 (base, upside, downside) with sensitivity to price, volume and substitution effects.
-
Go-to-market playbooks tailored by buyer type (telecom OEMs, satellite prime contractors, defense integrators, research institutions) including recommended commercial terms, bundling strategies and aftermarket support models.
-
Competitive benchmarking and product scorecards: performance, SWaP (size, weight, and power), qualification status, mean time between failures (MTBF) estimates, and typical lifecycle costs — presented in a format you can apply directly to supplier selection and RFPs.
-
Technology and R&D roadmap: miniaturization pathways, cell-based rubidium advances, frequency stability improvement levers, and plausible substitution threats across the forecast horizon.
-
Regulatory and certification tracker: a prioritized playbook of compliance activities required by major regulators and defense certification bodies, including energy efficiency and hazardous-substance constraints that affect manufacturing and sourcing.
-
Supply chain heatmaps and resilience playbook: single-source exposures, critical component lead times, sample dual-sourcing strategies, and practical inventory policies for mitigating geopolitical and component shocks.
-
M&A and partner screening: scored lists of potential acquisition or JV targets, with pro forma valuation ranges, integration risk assessment and potential synergies for product line expansion or geographic access.
-
Operational tools: downloadable models (Excel), executive slide decks and a one-week workshop agenda for rapid alignment with senior stakeholders.
Market dynamics and inflection points to track in 2026
-
Demand drivers are diversifying. High-capacity telecom networks (including backhaul and edge synchronization), expanding satellite constellations, defense modernization and critical infrastructure hardening are creating parallel demand streams. These drivers are changing procurement cadences and introducing new timeliness expectations for product qualification and delivery.
-
Miniaturization and cost-per-performance competition. The product development race is focused on reducing size, power and cost while preserving stability. New miniature models introduced across suppliers are beginning to compress price bands and open adjacent applications, but they also increase pressure on legacy unit economics.
-
Regulatory tightening — case in point: a series of updates to radio-frequency, interoperability and defense certification rules (notably in jurisdictions with advanced telecom and defense ecosystems) raise the bar for timing accuracy, interference mitigation and cybersecurity hardening. Environmental and energy-efficiency constraints are increasingly part of procurement specifications, forcing manufacturers to redesign production and to document lifecycle impacts.
-
Concentration with room for disruption. The vendor landscape is consolidated among a handful of established players with specialized capabilities, yet innovation from smaller, focused entrants is capable of reshaping niches if incumbents fail to scale miniaturized, low-cost solutions quickly.
Competitive landscape — strategic posture of core suppliers
The competitive field is occupied by established aerospace and defense suppliers, frequency-specialist manufacturers, semiconductor and systems companies, and high-performance laboratory vendors. A few high-level strategic takes on representative players:
-
Safran Electronics & Defense — A leading global supplier with a comprehensive product family spanning full-size to miniature rubidium clocks. Safran is executing on a product modernization cadence that emphasizes space and defense qualifications and moves to secure long-term prime-supplier positions in sensitive programs.
-
IQD Frequency Products — A frequency specialist with strong capabilities in crystal and oscillator technologies. IQD’s portfolio and manufacturing experience provide a stable platform for incremental innovation in timing modules that are compatible with telecom and industrial integrators.
-
AccuBeat — A supplier focused on ruggedized and miniature oscillators for military and space applications. AccuBeat’s modular approaches and GPS-integrated systems make it an attractive partner for programs requiring hybrid timing solutions.
-
Excelitas Technologies — Known for space-qualified standards and a strong track record in satellite timing products. Excelitas is positioned to win constellation-level supply contracts where flight heritage and qualification depth matter.
-
Frequency Electronics — Focused on high-precision products for defense and space, with digital rubidium systems that appeal to integrators prioritizing software-driven timing control and remote calibration capabilities.
-
Microchip Technology — A strategic entrant from the semiconductor side, pushing miniaturized embedded atomic oscillators that can be integrated into larger avionics and industrial platforms, raising potential for scale if successful.
-
Chengdu Spaceon Electronics — A major domestic producer with advantages in vertical integration for certain end-markets. Their positioning matters for procurement strategies tied to specific geographies or national programs.
-
Stanford Research Systems — Serves laboratory and precision instrument niches with reliable bench-top rubidium standards; important for test, calibration and research workflows rather than mass-deployed systems.
Recent product launches underscore the pace of innovation: several firms released second-generation miniature rubidium clocks and low-cost commercial models in 2025, accelerating the migration of atomic timing into new device classes. These product moves validate the trend toward smaller, lower-power solutions while simultaneously compressing time-to-qualification for network and defense integrators.
Strategic recommendations for executives planning in 2026
-
Prioritize miniaturized, low-power product roadmaps if you compete in telecom, avionics or LEO satellite markets — these segments are most sensitive to SWaP improvements and cost-per-channel economics.
-
Operationalize supplier diversification: define second-source contracts for critical subassemblies and negotiate joint inventory buffers with strategic suppliers to protect against lead-time shocks.
-
Embed regulatory readiness into product development: design to meet evolving frequency-interoperability, cybersecurity and environmental standards from day one to avoid costly retrofits.
-
Invest in aftermarket services and lifecycle monetization: extended warranties, calibration-as-a-service and remote-monitoring can materially improve lifetime margins and customer stickiness.
-
Pursue targeted M&A or partnerships to fill capability gaps quickly — especially where qualification cycles are long and in-house development would delay market entry.
-
Use scenario planning to size contingencies: model the impact of accelerated miniaturization, disruptive cost entrants, and tightening export controls on revenue and margin trajectories through 2032.
How to use this preview and the full study
This preview exists to orient leadership toward the strategic choices that will matter in 2026. The full PW Consulting study contains the granular segmentation, regional analytics, detailed supplier scorecards and executable templates that you will need to implement the recommendations above. If your objective is to (a) align R&D budgets to market windows, (b) structure procurement contracts that mitigate supplier risk, or (c) identify acquisition targets that accelerate route-to-market, the complete dataset and scenario models in the full report are designed to plug directly into your planning cycles.
For confidentiality and commercial reasons, we have intentionally withheld the granular regional and application splits in this preview — those detailed figures, together with unit-price models and downloadable decision tools, are available in the full report and through our advisory engagements.
Next steps
-
Request a tailored briefing: schedule a one-hour executive session where we will run the model on your specific product, region and procurement constraints and deliver a prioritized action plan for 90–180 days.
-
Engage for a rapid supply-chain stress test: a three-week engagement to map critical exposures, test alternative sourcing strategies and provide a remediation playbook.
-
Download the full study and interactive models to unlock the granular segmentation and supplier benchmarking required for tactical execution in 2026.
Timing devices frame the tempo of complex systems. As enterprises calibrate plans for 2026, access to disciplined market intelligence and an operational playbook will be the difference between being a supplier of choice and simply responding to procurement fires. Our full Rubidium Atomic Clock Market study provides that intelligence and the tools to act — contact PW Consulting to continue the conversation and convert this market momentum into measurable competitive advantage.
For detailed analysis of this topic, please visit the official page: Rubidium Atomic Clock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gas Turbine Services to Hit USD 52.7B by 2032 at 9.1% CAGR (2026–2032)
By pmarketresearch, 2026-07-08
Gas Turbine Services Market: A Strategic Lens for 2026 Decision‑Makers
Executive snapshot
As power and industrial end‑users confront simultaneous pressures — decarbonization mandates, fuel‑stack volatility, and constrained aftermarket capacity — the global gas turbine services market is entering a decisive growth phase. Our base‑year assessment (2025) positions the market at approximately USD 28.5 Billion, and the forecast through 2032 shows sustained expansion (CAGR ~9.1%) to roughly USD 52.7 Billion. That trajectory signals a multi‑year window for commercial repositioning: investments in service capability, lifecycle optimization, and strategic partnerships made in 2026 will materially affect competitive standing across the next decade.
Gas Turbine Services Market
Why 2026 matters: a confluence of demand drivers and supply constraints
2026 is not simply another reporting year — it is a pivot. The serviceable fleet is aging in many mature markets while new high‑efficiency units enter commercial operation. Regulators are tightening emissions and safety protocols, and OEMs and independent service providers are racing to monetize retrofits, digital monitoring, and long‑term service agreements. Simultaneously, limited repair capacity for critical rotating components and a skilled labor shortage are extending lead times and raising repair costs. This combination of expanding service demand and constrained supply underpins the market expansion we quantify in this study, and it explains why many players are accelerating strategic moves now rather than later.
Gas Turbine Services Market
Market trajectory and strategic implications
Our historical review (2020–2025) and forward forecast (2026–2032) reveal three practical takeaways for 2026 planning cycles:
Gas Turbine Services Market
- Growth is broad‑based and durable — the market nearly doubles from the mid‑2020s to 2032, reflecting both routine maintenance needs and a surge in upgrade/retrofit activity tied to emissions and fuel‑flexibility requirements.
- Consolidation dynamics are meaningful — the top three firms account for a majority share of aftermarket services and the top five amplify that concentration. Market concentration favors firms that can combine global parts footprint, repair centers, and technology‑enabled service delivery.
- Operational bottlenecks will be value multipliers — organizations that can secure repair network capacity, invest in workforce upskilling, and implement predictive maintenance platforms will extract disproportionate margin and backlog protection.
Industry dynamics shaping 2026 decisions
Several interlocking dynamics will determine winners and losers in 2026 and beyond. These are not abstract; they translate directly to procurement, contracting, and capital allocation choices.
- Regulatory acceleration: Stricter NOx limits and mandatory emissions monitoring are prompting widespread upgrade cycles. Providers offering retrofit pathways — particularly for ammonia slip control and hydrogen‑blend readiness — are seeing elevated demand for engineering, parts, and long‑term performance guarantees.
- Fuel‑flexibility and hydrogen readiness: Hydrogen blending and hydrogen‑ready retrofit programs are moving from pilot projects to commercial contracts in several jurisdictions. Compliance and certification complexity introduces a premium for validated retrofit solutions and managed risk transfer via service agreements.
- Repair capacity and labor supply constraints: Specialist rotor and component repair capacity remains limited, and skilled labor shortages are prolonging lead times. These constraints elevate the value of regional repair hubs, mobile field teams, and strategic acquisitions that expand capacity.
- Contracting evolution: Long‑term service agreements increasingly bundle emissions monitoring, efficiency guarantees, and digital performance optimization — creating recurring revenue streams but also embedding performance and compliance risk.
Competitive landscape — who matters and why
The market is populated by a mix of legacy OEMs, specialist independents, and diversified aftermarket players. Competitive advantage in 2026 will hinge on the ability to combine global service footprint, retrofit engineering, digital diagnostics, and parts availability. Key market participants profiled in our study include:
- Siemens Energy (München): Full lifecycle services with a strong push into hydrogen‑ready retrofits and digital optimization.
- GE Vernova (Atlanta): Depth in HA‑class fleet support, expanding regional repair footprints and demonstrating large operational hours across its fleets.
- Mitsubishi Power (Tokyo): Long‑term service agreements tied to large power projects and integrated aftermarket support for its turbine platforms.
- Solar Turbines (San Diego): Aeroderivative aftermarket specialist with field services and rapid response capabilities.
- Kawasaki Heavy Industries, Ansaldo Energia, Flowserve, Sulzer, and BHEL: Each brings regional strength, niche technical capabilities, or aftermarket scale that matter to buyers seeking diversified service strategies.
Recent strategic moves underscore the competitive tempo: acquisitions to bolster industrial repair capacity, opening of regional repair centers to shorten lead times, major service contracts tied to new HA‑class plants, and hydrogen retrofit contracts that position incumbents for the energy transition. These developments are analyzed in the report not as news bites but as indicators of capability trajectories and likely market responses to capacity shortages and regulatory shifts.
What the PW Consulting report delivers — practical, decision‑grade tools
Our market study is built to support procurement officers, service line leaders, corporate development teams, and asset owners making capital and contractual commitments in 2026. It emphasizes actionable outputs rather than descriptive narrative.
- Quantitative market model: a bottoms‑up revenue model (2020–2032) with scenario runs for retrofit intensity, fuel‑mix adoption, and repair capacity constraints.
- Demand drivers and sensitivity analysis: mapping how emissions regulations, hydrogen blending targets, and labor lead times alter serviceable addressable market size and timing.
- Competitive playbooks: vendor capability matrices, strategic imperatives for OEMs vs independents, and recommended contracting structures for buyers to allocate risk and protect availability.
- Operational benchmarks: lead‑time and pricing guides for common service scopes, turnaround tradeoffs, and spare parts inventory strategies keyed to fleet characteristics.
- M&A and partnership tracker: recent transactions, capability gaps, and acquisition targets that accelerate entry into constrained repair segments or regional footprints.
- Implementation checklists: procurement templates for long‑term service agreements, retrofit deployment roadmaps, and workforce upskilling programs tailored for 2026 execution.
How executives should use this intelligence in 2026
For executives planning capital cycles or negotiating multi‑year service contracts in 2026, the report supplies a practical playbook:
- Prioritize contractual flexibility that balances performance guarantees with supply chain risk sharing. Where repair capacity is constrained, include clear escalation and capacity assurance clauses.
- Invest in staged retrofit and fuel‑flexibility programs. A phased approach to hydrogen readiness and emissions upgrades preserves optionality while meeting near‑term compliance.
- Leverage digital monitoring to convert maintenance spend into predictability. Providers that combine field services with analytics reduce unplanned downtime risk and create differentiation in bids.
- Consider bolt‑on M&A or strategic alliances to secure repair capacity and regional presence. Recent transactions demonstrate how inorganic moves can compress lead times and increase share of wallet with large asset owners.
- Embed workforce strategies into procurement: contractual training obligations, shared apprenticeship programs, and certification pathways reduce the labor risk premium over time.
Limitations and why deeper segmentation analysis matters
Top‑line market growth and concentration metrics are necessary but not sufficient for precise commercial action. Critical decisions — which regions to localize repairs in, which turbine types to prioritize, and how to price retrofit bundles — require the granular segment economics we reserve for the full report. This "preview" is intentionally designed to show the analytical rigor and to surface the strategic questions; the detailed segmental datasets and model inputs are available in the complete study and will materially influence contract structuring and capital allocation choices.
Bottom line: timing, capability, and risk management
2026 offers a strategic inflection point: the market scale and 9.1% projected compound growth create both opportunity and urgency. Organizations that move early to secure repair capacity, formalize retrofit pathways, and reframe service agreements to meet evolving regulatory and performance expectations will capture durable value. Conversely, delay risks longer lead times, premium pricing, and weaker negotiating leverage as capacity tightens further.
Next steps
PW Consulting has prepared a comprehensive dataset, scenario models, vendor profiles, and executable playbooks to support 2026 decision cycles. For executives who need to convert this market trajectory into contracts, capex plans, or M&A strategies, the full report provides the granular segmentation, pricing matrices, and supplier scorecards required to act with confidence. Access details and sample model extracts are available on our web portal.
For detailed analysis of this topic, please visit the official page: Gas Turbine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com