

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: WiFi Modules Market to Reach USD 886 Million by 2032 at 9.2% CAGR

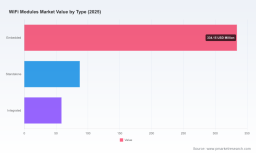
WiFi Modules Market — PW Consulting Strategic Preview for 2026 Decisions
As connectivity becomes the invisible nervous system of industry, commerce, and the consumer experience, WiFi modules are at the center of a strategic inflection for hardware-first businesses. PW Consulting’s latest market study places the global WiFi modules market at USD 480 million in the base year (2025), having expanded from roughly USD 310 million in 2020. Our forward-looking model—anchored in device adoption curves, chipset roadmaps, and realistic supply-side constraints—projects a compound annual growth rate (CAGR) of 9.2% through the 2026–2032 forecast horizon, taking the market toward an expected approximately USD 886 million by 2032. This preview explains why the study matters to corporate leaders in 2026 and how it converts market observation into actionable strategy—while reserving the detailed segment tables and competitive scorecards to the full report.
WiFi Modules Market
Why this study matters for 2026 strategic decisions
-
Timing: 2026 is a bifurcation year. Chipset suppliers are transitioning to new IP blocks (driven by WiFi 7 and low-power LPWAN hybrids), while end markets—consumer, smart home, industrial, and automotive—are evolving different cadence and margin expectations. Our study quantifies the systemic impacts of that transition on design cycles, procurement budgets, and certification timelines.
WiFi Modules Market -
Risk management: Recent geopolitical and regulatory interventions have materially altered wafer, memory, and specialized substrate availability. Companies that use the right scenario-based procurement and inventory playbooks will avoid multi-quarter product delays; the report’s supply-chain simulations translate macro shocks into expected lead-time and cost delta scenarios.
WiFi Modules Market -
Portfolio positioning: With an aggregate market growing at ~9.2% annually, the strategic choice is between scale (volume-led modules for mass consumer IoT) and differentiation (industrial-grade, pre-certified, or multi-radio combo modules). The study provides the decision frameworks needed to prioritize R&D, partnerships, and commercial investments under budget constraints.
Market trajectory — evidence, not guesswork
The market’s historical expansion from about USD 310 million in 2020 to USD 480 million in 2025 reflects both unit-demand growth and rising ASPs for advanced module classes. Our 2026 baseline sits modestly above 2025, consistent with continued OEM replenishment and early commercial deployments of WiFi 7-capable modules. By the early 2030s the market undergoes another structural shift as edge-AI enablement and new regulatory compliance requirements reshape module specs and certification costs. These dynamics—captured in our time-series model—allow finance, product, and procurement teams to stress-test three distinct growth scenarios (conservative, base, and accelerated) and map P&L and cash-flow outcomes to product roadmaps.
What’s in the report — practical outputs for leaders
-
Market sizing and forecast: A reproducible model spanning 2020–2032 with transparent assumptions and sensitivity levers for pricing, adoption, and supply constraints.
-
Go-to-market playbooks: Actionable steps for suppliers and OEMs for cost-to-serve optimization, channel selection, and certification acceleration (including recommended timelines to avoid first-mover compliance penalties).
-
Supplier risk matrix and procurement tactics: Ranked supplier archetypes, dual-sourcing templates, and inventory hedging scenarios calibrated to lead-time shocks observed in early 2026.
-
Product and platform strategy guidance: Decision trees that help R&D and product teams choose between embedded, standalone, and integrated architectures depending on margin targets, time-to-market, and field-service economics.
-
Regulation and raw-material impact analysis: Scenario maps that translate tariff, export-control, and critical-mineral licensing actions into component price and availability outcomes at the module level.
-
Peer and M&A intelligence: A curated shortlist of potential acquisition targets and partnership candidates with high strategic fit across three buyer archetypes (scale-seeker, vertical-specialist, and platform-expander).
Competitive landscape — where incumbents and challengers stand
The WiFi modules ecosystem is populated by chipset suppliers, module manufacturers, and system integrators. Market concentration is moderate: the top three suppliers account for roughly one-third of market value, and the top five for just over half—indicating room for niche specialists and differentiated entrants while underscoring the importance of scale for global OEMs that require broad certification footprints.
-
Raytac Corporation (Taiwan) — Strengths: pre-certified WiFi/Bluetooth modules and rapid certification cycles. Strategic value: ideal partner for companies prioritizing shortened time-to-market in IoT and industrial segments. Recent product and trade-show activity through early 2026 underscores a push into lower-power, Nordic SoC-based modules and edge-AI showcases.
-
SparkLAN (Taiwan) — Strengths: early mover in WiFi 7 modules and industrial-grade offerings. Strategic value: suppliers building AI PC, automotive, and ruggedized product lines should evaluate SparkLAN for high-throughput, latency-sensitive deployments.
-
Espressif Systems (China) — Strengths: cost-effective, low-power module ecosystems widely adopted in consumer and IoT markets. Strategic value: an attractive option for scale production where unit economics drive platform selection and OTA ecosystems are required.
-
Quectel Wireless Solutions (China) — Strengths: broad combo-module portfolio and industrial certifications. Strategic value: companies seeking integrated cellular-WiFi solutions or WiFi HaLow for long-range IoT should examine Quectel’s roadmap and certification support.
-
Nordic Semiconductor (Norway) — Strengths: SoCs and reference modules used in pre-certified solutions for low-power edge devices. Strategic value: critical supplier for designs where battery life and tight RF integration are non-negotiable.
-
u-blox (Switzerland) — Strengths: compact WiFi and WiFi+BT modules with industrial and medical certifications. Strategic value: vendors in regulated verticals will find u-blox’s validation and quality processes compelling.
-
NXP Semiconductors (Netherlands) — Strengths: SoC platforms and partner ecosystems for certified modules. Strategic value: semiconductor partnerships with NXP can accelerate certification and provide long-term roadmap visibility for OEMs.
-
Semtech (USA), Murata (Japan), Laird Connectivity (USA) — Strengths: complementary roles across wireless subsystems, embedded module leadership, and industrial connectivity. Strategic value: these players are frequent targets for OEMs seeking proven quality, robust supply, and aftermarket support.
Recent developments and market noise — what to watch in 2026
Several market events in late 2025 and 2026 are reshaping supplier selection and go-to-market timing. Notable examples include product announcements and certification milestones by module makers, and macro-level policy shifts that increase supply-chain friction. In particular, we account for the industry’s observed surge in component prices and lead times—driven by AI-related demand—and significant regulatory movements affecting semiconductor trade and critical mineral access. These events are not transient; they materially alter both unit economics and implementation timelines for module-reliant products. The full report translates these occurrences into probabilistic outcomes for product launches, cost-of-goods-sold (COGS) trajectories, and inventory exposure.
Strategic implications — decision playbook for 2026
-
Procurement and supplier strategy: Move from single-source to diversified supply agreements with tiered lead-time SLAs. Use our scenario matrices to calculate the cost of dual-sourcing versus the expected cost of supply disruption across a two-year horizon.
-
Product architecture: For new designs, adopt modular architectures that allow field upgrades (e.g., replaceable radio modules). This reduces obsolescence risk and makes certification more manageable when migrating to newer WiFi standards.
-
Certification as strategic asset: Factor certification timelines and costs into go/no-go gates for all product launches. Pre-certified module selection can shave months off launch cycles—an advantage that often outweighs modest ASP premiums.
-
M&A and partnership targeting: Prioritize acquisitions that fill either a certification gap, supply-chain control point (e.g., antenna or RF front-end), or a vertical channel play that accelerates access to high-value customers.
-
Regulatory hedging: Create a five-point compliance checklist tied to export-control and critical-mineral risk. The checklist in our report provides immediate steps for legal and procurement teams to lower exposure to sudden trade-policy shifts.
Concluding perspective
The WiFi modules market is maturing into a bifurcated landscape: high-volume, price-sensitive modules for consumer IoT on one hand; and differentiated, certification-heavy modules for industrial, medical, and automotive segments on the other. With a market expanding from roughly USD 310 million in 2020 to USD 480 million in 2025 and an expected CAGR of ~9.2% through 2032, companies that prepare today—by locking in supplier relationships, rethinking architecture, and integrating regulatory risk into their roadmaps—will convert market growth into sustainable profit pools. PW Consulting’s full report contains the detailed segment breakdowns, supplier scorecards, and the operational templates required to execute these strategies. For decision-makers planning 2026 budgets and roadmaps, the study is a practical guide: it reduces uncertainty, quantifies trade-offs, and translates industry noise into executable actions.
Next steps
Access the full PW Consulting WiFi Modules Market Report to unlock the proprietary segment tables, scenario models, supplier scoring, and downloadable playbooks that underpin the guidance summarized above. The full document is designed as an operational toolkit for product leaders, procurement teams, and corporate strategists who must make high-consequence choices in 2026.
For detailed analysis of this topic, please visit the official page: WiFi Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com