

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gas Turbine Services to Hit USD 52.7B by 2032 at 9.1% CAGR (2026–2032)

Gas Turbine Services Market: A Strategic Lens for 2026 Decision‑Makers
Executive snapshot
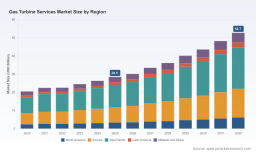
As power and industrial end‑users confront simultaneous pressures — decarbonization mandates, fuel‑stack volatility, and constrained aftermarket capacity — the global gas turbine services market is entering a decisive growth phase. Our base‑year assessment (2025) positions the market at approximately USD 28.5 Billion, and the forecast through 2032 shows sustained expansion (CAGR ~9.1%) to roughly USD 52.7 Billion. That trajectory signals a multi‑year window for commercial repositioning: investments in service capability, lifecycle optimization, and strategic partnerships made in 2026 will materially affect competitive standing across the next decade.
Gas Turbine Services Market
Why 2026 matters: a confluence of demand drivers and supply constraints
2026 is not simply another reporting year — it is a pivot. The serviceable fleet is aging in many mature markets while new high‑efficiency units enter commercial operation. Regulators are tightening emissions and safety protocols, and OEMs and independent service providers are racing to monetize retrofits, digital monitoring, and long‑term service agreements. Simultaneously, limited repair capacity for critical rotating components and a skilled labor shortage are extending lead times and raising repair costs. This combination of expanding service demand and constrained supply underpins the market expansion we quantify in this study, and it explains why many players are accelerating strategic moves now rather than later.
Gas Turbine Services Market
Market trajectory and strategic implications
Our historical review (2020–2025) and forward forecast (2026–2032) reveal three practical takeaways for 2026 planning cycles:
Gas Turbine Services Market
- Growth is broad‑based and durable — the market nearly doubles from the mid‑2020s to 2032, reflecting both routine maintenance needs and a surge in upgrade/retrofit activity tied to emissions and fuel‑flexibility requirements.
- Consolidation dynamics are meaningful — the top three firms account for a majority share of aftermarket services and the top five amplify that concentration. Market concentration favors firms that can combine global parts footprint, repair centers, and technology‑enabled service delivery.
- Operational bottlenecks will be value multipliers — organizations that can secure repair network capacity, invest in workforce upskilling, and implement predictive maintenance platforms will extract disproportionate margin and backlog protection.
Industry dynamics shaping 2026 decisions
Several interlocking dynamics will determine winners and losers in 2026 and beyond. These are not abstract; they translate directly to procurement, contracting, and capital allocation choices.
- Regulatory acceleration: Stricter NOx limits and mandatory emissions monitoring are prompting widespread upgrade cycles. Providers offering retrofit pathways — particularly for ammonia slip control and hydrogen‑blend readiness — are seeing elevated demand for engineering, parts, and long‑term performance guarantees.
- Fuel‑flexibility and hydrogen readiness: Hydrogen blending and hydrogen‑ready retrofit programs are moving from pilot projects to commercial contracts in several jurisdictions. Compliance and certification complexity introduces a premium for validated retrofit solutions and managed risk transfer via service agreements.
- Repair capacity and labor supply constraints: Specialist rotor and component repair capacity remains limited, and skilled labor shortages are prolonging lead times. These constraints elevate the value of regional repair hubs, mobile field teams, and strategic acquisitions that expand capacity.
- Contracting evolution: Long‑term service agreements increasingly bundle emissions monitoring, efficiency guarantees, and digital performance optimization — creating recurring revenue streams but also embedding performance and compliance risk.
Competitive landscape — who matters and why
The market is populated by a mix of legacy OEMs, specialist independents, and diversified aftermarket players. Competitive advantage in 2026 will hinge on the ability to combine global service footprint, retrofit engineering, digital diagnostics, and parts availability. Key market participants profiled in our study include:
- Siemens Energy (München): Full lifecycle services with a strong push into hydrogen‑ready retrofits and digital optimization.
- GE Vernova (Atlanta): Depth in HA‑class fleet support, expanding regional repair footprints and demonstrating large operational hours across its fleets.
- Mitsubishi Power (Tokyo): Long‑term service agreements tied to large power projects and integrated aftermarket support for its turbine platforms.
- Solar Turbines (San Diego): Aeroderivative aftermarket specialist with field services and rapid response capabilities.
- Kawasaki Heavy Industries, Ansaldo Energia, Flowserve, Sulzer, and BHEL: Each brings regional strength, niche technical capabilities, or aftermarket scale that matter to buyers seeking diversified service strategies.
Recent strategic moves underscore the competitive tempo: acquisitions to bolster industrial repair capacity, opening of regional repair centers to shorten lead times, major service contracts tied to new HA‑class plants, and hydrogen retrofit contracts that position incumbents for the energy transition. These developments are analyzed in the report not as news bites but as indicators of capability trajectories and likely market responses to capacity shortages and regulatory shifts.
What the PW Consulting report delivers — practical, decision‑grade tools
Our market study is built to support procurement officers, service line leaders, corporate development teams, and asset owners making capital and contractual commitments in 2026. It emphasizes actionable outputs rather than descriptive narrative.
- Quantitative market model: a bottoms‑up revenue model (2020–2032) with scenario runs for retrofit intensity, fuel‑mix adoption, and repair capacity constraints.
- Demand drivers and sensitivity analysis: mapping how emissions regulations, hydrogen blending targets, and labor lead times alter serviceable addressable market size and timing.
- Competitive playbooks: vendor capability matrices, strategic imperatives for OEMs vs independents, and recommended contracting structures for buyers to allocate risk and protect availability.
- Operational benchmarks: lead‑time and pricing guides for common service scopes, turnaround tradeoffs, and spare parts inventory strategies keyed to fleet characteristics.
- M&A and partnership tracker: recent transactions, capability gaps, and acquisition targets that accelerate entry into constrained repair segments or regional footprints.
- Implementation checklists: procurement templates for long‑term service agreements, retrofit deployment roadmaps, and workforce upskilling programs tailored for 2026 execution.
How executives should use this intelligence in 2026
For executives planning capital cycles or negotiating multi‑year service contracts in 2026, the report supplies a practical playbook:
- Prioritize contractual flexibility that balances performance guarantees with supply chain risk sharing. Where repair capacity is constrained, include clear escalation and capacity assurance clauses.
- Invest in staged retrofit and fuel‑flexibility programs. A phased approach to hydrogen readiness and emissions upgrades preserves optionality while meeting near‑term compliance.
- Leverage digital monitoring to convert maintenance spend into predictability. Providers that combine field services with analytics reduce unplanned downtime risk and create differentiation in bids.
- Consider bolt‑on M&A or strategic alliances to secure repair capacity and regional presence. Recent transactions demonstrate how inorganic moves can compress lead times and increase share of wallet with large asset owners.
- Embed workforce strategies into procurement: contractual training obligations, shared apprenticeship programs, and certification pathways reduce the labor risk premium over time.
Limitations and why deeper segmentation analysis matters
Top‑line market growth and concentration metrics are necessary but not sufficient for precise commercial action. Critical decisions — which regions to localize repairs in, which turbine types to prioritize, and how to price retrofit bundles — require the granular segment economics we reserve for the full report. This "preview" is intentionally designed to show the analytical rigor and to surface the strategic questions; the detailed segmental datasets and model inputs are available in the complete study and will materially influence contract structuring and capital allocation choices.
Bottom line: timing, capability, and risk management
2026 offers a strategic inflection point: the market scale and 9.1% projected compound growth create both opportunity and urgency. Organizations that move early to secure repair capacity, formalize retrofit pathways, and reframe service agreements to meet evolving regulatory and performance expectations will capture durable value. Conversely, delay risks longer lead times, premium pricing, and weaker negotiating leverage as capacity tightens further.
Next steps
PW Consulting has prepared a comprehensive dataset, scenario models, vendor profiles, and executable playbooks to support 2026 decision cycles. For executives who need to convert this market trajectory into contracts, capex plans, or M&A strategies, the full report provides the granular segmentation, pricing matrices, and supplier scorecards required to act with confidence. Access details and sample model extracts are available on our web portal.
For detailed analysis of this topic, please visit the official page: Gas Turbine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com